

Value investor. Bird appreciator.
Tel Aviv
Joined April 2025
- Tweets1.4K
- Following324
- Followers233
- Likes16.5K




Dean retweeted

Very well written fund letter why AI is not fully displacing humans any time soon.
Have heard this from fundamental investors as well as quants. Especially about the velocity of idea (or signal) generation vs finite time for human review.

Dean retweeted

GMS $GMS.L
Implied day rates are approaching a 10-year high🫣
Assuming historical cash conversion, we're generating +$50m/y FCF at steady state now, and +$90m/y three years out. Market cap ~$300m.
p/fcf ~6x
As deleveraging continues, we'll see a transfer of value from debt to equity holders. ✅


Oh Canada...

⏹️Will the diesel crisis get worse?
🔲Who benefited from the loss of Qatari LNG?
⏹️Why are tanker attacks in the Gulf intensifying, and what does that mean for oil prices?
🔲Will Trump’s $8 billion farmer support program offset the diesel crisis?
⏹️Is Trump’s plan to import Russian diesel legal—and does it matter?
⏹️Why is Trump waiving sanctions on Russian oil buyers?
🔲How are record tanker rates crushing Asian and European refiners?
⏹️Can the EU still block Arctic oil and gas development?
🔲Why is US power-grid strain becoming a year-round problem?
🔲Is the Northeast facing a real climate-policy revolt?
⏹️Will Trump’s plan to rehabilitate dark-fleet tankers actually increase oil supply?
🟥Daily Energy Report
Daily Energy Report
afalhajji.substack.com/p/dai…

Dean retweeted

$PVE Executive Chairman and CEO Kevin Bailey joined @MSTFinancial’s Oil & Gas International Exposure Series.
Watch the full replay on our investor hub 👇 povalley.com/activity-update…
#PVE

Despite widespread rioting, an upcoming winter, low storage levels, and natgas prices already at triple their pre-hormuz level, the EU is still committed to the Russian LNG ban taking effect this coming January
Risky but you gotta respect it
$PVE.AX
forbes.com/sites/marktemnyck…


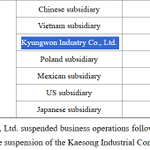
An interesting find. You comb through the filings of a random SK company and you find out they have an inactive overseas subsidiary in North Korea.


Dean retweeted
I have a better idea
$RIG


Lego Maersk Duel-Fuel Container Vessel revealed!
1516 Pieces / $149.99 / 1st March 2026
#Lego #Legonews #Legoleaks

Dean retweeted

RIG's new amended RCF keeps RP leverage and liquidity thresholds unchanged, but with some looser terms adding shareholder-return flexibility
The key dividend driver is VAL merger accelerates deleveraging at close and over the next 12 months as three 7G drillships return to work
- From 5.5x net leverage at YE24, Transocean has deleveraged to ~3x currently, mostly due to converting backlog into cash for debt reduction. The deleveraging aspect of the all-stock merger is key for Transocean; incorporating Valaris’ balance sheet (currently ~1.3x net leverage) should reduce net leverage to ~2.5x at close, with a visible path to ~2.0x by 2Q27.
- After Transocean delivered Atlas, Titan and Aquila (acquired) in 2022-2023, capex has materially declined to maintenance, modest upgrades and SPS levels, which supports meaningful free cash flow (OCF-Capex) averaging ~$180mm per quarter since 2024. The organic deleveraging is likely to continue, which makes underwriting 2x net leverage (covenant definition) by 2Q27 reasonable.
- Further, Valaris’ TTM EBITDA of $424mm represents a cyclical trough, depressed by idle (warm) rigs in TTM period. Operating leverage turns positive over the next 12 months as 7G drillships DS-10 (June 2026), DS-15 (Sept 2026) and DS-18 (4Q26) return to work. Activations are likely to draw on working capital initially, but EBITDA growth is clear, with cash flow to follow.
Transocean avoided this drag because due to its Norway-eligible harsh-environment semisub fleet, a market in which Valaris has no exposure. Valaris’ 7G drillships were hit by delays in West Africa during 2025 but are now scheduled to recover. The combined company has a more diversified fleet, which should lower its cost of capital, all else equal.
- The Net Leverage calculation in Transocean’s RCF credit agreement excludes the $286mm of Restricted Cash on its 6/30/2026 balance sheet. Restricted cash consists largely of Debt Service Reserve Accounts funding the next 12 months of amortization and interest on Transocean’s secured bonds. These funds are structurally dedicated to secured bondholders, not the bank group on Transocean’s revolver so are excluded from its net leverage calculation.
- Transocean’s repayment of its Poseidon, Titan and now Aquila secured bonds both reduces debt and releases restricted cash, which receives no credit under the revolver’s net leverage covenant. The 2030 secured notes had $822mm outstanding at 6/30/26, falling to ~$763mm after the August paydown. With the call premium stepping down from 104.375 to 102.188 in February 2027, a refinancing into unsecureds is logical; eliminating $117.5mm of annual amortization could fund a larger dividend program, though is subject to Board capital allocation policy...

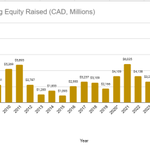
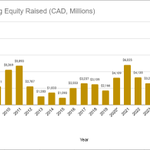
TSX-V equity raises in the mining sector are again at a new all-time high on a TTM basis after 824m CAD (+40% y/y) was raised in September
$OGD.TO $FAR.TO $GEO.TO $MDI.TO


Dean retweeted

A couple years ago there were so many ppl on here excited about deepwater consolidation, yet now consolidation has reached its blue sky outcome and few seem to care.
I view these assets effectively as permanent holds at this point, or at the very least holds until values begin to approach replacement cost. Hard to overstate how much having 80% of supply in the hands of 3 players transforms the industry dynamics for the better. $RIG $NE $SDRL


Dean retweeted

Europe’s Thin Winter Buffer: Can El Niño Ease Rising Reliance on Russian Gas? (with 9 charts)
anasalhajjieoa.substack.com/…

Dean retweeted

$PVE.AX Gas price going ballistic. If gas price settle anywhere near current price & @energy_po get their approvals next month for next 4 wells & the enviornmentals get approved for Teodorico (offshore asset), then this could have one of the best returns on the ASX next year.

Dean retweeted

United States natural gas is down 14% year-to-date, while European natural gas is up 186%.
And some still believe that following European energy policies and taxation will strengthen America.
via Bloomberg


Dean retweeted

The AI boom is increasingly shifting from parabolic to linear growth. Most investors are totally unprepared for that shift. This week, free on the blog app.
bobeunlimited.substack.com/p…

Dean retweeted

Linking pipeline development to “toxic waste” in the title is a choice by @CBC, a poor one, an inflammatory one, and likely violates their editorial standards. No one quoted refers to “toxic waste” and oil sands tailings are not, in fact, hazardous waste.
cbc.ca/news/politics/pacific…

Dean retweeted

$MMY.V 🇨🇦 Q4 FY2026. Weak quarter. Cash now US$109.6m, no bank debt.
Revenue: US$37.0m (−7% YoY)
Gross mine margin: US$23.3m (−21%)
Net income: US$15.5m (−26%)
Operating cash flow: US$13.9m (−27%)
Realised price: US$4,349/oz (+29%)
AISC*: US$1,898/oz (+123%)
Gold produced: 9,902 oz (−20%)
Head grade: 1.48 g/t (−19%)
*Royalties went US$97 → $575/oz. Nearly half the AISC increase.
Mine life extension is the thesis. The MD&A says drilling "may support resource growth potential and future mine life extension." FY27 drilling started in June. Murchison studies continue.
Reserve on file is still from 2018. A resource update is what I'm waiting for.
disc: long


LNG Canada today announced that its Joint Venture Participants have taken a Final Investment Decision (FID) on the LNG Canada Phase 2 expansion project in Kitimat, BC, in the traditional territory of the Haisla Nation tinyurl.com/3ysr2jxy

Dean retweeted

Canada wants to become an energy superpower, and if it has the will, there is a way wsj.com/business/energy-oil/… via @WSJ
