

Earn yield. Build credit. No collateral. Decentralised USDC lending on @arbitrum Audited by @Omniscia_sec
Joined April 2026
- Tweets700
- Following14
- Followers2.6K
- Likes6




Pinned Tweet
Lending built for more.
Avocado Fund is now live on @merkl_xyz with a $5,000 rewards pool running for 10 days.
This campaign will give onchain users the opportunity to supply USDC to the Avocado Fund market on Arbitrum and earn a share of the rewards before it ends on August 21.
Explore the campaign on Merkl: avocado.fund/merkl
Your capital shouldn’t need constant managing.
Some yield strategies keep you coming back to claim and reinvest just to keep your position growing. Avocado Fund removes that extra management through an ERC-4626 vault, where borrower interest is automatically reflected in your avUSDC position as it accrues.
Put the capital to work, not yourself.
Yield shouldn’t cost you flexibility.
Some protocols rely on emissions to keep returns high. Avocado Fund generates lender yield from borrower interest and lets you withdraw without a fixed lockup, so your capital can stay productive without being tied to token rewards.
Let lending do the work.
Capital should have stronger protection.
Security claims mean little without independent review. Avocado Fund’s smart contracts have been reviewed by Omniscia, adding external scrutiny to the infrastructure behind its lending market.
Security shouldn’t come at your expense.
APY should do more for you.
Token incentives can boost a rate without creating lasting lending demand. Avocado Fund generates lender yield from the interest paid by borrowers at a 12% fixed APR, rather than depending on token emissions to fund the return, so you know what is actually driving your yield.
Let borrowing fund the yield.

Capital efficiency should work in your favor.
Lenders earn less when supplied capital sits idle. Avocado Fund puts USDC to work with verified borrowers and delivers 9.7% lender APY, which means more of the pool is actively being used instead of sitting unused.
Make utilization count for lenders.

ONLY 4 DAYS LEFT TO GRAB YOUR SHARE OF $5,000!
If you haven’t joined yet, now’s your chance to enter the @merkl_xyz campaign! Supply USDC on Arbitrum, receive avUSDC, and hold it in your wallet to earn a share of the rewards before the campaign ends on August 21!
The clock is ticking, so what are you waiting for?
Join now: avocado.fund/merkl

Your borrowing behavior should shape your credit.
Risk should not be assessed from collateral alone. The way you manage credit over time gives a clearer picture of how you borrow, and Avocado Fund uses those signals to assess risk and shape credit access accordingly.
Every loan should strengthen what comes next.

Audit Completed!
Our security review with @omniscia_sec is officially complete, strengthening the security of the infrastructure that powers Avocado Fund’s uncollateralized borrowing and lender yield.
Security remains our top priority as we build the future of onchain credit.


🔐 We recently wrapped up a security review for @_AvocadoFund, supporting their vision to enable uncollateralized borrowing and real yield generation.
We look forward to working with their team again in the near future.
Follow @omniscia_sec for more security updates! 🛡️
Platforms ignore the financial history you already built.
Every repayment, every loan, and every onchain decision creates signals about your financial behavior.
Avocado Fund brings these signals together to build a credit profile that evolves with responsible borrowing instead of leaving that progress behind.
Your history should unlock better opportunities.

You can repay every loan on time and still face the same collateral requirement the next time you borrow.
You prove you are reliable, but still get nothing in return.
But what if every repayment unlocked a reward? 👇🏻

Avocado Fund is designed to make your repayment history count.
Your repayment history, account tenure, repayment volume, and credit utilisation contribute to your AVO Score.
As your borrowing behavior improves, your credit profile can grow stronger and unlock better access over time.
Your credit should unlock rewards, not restrictions.
Most lending platforms decide how much you can borrow based on how much you can lock away, rather than assessing you as a borrower.
Avocado uses verified identity and borrowing behaviour to assess credit without requiring collateral first.

Every Loan Builds a Reputation While Platforms Make It Worthless
A borrowing history reveals how credit has been managed over time. Consistent repayments, responsible credit utilisation, and long-term activity all contribute to a stronger financial record.
Blockchain records every transaction, repayment, and interaction, yet many protocols still rely mainly on how much collateral can be locked today. Instead of recognising what has already been proven, they continue measuring access through wallet size.
The information is already there. A borrower’s history shows whether credit was managed responsibly, but most lending models still fail to make that history matter.
Avocado Fund is designed around a different approach through the AVO Score. By combining multiple onchain signals, the AVO Score creates a credit profile that can evolve alongside borrowing behaviour.
The future of lending should not be defined only by who can lock the most capital. It should also recognise who has consistently demonstrated responsibility and managed credit well over time.

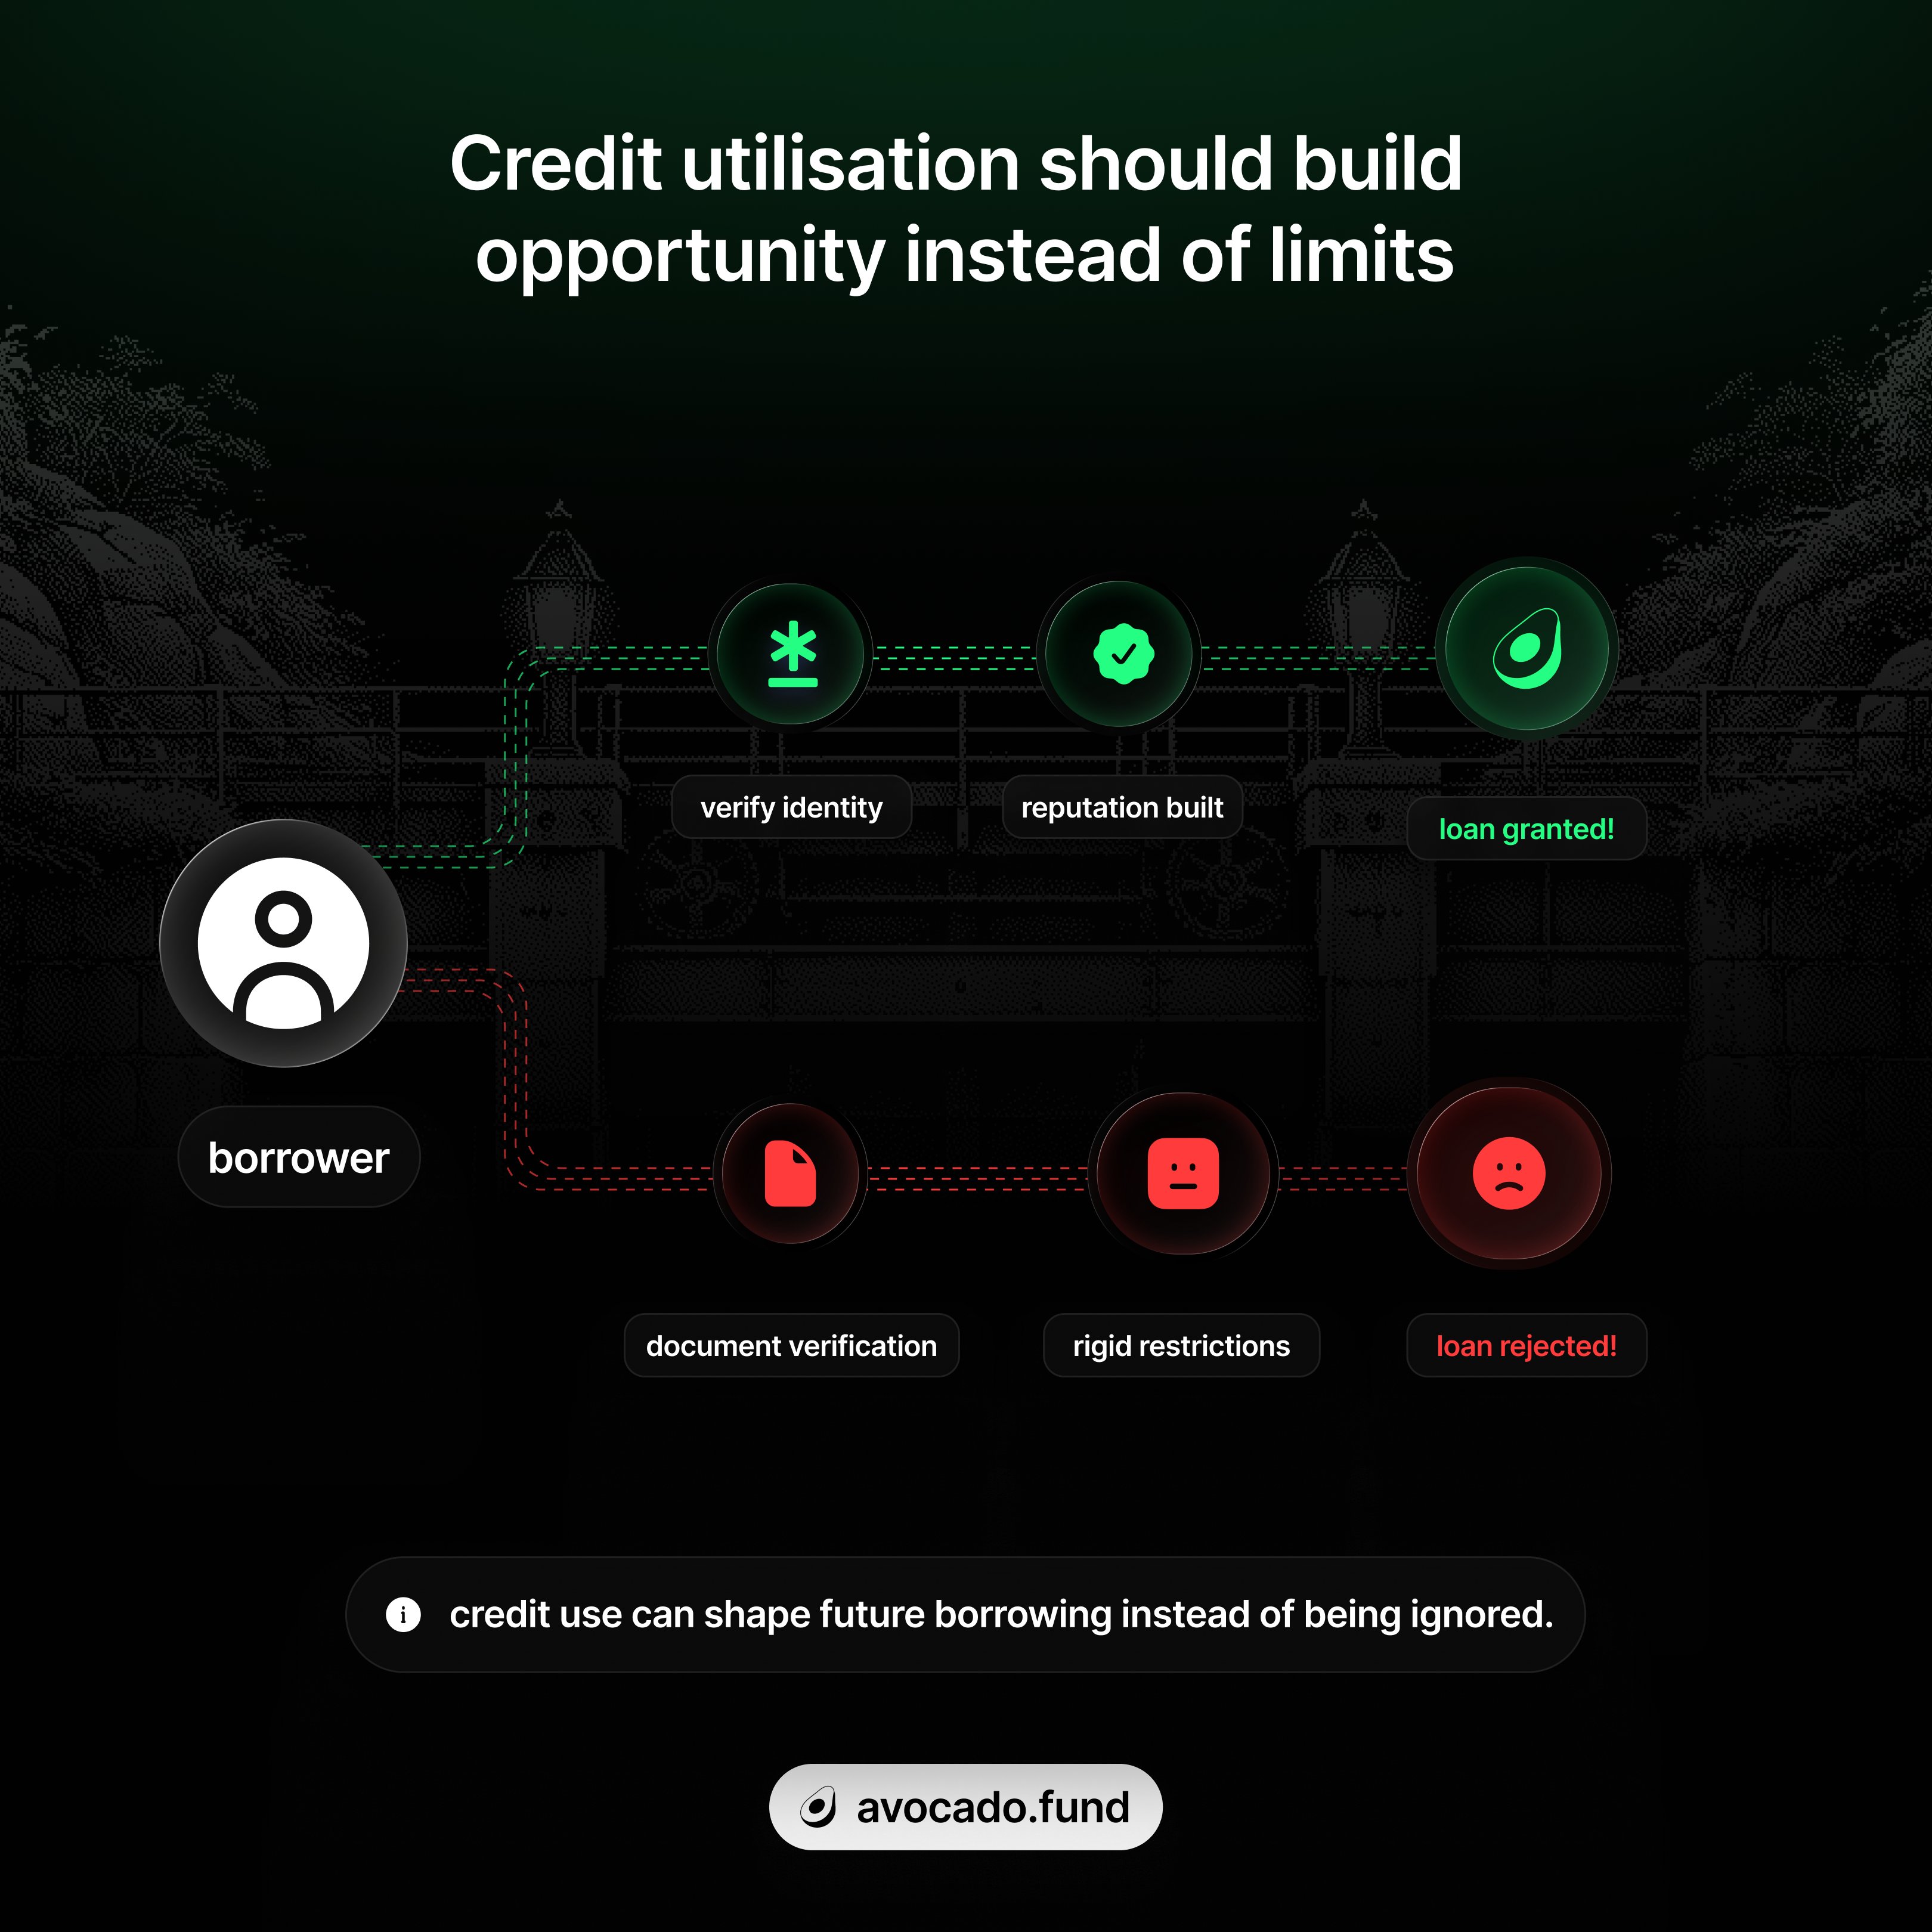
Credit utilisation should build opportunity instead of limits.
How credit is managed can matter just as much as how much is borrowed.
Most lending platforms still rely on:
• Static limits that do not reflect how credit is actually used
• One-size-fits-all assessments that treat every borrower the same
Avocado Fund uses credit utilisation as one of the factors contributing to the AVO Score so responsible credit use can shape future borrowing instead of being ignored.
Traditional credit scores stop where onchain finance begins.
Millions of responsible crypto users have years of onchain activity, yet most lending systems still cannot recognize it.
Instead, they continue relying on outdated ways to assess borrowers.
What if onchain activity finally counted?👇

Not every borrower has a traditional credit history.
Many users have already built a financial record through:
• Borrowing and repayments
• Consistent wallet activity
• Responsible onchain behavior
That history deserves to be recognized, not ignored.


You are losing value when every new loan resets the journey.
Most lending platforms ignore the record already built through responsible borrowing. With Avocado, your repayment history and account activity contribute to your AVO Score so that each loan can strengthen your credit profile over time.
Every repayment should move you closer to better credit.
