
Founder of Zorea Capital. Not investment advice. Views are personal.
Joined May 2021
- Tweets49
- Following64
- Followers12
- Likes16



Interesting comments from Tencent today on why its AI capex should come down in 2028.
Martin Lau expects Tencent to keep using the infrastructure it builds in 2026 and 2027. And if it buys the same equipment in 2028, he expects the price to come down “quite significantly.”
Tencent, just like $ANT, is getting orders of magnitude more out of the compute it already has. As efficiency improves, it expects to train models more efficiently and generate far more tokens from the same facilities. They emphasized this point several times during the call.
#TCEHY is just one company, but its comments point in a different direction than all the 2028 projections we have seen.

45
Interesting comparison between $KKR’s comp expenses and those of the much smaller $TPG.
$KKR generates nearly 3× $TPG’s fee-related revenue. Yet their fee-related compensation + SBC bills are almost identical.
This excludes compensation tied to carried interest, of which employees deserve a reasonably large share.
One way to contextualize $KKR's moat.

93
The market clearly liked CoreWeave’s liquidity outlook. But what a balance sheet: $87.5bn of liabilities against just $4.0bn of book equity.
Four things need to hold up:
• Binding customer commitments.
• Customers’ ability to pay.
• On-time, on-budget capacity delivery.
• Continued access to financing.
A lot needs to go right. Maybe it will, but very little room for error.
$CRWV

27
Simon Bennaim retweeted

🆕 Anthropic $ANT IPO Roadshow (57 slides) available on RetailRoadshow:
netroadshow.com/custom/IPO/A…

Plenty of headlines about memory prices. Here’s some data, 16GB DDR4 RAM kits went from ~$50 to ~$180 in about 18 months. This is a mature, largely commoditized product.
I am not aware of any commoditized manufactured product sustaining this type of price increase without a corresponding increase in input costs.
With $100bn+ in annual memory capex forecast across Samsung, $SKHY , and $MU, capacity is certainly coming online in the next two to three years.

53
O’Leary is the airline GOAT.
“I very much hope that jet (fuel) prices will rise faster into next year because that will accelerate the extent to which other airlines will fail.”
An airline CEO hoping fuel prices continue to rise. Nevermind that jet fuel prices in Europe are at an equivalent of $191 per barrel.
$RYAAY
10
Simon Bennaim retweeted

The complete AI fund flows


Nvidia Gets $690BN, The Other 499 Get $340BN: Tracing Every Dollar Of 2027's AI Capex zerohedge.com/markets/nvidia…

Investor letter 3Q 2026
Our 3Q 2026 Investor Letter is now available. Key highlights include our 3Q performance, why we see our "AI scare basket" as a particularly compelling opportunity, our decision to reduce HCA, and why we have become relatively more constructive on the AI spending supercycle.
zoreacapital.com/post/zorea-…

11
From a conversation with a former $TOI.V employee who reported to Ramon:
Question: How active was Robin in the business?
Answer: Robin was not very active in the business. Only involved in larger acquisitions. Day to day operations fully delegated. Quite invisible.

Anytime a CEO steps down creates uncertainty, but Robin stepping down as $TOI.V CEO seems relatively immaterial. The fact pattern points to someone who wasn't very engaged:
- A 2021 AlphaSense interview already had him relatively checked out "So he works only 2 days a week or so for TSS. And the rest of the week, he works for this family office, Strikwerda AS ."
- He is the Chairman of the Strikwerda Investment Committee.
- In 2024 Strikwerda rolled up some of their businesses into Your.World and made Robin the Chairman and CEO. Subsequently, in early 2025 Your.World raised capital from Ares and Carlyle. My guess is that Ares and Carlyle made sure Your.World is not just a pastime for Robin.
In early 2025 he started stepping down from $CSU.TO related boards. Stepping down from the $CSU.TO board in May 2025 and the $LMN.V board in January 2025. Notably, both before Mark Leonard left $CSU.TO, and right around the time of the Your.World capital raise.
This was well choreographed.
After the announcement, our concern was that maybe he is leaving because of some issue with Mark Miller, which could have negative implications about the continuity of the CSU.TO umbrella culture. We haven't yet seen any indication that this is happening but are doing more work to make sure. We struggle to think of another negative read-through.
Now its up to Ramon Zanders to execute. Ramon has a long and successful track record at $TOI.V and seems to be all-in on the $CSU.TO culture. He owns ~454k shares of $TOI.V so he is well incentivized.
How can $CVNA bulls underwrite the durability of its financing economics?
Carvana recorded $1.2B of gains on loan sales in 2025, against $1.9B of operating income. Their spreads seem to be 200bps-300bps higher than dealer averages.
The only coherent bull case I can see is that 2022 forced Carvana to squeeze every revenue line. Now, with scale and a much cleaner balance sheet, it can let spreads normalize toward industry levels, share efficiency gains with customers, and maintain strong margins on volume.
Curious if there is an argument for why the customer isn’t overpaying relative to what they could get almost anywhere else, and why this dynamic doesn’t add real fragility to the model.
2
1
283
Anytime a CEO steps down creates uncertainty, but Robin stepping down as $TOI.V CEO seems relatively immaterial. The fact pattern points to someone who wasn't very engaged:
- A 2021 AlphaSense interview already had him relatively checked out "So he works only 2 days a week or so for TSS. And the rest of the week, he works for this family office, Strikwerda AS ."
- He is the Chairman of the Strikwerda Investment Committee.
- In 2024 Strikwerda rolled up some of their businesses into Your.World and made Robin the Chairman and CEO. Subsequently, in early 2025 Your.World raised capital from Ares and Carlyle. My guess is that Ares and Carlyle made sure Your.World is not just a pastime for Robin.
In early 2025 he started stepping down from $CSU.TO related boards. Stepping down from the $CSU.TO board in May 2025 and the $LMN.V board in January 2025. Notably, both before Mark Leonard left $CSU.TO, and right around the time of the Your.World capital raise.
This was well choreographed.
After the announcement, our concern was that maybe he is leaving because of some issue with Mark Miller, which could have negative implications about the continuity of the CSU.TO umbrella culture. We haven't yet seen any indication that this is happening but are doing more work to make sure. We struggle to think of another negative read-through.
Now its up to Ramon Zanders to execute. Ramon has a long and successful track record at $TOI.V and seems to be all-in on the $CSU.TO culture. He owns ~454k shares of $TOI.V so he is well incentivized.


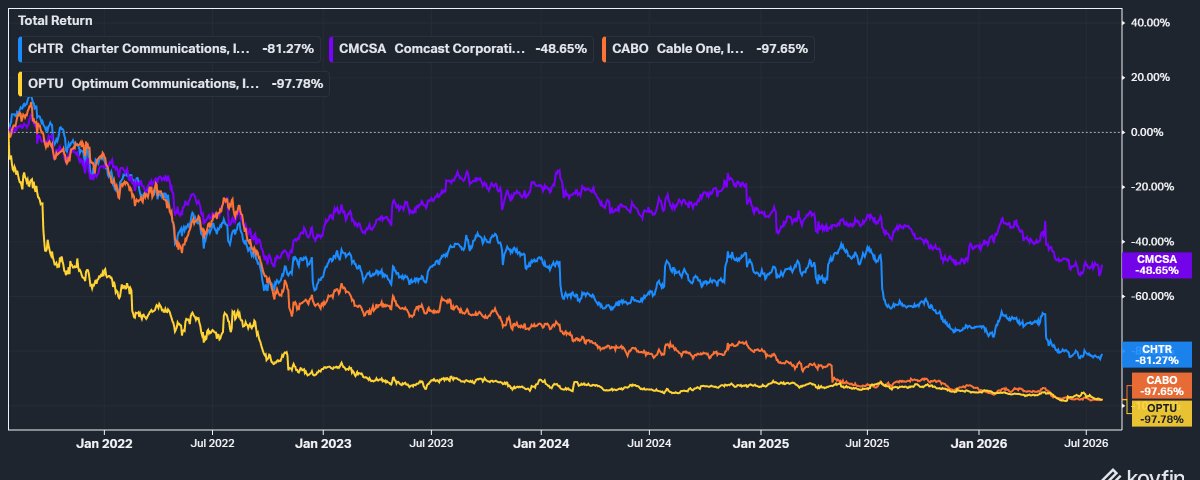
For all of Europe’s inefficient overregulation, #Telecom is an interesting counterexample; regulation has significantly lowered consumer prices without a commensurate sacrifice in service quality, even as it crushes industry returns.
Telecom services in parts of Europe cost as little as one-third of comparable US services. Yet Spain and Romania have approximately 95% fiber coverage versus 55% in the US. Geography explains some of the difference, but regulation and market structure appear more important.
The flip side is poor industry returns. Yet operators keep investing and torching capital (with consent of their shareholders). Not the outcome you would expect.
$TEF $ORAN $VOD

24
Simon Bennaim retweeted
Senior care EHR product VP on nurses who quit rather than learn a rival system ($CSU)

Buffett's “Never lose money” quote may be one of the most misquoted and misunderstood ideas in investing.
Our latest letter explores the difference between position-level risk and portfolio-level risk, and why trying to avoid uncertainty in every individual decision does not necessarily produce the safest overall outcome.
We believe this distinction is important for anyone allocating capital, whether in a business, an investment portfolio, or their personal life.
@iancassel reading recently reading one of your posts motivated me to write this.
zoreacapital.com/post/never-…

Investor letter 2Q 2026
Our 2Q 2026 Investor Letter is now available. Key highlights include our 2Q performance, updated look-through metrics of our portfolio, and a look at some of the market exuberance we are witnessing today ($MU).
zoreacapital.com/post/zorea-…

23
Simon Bennaim retweeted

AI IPO mania has begun. Even that Shark Tank dude from the ping-pong movie who got $15 million from Sam Bankman-Fried and FTX is building data centers. It’s worth remembering the story of Global Crossing, filled with ghosts of Wall Street’s past.
wsj.com/opinion/the-hallucin…
@ylecun @mustafasuleyman @elonmusk @sama @openai @GoogleDeepMind @AnthropicAI @Meta @ajassy @nvidia @geoffreyhinton @demishassabis @gdb @ESYudkowsky @ericschmidt @AndrewYNg @drfeifei @finkd @ajassy @emollick @miramurati @thinkymachines @JohnStossel @steve_hanke @CliffordAsness @AndrewLilico @lymanstoneky @tylercowen @FelixSalmon #EconTwitter @adam_tooze @Austan_Goolsbee @JustinWolfers @elerianm @yardeni @TruthGundlach

We have become increasingly positive about a subset of software companies in an era of AI. Those with proprietary workflows, strong distribution, valuable data, deep integrations, embedded customer relationships, reasonable pricing, and management teams that are moving quickly.
Our view is that, for many applications, AI models will become a core part of the application technology stack. Comparable to how cloud infrastructure became integral to SaaS business models. In that world, AI is not necessarily a replacement for software companies, but a capability they can embed into their products, workflows, and customer experiences.
We recently listened to an interview with Anthropic CFO Krishna Rao that reinforced this framing. Anthropic appears to be positioning itself mostly as a horizontal AI platform, albeit with some applications. Customers can access Claude to incorporate model intelligence into their own products and operations.
We expect software and developer-tool companies to be among Anthropic’s most important commercial customers. In that context, Anthropic’s strategy makes sense: rather than trying to disrupt application-layer companies directly, Anthropic can become an essential part of their infrastructure. A toll road.
That does not mean every software company benefits. Some applications will be enhanced by AI, while others may be commoditized or displaced by it. We think the software sector is increasingly becoming a market for picking winners and losers.