

Focus on quality US compounders and durable businesses. In-depth analysis, clear thinking, long-term perspective. No hype — just better investment decision
New York, USA
Joined September 2010
- Tweets178
- Following36
- Followers342
- Likes552








I’m still firmly bullish on NVDA! Added another 1,000 shares today — total position now 3,000 shares.🔥
NVDA has pulled back recently after the board launched an independent investigation related to reports involving Jensen Huang, and the stock dropped noticeably (at one point down sharply intraday). Market sentiment got a bit shaky. But I’m focused on the fundamentals:
Last quarter revenue hit $96.2 billion, up 106% year-over-year, with Data Center soaring 117% to $89 billion — still extremely strong.
Company guided roughly $108 billion in revenue for the next quarter. AI demand remains robust, and the Vera Rubin platform is progressing.
Analysts are still mostly Buy-rated, with average price targets well above current levels.
The company continues advancing sovereign AI infrastructure collaborations (including NVLink Fusion in Korea and elsewhere). Its long-term leadership in AI compute is intact.
Short-term noise (personal matters investigation, market sentiment) vs. the long-term AI infrastructure supercycle — I’m choosing the latter. The pullback actually gave a good opportunity to add, so I bought more today.
The AI wave is just getting started. NVIDIA’s moat and execution remain top-tier. Short-term volatility is normal — I’m holding for the long term.
If you also hold NVIDIA, follow me for timely updates and position insights!
$NVDA #NVIDIA #AI

Ignore the FUD. Focus on the signal. 🚨
$IREN $NBIS $CIFR $WULF
When AI infrastructure contracts command $22M per MW with 90% GPU CapEx prepayments, that's not noise. That's a powerful signal.
Steve Jobs understood the difference between signal and noise.
Stop chasing headlines. Stop getting distracted by market noise.
Pay attention to what's happening on the ground.
𝗙𝗼𝗰𝘂𝘀 𝗼𝗻 𝘁𝗵𝗲 𝘀𝗶𝗴𝗻𝗮𝗹. 🎯

🚨 Those shorting $IREN may be underestimating its upside potential!🔥
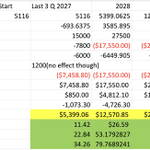
According to analyst forecasts, even at a price-to-book (P/B) ratio of 1x, $IREN could potentially deliver a 5x return by the end of 2030.
This model is based on the following assumptions:
🔥 An additional $15 billion in data center and GPU assets.
📈 A turnaround to profitability by next year.
⚡ Continued business expansion fueled by prepayments, debt, and operating cash flow.
Currently, the market is primarily focused on near-term execution risks.
But what happens if $IREN’s massive investments in artificial intelligence (AI) infrastructure begin to translate into tangible earnings?
The long-term upside could far exceed what the bears anticipate. 🚀
I am bullish on the long-term potential of $IREN.
#IREN #AI #DataCenter #Investing


$INTC – key chart after the crash.🔥
MOAT trendline forming.
Still testing 54–57 support.
Higher lows? Bounce time??
Either bounce or wait and see.

$NBIS
Cantor Fitzgerald’s analysis of $IREN’s earnings:
In the medium term, the market sell-off has been driven by a reduction in the number of data centers under construction. In our view, however, this actually increases demand for existing computing resources—an area in which IREN is well-positioned.
$NBIS
$IREN
If you hold either of these stocks, follow me for more timely updates.

🚨 $ASTS — THE GLOBAL EXPANSION IS JUST GETTING STARTED!
Have you noticed this?
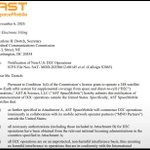
AST SpaceMobile has notified the FCC that international Direct-to-Cell operations are expected to begin imminently with MNO partners.
🇯🇵 Japan
🇬🇧 UK
🇰🇪 Kenya
🌍 More markets ahead!
This is more than a headline. It's a major step toward bringing ASTS's satellite network to customers beyond the U.S.
While the market focuses on rockets, the real opportunity is a global mobile network in the making.
I'm increasingly bullish on $ASTS. The long-term potential could be massive!
#ASTS #Space #Satellite #Telecom


I fully agree with this comparison; it is the core logic behind why I remain firmly bullish on INTC. The Intel of today is no longer the Intel of eight years ago—a company solely focused on PC chips and squeezed on two fronts by AMD and TSMC.
With Q3 revenue reaching $16.5 billion (up 21% year-over-year), a data center business so strong that demand outstrips supply, the 18A process node progressing, the 14A PDK 0.9 already released to customers, and the CEO himself making significant, repeated personal stock purchases—these are tangible, substantive changes. The market has currently priced in various "noises"—such as short-term weakness in the PC market, a soft Q4 outlook, and memory shortages—driving the valuation of a company undergoing a fundamental business transformation back down to levels seen eight years ago. History often repeats itself in this regard: when a company shifts from being driven by "legacy businesses" to "new growth engines," the market frequently continues to apply an old valuation multiple rather than accounting for the premium warranted by the new growth narrative. My bullish stance on INTC isn't based on the idea that it’s "cheap because it has fallen a lot," but rather on the fact that it is a fundamentally different company than it was eight years ago—yet it is still trading at the same price. It’s the same price, but a completely different underlying quality—that is what truly warrants a closer look. What’s your take on this comparison? Do you think the market is undervaluing the company, or do you believe the transformation has yet to fully materialize?

$INTC 8 years ago:
• $55/share
• Primarily an x86 CPU & PC business with no external foundry business or outside backing & no meaningful AI growth engine
$INTC today:
• $55/share
• A centerpiece of America's push for domestic advanced chipmaking backed by U.S. government & $NVDA with Data Center & AI revenue just posting its strongest growth in 15 years
Same price. Very different business.


🚨 BULLISH NEWS FOR $IREN!
IREN is bringing a NEW liquid-cooled data center to Arizona!
🔥 Another major step in its AI infrastructure expansion.
$IREN's AI growth story keeps getting bigger!
#IREN #AI #DataCenters


🔥This interview focuses on Keel Infrastructure’s ($KEEL) Q3 2026 financial results and 2027 strategy. Ben Gagnon (@CaptainKeel) highlighted several key points: Q3 progress—construction has broken ground at Moses Lake (with all permits secured; the site is expected to generate its first HPC-related revenue by 2027). In Pennsylvania, the permitting process continues to advance, with no applications rejected. Lease negotiations across multiple sites with various counterparties are well underway, with technical due diligence completed and several Letters of Intent (LOIs) already in hand.
Regarding the leasing timeline: The previous goal of signing three leases by year-end has been adjusted; the focus has shifted toward securing the "highest-quality, highest-return" deals, with significant progress anticipated by early 2027.
Market dynamics and supply/demand: Power is becoming increasingly scarce while demand has reached an all-time high, leaving customers with fewer viable options for 2027–2028. Keel foresaw this supply-demand imbalance two years ago and pivoted its entire strategy accordingly.
Design and execution: The company is maintaining flexibility for next-generation GPUs (such as the Vera Rubin architecture), fostering competition among multiple potential counterparties to avoid long-term exclusivity, and leveraging a strong cash position (approx. $780 million) to drive development without the need for external financing.
Other topics covered include the political and labor union landscape in Pennsylvania, GPU rental rate dynamics, capital allocation options, and investor feedback.
Closing sentiment: Despite significant market volatility, the company’s operational execution and the progress made at the negotiating table remain far more stable than the stock price. Management remains composed—this is precisely the moment they have been preparing for.
Core thesis for the outlook (my perspective):
Power is the true bottleneck of the AI era, and Keel holds a portfolio of scarce, permitted (or near-permitted) power-ready sites, backed by ample cash and active construction. While market sentiment is currently dampened by lease delays and share price volatility, the announcement of a first lease or further progress at Moses Lake could serve as a powerful catalyst. Execution is everything, and for now, it appears the company is advancing exactly according to plan.
🚨 $INTC
— Kevin Hassett, Director of the White House National Economic Council (NEC), stated today that President Trump is enthusiastic about the "agreement with Intel," adding that it is "very encouraging to see Intel showing sustained and strong improvement." Coming just about a week after Intel’s weak guidance triggered a sharp sell-off, this marks another clear signal of strong support from the U.S. government. With the government projected to hold an approximately 9.9% stake by 2025, it remains firmly confident in the company’s long-term transformation and recovery. Short-term pressures in the PC market and supply chain are merely "noise"—the long-term potential remains clear. For those holding $INTC, there is no need to be overly concerned.
Follow me for the latest news and policy updates. Like + Follow + Share

$INTC Position Update 🔥
Just added another 2,000 shares of $INTC yesterday.
Now sitting on 6,000 shares total.
CEO Lip-Bu Tan just bought $9.7 million worth at around $64.73.
That tells me management still believes in the long-term turnaround.
I’m still bullish on Intel’s long-term potential. The problems are real, but the CEO putting real money to work at these levels is a strong signal.
If you’re also holding $INTC, follow me. I’ll keep sharing the latest updates.

Yieldfield retweeted

HASSETT, director of the White House National Economic Council, said Trump is excited about the agreement with $INTC Intel. It was encouraging to see Intel show a sustained strong improvement.

$INTC 🔥
INTEL CTO PUSHKAR RANADE ON WHY AI INFERENCE CAN'T SCALE 10X AT THE LEADING EDGE:
Asked if there are enough tools in the world to 10X leading edge inference output:
"Not 10X, but probably like 2X, yes"
He says the whole supply chain would have to scale together:
"Unless the entire supply chain, starting from the equipment suppliers, their suppliers, their sub-suppliers, unless everybody produces, you can't increase the output collectively"

$CRWV
CEO confirmation that the political shift carries zero risk to its backlog outlines a massive structural ceiling on regulatory or policy concerns for infrastructure plays.
Watching CRWV fall with the broader market is frustrating, but my confidence in its long-term business hasn't changed.
While the market gets distracted by post election noise, the true operational signal lies in CRWV capacity gap bridging the gap between 1.5 GW of active power and 4.2 GW of contracted capacity signed as of August 2026.
The core investment thesis depends on conversion velocity how efficiently they can construct these physical data center shells, deploy GPU hardware, and clear acceptance gates to transition commitments into billed cash flows without burning through expansion capital.

🚨 $IREN’s >35 GW PIPELINE 🚨
THEY FINALLY DID IT.
After years of investors begging, pleading, and screaming for management to just tell us the size of their power pipeline… they dropped it.
And holy shit.
Over 35 GW.
Let that sink in.
No other neocloud comes close.
No colo provider comes close.
Nobody in this entire space has anything even remotely like this.
It only took the stock getting crushed 58% YTD for them to finally reveal one of the most important pieces of information in the entire AI infrastructure race.
But I’m not even mad.
I’m impressed as hell.
This is the same company that just printed its first real AI earnings beat, locked in $22M/MW 5-year deals with 90% GPU prepayment, and is sitting on a $20B+ backlog with Microsoft and NVIDIA.
And now they casually drop that they’re sitting on a 35+ GW pipeline.
This isn’t just a good report.
This is a statement.
$IREN just reminded everyone why they’ve been one of the most underappreciated names in the entire AI buildout.
The pipeline is real.
The demand is real.
The execution is finally showing up.
Respect. Absolute respect. 🔥
#IREN #AIInfrastructure

AI long-term logic hasnt changed. The test for chip stocks may just be starting. 🔥
Goldman showed consensus expectations. Big cloud free cash flow turns negative in 2026, pressure peaks in 2027, and could turn positive again in 2028.
Look at $INTC. From the 90s down to around $60. Dropped about a third in a few trading days.
Long-term semiconductor opportunity is still fine.
The market is just starting to care more about cash flow and valuation.
Same for the main cloud names we track.
This could turn into a longer fight. Less leverage, protect capital, then wait for the industry returns to show up.
The process is tough though.

