

Invest with VISION | Knowledge based Wealth Creation | No recommendations | All views for educational purpose | Not SEBI registered
Joined December 2023
- Tweets575
- Following77
- Followers12.8K
- Likes299



Pinned Tweet
𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (Alpha Ideas Meet Update)
Summary: 🗒️
▪️CDMO with major 𝐟𝐨𝐫𝐦𝐮𝐥𝐚𝐭𝐢𝐨𝐧𝐬 𝐑&𝐃 𝐝𝐨𝐧𝐞 𝐢𝐧-𝐡𝐨𝐮𝐬𝐞 𝐰𝐢𝐭𝐡 𝐈𝐧𝐟𝐥𝐮𝐱 𝐫𝐞𝐭𝐚𝐢𝐧𝐢𝐧𝐠 𝐨𝐰𝐧𝐞𝐫𝐬𝐡𝐢𝐩✅ & high customer stickiness
▪️𝐁𝐫𝐨𝐰𝐧𝐟𝐢𝐞𝐥𝐝 𝐞𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧 𝐛𝐲 𝟔𝟎% 𝐜𝐨𝐦𝐩𝐥𝐞𝐭𝐞𝐝 - to drive FY26 growth
▪️Greenfield expansion by Mar’26 to take overall 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝐭𝐨 𝟐.𝟓-𝟑𝐱 𝐨𝐟 𝐜𝐮𝐫𝐫𝐞𝐧𝐭 𝐭𝐫𝐚𝐧𝐬𝐥𝐚𝐭𝐢𝐧𝐠 𝐭𝐨 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐩𝐨𝐭𝐞𝐧𝐭𝐢𝐚𝐥 𝐨𝐟 𝟒𝟓𝟎-𝟓𝟎𝟎𝐂𝐫𝐨𝐫𝐞✅✅
▪️Onboarded clients like 𝐄𝐫𝐢𝐬 𝐋𝐢𝐟𝐞𝐬𝐜𝐢𝐞𝐧𝐜𝐞 (24,000Cr MCap Co), 𝐋𝐚 𝐑𝐞𝐧𝐨𝐧 (𝐂𝐡𝐫𝐲𝐬𝐂𝐚𝐩 𝐛𝐚𝐜𝐤𝐞𝐝), among others
▪️Targeting other high growth consumer segments like 𝐂𝐨𝐬𝐦𝐞𝐭𝐢𝐜𝐬, 𝐏𝐞𝐭 𝐟𝐨𝐨𝐝, 𝐞𝐭𝐜
▪️1st in Maharashtra to get FSC 22000 approval in food category - unlocks 𝐝𝐢𝐫𝐞𝐜𝐭 𝐚𝐜𝐜𝐞𝐬𝐬 𝐭𝐨 𝐔𝐒𝐀, 𝐄𝐔, 𝐞𝐭𝐜
(Further, my analysis on projections FY26E to FY28E at the end)
__________________________________
Detailed notes: 📝
𝐅𝐨𝐫𝐦𝐮𝐥𝐚𝐭𝐢𝐨𝐧 𝐝𝐫𝐢𝐯𝐞𝐧 𝐢𝐧𝐧𝐨𝐯𝐚𝐭𝐢𝐨𝐧:
1. Influx is the owner of the formulation with majority of the customers.
2. Eg for Gummies, Protein Bars, etc all base formulations R&D done by Influx
3. Customer stickiness due to importance of taste, texture etc in such products & customer needs consistency
𝐀𝐩𝐩𝐫𝐨𝐯𝐚𝐥𝐬:
1. FSC 22000 - 1st in Maharashtra to get this certification in food category - unlocks direct access to USA, EU, etc
2. First to get Nigeria approval in food category
𝐂𝐮𝐬𝐭𝐨𝐦𝐞𝐫𝐬:
1. Serving the top D2C brands such as Carbamide Forte (avg 5-10k ratings per product on Amazon), Tata 1mg, etc
2. Recently onboarded marquee clientele such as Eris Lifescience (24,000Cr MCap co), La Renon (ChrysCap backed), among others
𝐍𝐞𝐰 𝐩𝐫𝐨𝐝𝐮𝐜𝐭𝐬:
1. Got approval for Aerosols in March’2025
2. Cosmetics is an area of focus - have developed capabilities for colour cosmetics
3. Pet food is an emerging market - not easy to crack and Influx has been investing in this since 2022 and expect to reap rewards now
𝐂𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝐄𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧:
1. 𝘽𝙧𝙤𝙬𝙣𝙛𝙞𝙚𝙡𝙙 - 𝘾𝙤𝙢𝙥𝙡𝙚𝙩𝙚𝙡𝙮 𝙤𝙛 𝙞𝙣𝙩𝙚𝙧𝙣𝙖𝙡 𝙖𝙘𝙘𝙧𝙪𝙖𝙡𝙨
- Capacity at existing unit increased by 60% *
- Includes new granulation line, capsule line (increases capsule capacity by 4x)
▶️So revenue potential in my view should be 170-180Cr from this unit
2. 𝙂𝙧𝙚𝙚𝙣𝙛𝙞𝙚𝙡𝙙 - 𝙊𝙪𝙩 𝙤𝙛 𝙄𝙋𝙊 𝙛𝙪𝙣𝙙𝙨:
- Expected completion by Mar’25/Apr’25
- This unit will increase overall capacity by 2.5-3.0x
⏩️So revenue potential from both units will be 450-500Cr
View on Promoter Mr Munir: Superb clarity & immense Passion for the business
____________________________________
No projections shared by management. But my view:
𝐅𝐘𝟐𝟔𝐄: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝟏𝟕𝟎-𝟏𝟖𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟐𝟑-𝟐𝟓𝐂𝐫✅ (Brownfield expansion)
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝟐𝟖𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟒𝟎-𝟒𝟐𝐂𝐫✅
(New unit at 40-50% utilisation)
𝐅𝐘𝟐𝟖𝐄: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝟒𝟓𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟔𝟎-𝟔𝟓𝐂𝐫
(Ramp up new unit to 85-90% utilisation)
A very strong consumer wellness co trading at 15x FY26E ; 9x FY27E vs peers / proxies at 30-35PE
______________________________________
* Unlocked 40% of capacity at existing unit i.e. utilisation which was 93% would now be at 53-55%. This means 60-65% increase in overall capacity
NOTE: Not a buy / sell reco | DYODD


𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (Update)
A 𝐑𝐚𝐫𝐞 𝐂𝐃𝐌𝐎 / 𝐍𝐮𝐭𝐫𝐚𝐜𝐞𝐮𝐭𝐢𝐜𝐚𝐥𝐬 𝐩𝐥𝐚𝐲𝐞𝐫 𝐥𝐢𝐬𝐭𝐞𝐝 𝐢𝐧 𝐒𝐌𝐄 𝐬𝐩𝐚𝐜𝐞
Main Board quality company on SME platform
✅Promoter quality + Manufacturing facility - Both are TOP Notch
Detailed analysis👇🏻
________________________________
Co is engaged in CDMO (end-to-end right from 𝐝𝐞𝐯𝐞𝐥𝐨𝐩𝐦𝐞𝐧𝐭 𝐨𝐟 𝐟𝐨𝐫𝐦𝐮𝐥𝐚) for Nutraceutical brands
🔹𝐒𝐞𝐫𝐯𝐢𝐧𝐠 𝐭𝐨𝐩 𝐧𝐮𝐭𝐫𝐢𝐭𝐢𝐨𝐧 𝐛𝐫𝐚𝐧𝐝𝐬 𝐢𝐧𝐜𝐥:
1. Carbamide Forte (products - superb ratings on Amazon)
2. Divine nutrition - one of a well known brand in supplement etc
3. In talks with ON nutrition (US based- considered one of the top of industry)
🔹𝐕𝐞𝐫𝐲 𝐬𝐭𝐫𝐨𝐧𝐠 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐦𝐨𝐝𝐞𝐥:
- Net debt free
- Historical consistent Operating Cash Flows (OCF) to EBITDA of 50-60%
- Continuous capex over last 3-4 yrs funded out of internal accruals
🔹𝐄𝐦𝐞𝐫𝐠𝐢𝐧𝐠 𝐬𝐞𝐠𝐦𝐞𝐧𝐭𝐬 - 𝐂𝐨𝐬𝐦𝐞𝐭𝐢𝐜𝐬 (𝐡𝐢𝐠𝐡𝐞𝐫 𝐦𝐚𝐫𝐠𝐢𝐧) & 𝐕𝐞𝐭𝐞𝐫𝐢𝐧𝐚𝐫𝐲
- Setting up separate lines for these out of IPO funds
- Focus is on increasing this contribution from 5% currently to 15-20% in next 3 yrs
🔹Capex from IPO funds : 𝟐.𝟓𝐱 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝐛𝐲 𝐀𝐩𝐫’𝟐𝟔 (9 months from now)
- 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐩𝐨𝐭𝐞𝐧𝐭𝐢𝐚𝐥 𝐨𝐟 𝟓𝟎𝟎-𝟓𝟓𝟎𝐂𝐫 ✅ 𝐩𝐨𝐬𝐭 𝐜𝐚𝐩𝐞𝐱
🔹Financials/Projections (conservative):
FY25: Rev 105Cr ; PAT 13.4Cr
FY26E: Rev 175Cr ; PAT 23-24Cr✅
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯 𝟐𝟔𝟓𝐂𝐫 ; 𝐏𝐀𝐓 𝟑𝟖-𝟒𝟎𝐂𝐫 ✅
Margin profile in line with peers like Zeon Lifesciences (unlisted) gives additional comfort
🔹Peer comparison (can check tagged tweet) - 𝐭𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝟔𝟎% 𝐝𝐢𝐬𝐜𝐨𝐮𝐧𝐭 𝐭𝐨 𝐨𝐭𝐡𝐞𝐫 𝐂𝐃𝐌𝐎 / 𝐜𝐨𝐧𝐬𝐮𝐦𝐞𝐫 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭 𝐦𝐟𝐫𝐬
- No direct competitors, covered proxies (CDMO pharma, Nutraceutical brand owners, Consumer contract mfr)
_________________________________
Disc: Not a buy / sell reco | DYODD


𝐋𝐓 𝐄𝐥𝐞𝐯𝐚𝐭𝐨𝐫 𝐂𝐌𝐏 𝟐𝟐𝟎
𝐓𝐡𝐞 𝐨𝐧𝐥𝐲 𝐥𝐢𝐬𝐭𝐞𝐝 𝐄𝐥𝐞𝐯𝐚𝐭𝐨𝐫 𝐜𝐨𝐦𝐩𝐚𝐧𝐲
Currently mainly doing B2G and B2B
But, recently acquired Ricardo Elevators, which is a 𝐬𝐭𝐫𝐨𝐧𝐠 𝐩𝐥𝐚𝐲𝐞𝐫 𝐢𝐧 𝐇𝐨𝐦𝐞 𝐄𝐥𝐞𝐯𝐚𝐭𝐨𝐫𝐬 (𝐁𝟐𝐂)
- Home Elevators is a 2000Cr market seeing much stronger growth than traditional elevator market
- This is a brand play which entails higher multiples
✅Ricardo’s 𝐦𝐨𝐧𝐭𝐡𝐥𝐲 𝐨𝐫𝐝𝐞𝐫 𝐢𝐧𝐟𝐥𝐨𝐰 𝐫𝐮𝐧 𝐫𝐚𝐭𝐞 𝐚𝐭 𝟔𝐂𝐫
✅𝟏𝟖+ 𝐞𝐱𝐩𝐞𝐫𝐢𝐞𝐧𝐜𝐞 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 𝐚𝐜𝐫𝐨𝐬𝐬 𝐈𝐧𝐝𝐢𝐚
𝐄𝐱𝐩𝐞𝐜𝐭𝐢𝐧𝐠 𝐬𝐭𝐫𝐨𝐧𝐠 𝐬𝐲𝐧𝐞𝐫𝐠𝐢𝐞𝐬:
LT’s R&D, Manufacturing , execution capabilities
+
Ricardo’s product range, Brand and retail presence
Video below gives a gist of Ricardo (it’s a bit dated)
___________________________________
Massive expansion:
LT has plans to expand its manufacturing facility to 𝟐.𝟓𝐱✅ 𝐨𝐟 𝐢𝐭𝐬 𝐜𝐮𝐫𝐫𝐞𝐧𝐭 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲 (to commence in 12 months)
FY26E: Rev 110Cr ; PAT 17Cr
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯 𝟐𝟐𝟎𝐂𝐫 (𝐢𝐧𝐜𝐥 𝐑𝐢𝐜𝐚𝐫𝐝𝐨) ; 𝐏𝐀𝐓 𝟑𝟒𝐂𝐫✅
(Based on order book - ss 3)
Not a buy / sell reco | DYODD


𝐓𝐚𝐮𝐫𝐢𝐚𝐧 𝐌𝐏𝐒 (Update)
I have added at these levels (after a guidance cut, stock has been hammered disproportionately)
Recent positives:
1️⃣Appointed Anand Mohan as Global Sales Head - prior experience 7yrs at Propel (one of the leading domestic competitors - 𝐡𝐞𝐥𝐩𝐞𝐝 𝐠𝐫𝐨𝐰 𝐭𝐡𝐞 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐟𝐫𝐨𝐦 𝟑𝟎𝟎 𝐭𝐨 𝟏𝟓𝟎𝟎 𝐂𝐫 𝐢𝐧 𝟕𝐲𝐫𝐬)
2️⃣Orders worth 34 Cr won in Dec’25, expecting most to be shipped out in Q4 itself
𝐓𝐚𝐮𝐫𝐢𝐚𝐧 𝐬𝐡𝐨𝐮𝐥𝐝 𝐬𝐭𝐢𝐥𝐥 𝐚𝐜𝐡𝐢𝐞𝐯𝐞 𝟏𝟎𝟎-𝟏𝟏𝟎𝐂𝐫 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐰𝐢𝐭𝐡 𝟏𝟔-𝟏𝟕𝐂𝐫 𝐏𝐀𝐓 𝐢𝐧 𝐅𝐘𝟐𝟔 & 𝐬𝐡𝐨𝐮𝐥𝐝 𝐠𝐫𝐨𝐰 𝐚𝐭 𝐂𝐀𝐆𝐑 𝐨𝐟 𝟒𝟎%+ 𝐨𝐯𝐞𝐫 𝐧𝐞𝐱𝐭 𝟐-𝟑 𝐲𝐫𝐬
𝐂𝐨𝐦𝐩𝐚𝐧𝐢𝐞𝐬 𝐰𝐢𝐭𝐡 𝐭𝐡𝐢𝐬 𝐤𝐢𝐧𝐝 𝐨𝐟 𝐩𝐫𝐨𝐝𝐮𝐜𝐭, 𝐢𝐧𝐟𝐫𝐚 & 𝐥𝐞𝐚𝐝𝐞𝐫𝐬𝐡𝐢𝐩 𝐠𝐞𝐭 𝟐𝟓-𝟑𝟎 𝐏𝐄
(Covered in detail below)
Current MCap just 210Cr
___________________________________
1️⃣𝐒𝐮𝐩𝐞𝐫𝐢𝐨𝐫 𝐩𝐫𝐨𝐝𝐮𝐜𝐭:
- Among the top domestic players in this segment. Competing with likes of Propel, Puzzolana, etc
- High acceptance in export markets gives further conviction on its product quality
2️⃣𝐒𝐭𝐚𝐭𝐞 𝐨𝐟 𝐭𝐡𝐞 𝐚𝐫𝐭 𝐟𝐚𝐜𝐢𝐥𝐢𝐭𝐲:
- 110,000 sqft automated facility
- Strong In house R&D capabilities
- Revenue potential of 250Cr+ from existing infra itself
3️⃣𝐏𝐫𝐨𝐟𝐞𝐬𝐬𝐢𝐨𝐧𝐚𝐥 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭:
- Covered above - appointed sales head of Propel
✅This move will help boost exports in markets like Africa, Russia, Middle East (exports was impacted due to US tariffs)
Ground level checks done with the competitors on the product, business seasonality , etc all of which checks out
No buy / sell reco | DYODD


𝐓𝐚𝐮𝐫𝐢𝐚𝐧 𝐌𝐏𝐒 - 𝐂𝐌𝐏 𝟐𝟓𝟓
(MCap 227 Cr)
Sector - Capital Goods 🏭
Taurian is manufacturer of crushers, screeners, etc used mainly in mining, infra, etc
___________________________________
Amazing product and top notch quality (ground checks)
𝐉𝐮𝐬𝐭 𝟑-𝟒 𝐨𝐭𝐡𝐞𝐫 𝐝𝐨𝐦𝐞𝐬𝐭𝐢𝐜 𝐩𝐥𝐚𝐲𝐞𝐫𝐬 & 𝟑 𝐌𝐍𝐂𝐬 𝐢𝐧 𝐨𝐫𝐠𝐚𝐧𝐢𝐬𝐞𝐝 𝐩𝐥𝐚𝐲 (This product requires higher tech / engineering)
Taurian is the only these few players having 𝐜𝐚𝐩𝐚𝐛𝐢𝐥𝐢𝐭𝐢𝐞𝐬 𝐭𝐨 𝐝𝐨 𝐡𝐢𝐠𝐡 𝐩𝐨𝐰𝐞𝐫 𝐜𝐫𝐮𝐬𝐡𝐞𝐫𝐬/𝐬𝐜𝐫𝐞𝐞𝐧𝐞𝐫𝐬 (Upto 800TPH)✅
✅𝐓𝐨𝐩 𝐜𝐥𝐢𝐞𝐧𝐭𝐞𝐥𝐞 - 𝐋&𝐓, 𝐇𝐂𝐂, 𝐓𝐚𝐭𝐚, 𝐆𝐥𝐨𝐛𝐚𝐥 𝐀𝐭𝐨𝐦𝐢𝐜
110,000 sqft state of the art manufacturing facility (unlike majority SMEs having jugadu facilities 2-3 galas of 10,000 sqft each)
𝐂𝐮𝐫𝐫𝐞𝐧𝐭 𝐮𝐭𝐢𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 𝐢𝐬 𝐣𝐮𝐬𝐭 𝟐𝟎% 𝐟𝐫𝐨𝐦 𝐞𝐱𝐢𝐬𝐭𝐢𝐧𝐠 𝐩𝐥𝐚𝐧𝐭 𝐩𝐫𝐨𝐯𝐢𝐝𝐞𝐬 𝐛𝐢𝐠 𝐡𝐞𝐚𝐝𝐫𝐨𝐨𝐦✅
___________________________________
Dynamic 2nd gen promoter - he will easily grow the business 70-80% CAGR
FY25: Rev 74Cr ; PAT 10Cr
𝐅𝐘𝟐𝟔𝐄: 𝐑𝐞𝐯 𝟏𝟑𝟓𝐂𝐫 + ; 𝐏𝐀𝐓 𝟏𝟗-𝟐𝟏𝐂𝐫✅
FY27E: Rev 240Cr ; PAT 35Cr
Capital goods companies with this kind of product line in my view 𝐝𝐞𝐬𝐞𝐫𝐯𝐞𝐬 𝟐𝟓-𝟑𝟎 𝐏𝐄 (𝐜𝐮𝐫𝐫𝐞𝐧𝐭𝐥𝐲 𝐚𝐭 𝟏𝟎.𝟓𝐏𝐄 𝐅𝐘𝟐𝟔𝐄 ; 𝟔.𝟓𝐏𝐄 𝐅𝐘𝟐𝟕𝐄) ✅
_____________________________________
Other growth areas:
M-Sand machines is a big growth area - with govt moving towards banning of river sand mining, this will gain big traction. Taurian has entire range
Superior product quality has opened up export markets - Co expects 40% of revenue from exports next year (was negligible in FY25)
Waste processing in another sector which company could explore
Note: NOT a buy / sell reco | DYODD


𝐀𝐟𝐜𝐨𝐦 𝐇𝐨𝐥𝐝𝐢𝐧𝐠𝐬 (Update)
Finally, the 3rd aircraft has arrived !!
✅Will give big boost to Q4
Ground checks suggest even Q3 should be all time high
So on track for:
𝐅𝐘𝟐𝟔𝐄: 𝐑𝐞𝐯 𝟔𝟎𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟏𝟑𝟓𝐂𝐫
_______________________________
Further with 4th aircraft expected soon:
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯 𝟏𝟏𝟎𝟎𝐂𝐫 + ; 𝐏𝐀𝐓 𝟐𝟑𝟎𝐂𝐫+
✅Trading at just 16.5 PE (FY26E) ; 10PE (FY27E)
Further with preferential funds received (despite bad market & all the negativity around the stock), can expect 𝐚𝐜𝐜𝐞𝐥𝐞𝐫𝐚𝐭𝐞𝐝 𝐩𝐥𝐚𝐧𝐬 𝐟𝐨𝐫 𝐭𝐡𝐞 𝟐 𝐰𝐢𝐝𝐞 𝐛𝐨𝐝𝐲 𝐚𝐢𝐫𝐜𝐫𝐚𝐟𝐭𝐬 (𝟕𝟕𝟕) as well which will be a massive massive trigger
Not a buy / sell reco | DYODD

𝐀𝐟𝐜𝐨𝐦 𝐇𝐨𝐥𝐝𝐢𝐧𝐠𝐬 (Update)
Good numbers
H1FY26 performance:
Rev: 240Cr vs 150Cr HoH vs 89Cr YoY
𝐏𝐀𝐓: 𝟓𝟓𝐂𝐫🔥 𝐯𝐬 𝟑𝟎𝐂𝐫 𝐇𝐨𝐇 𝐯𝐬 𝟏𝟗𝐂𝐫 𝐘𝐨𝐘
Q1 performance had been out of the park and co has maintained that performance in Q2
____________________________________
Now key is to track 3rd and 4th aircraft. Expecting these to come in soon
1️⃣Existing capacity: 44 tonnes
𝐓𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟏𝟗 𝐏𝐄 (𝐚𝐧𝐧𝐮𝐚𝐥𝐢𝐬𝐞𝐝 𝐇𝟏) - 𝐭𝐡𝐢𝐬 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐝𝐞𝐬𝐞𝐫𝐯𝐞𝐬 𝟑𝟎-𝟑𝟓𝐏𝐄
BUT, MAINLY, HUGE EXPANSION…
2️⃣By Q4FY26: Capacity 110 tonnes
And with fund raise plans in place
3️⃣By Q2FY27: Capacity 220 tonnes
4️⃣𝐁𝐲 𝐐𝟒𝐅𝐘𝟐𝟕: 𝐂𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝟑𝟑𝟎 𝐭𝐨𝐧𝐧𝐞𝐬
So with 𝟕-𝟖𝐱 𝐞𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧✅ 𝐢𝐧 𝐩𝐢𝐩𝐞𝐥𝐢𝐧𝐞, 𝐁𝐈𝐆 𝐁𝐈𝐆 𝐧𝐨𝐬 𝐩𝐨𝐬𝐬𝐢𝐛𝐥𝐞. Just need patience considering delays due to inherent limitations of this sector
DYODD | Not a buy / sell reco

𝐅𝐫𝐞𝐬𝐡𝐚𝐫𝐚 𝐀𝐠𝐫𝐨 (Update)
𝐒𝐩𝐚𝐢𝐧 𝐚𝐜𝐪𝐮𝐢𝐬𝐢𝐭𝐢𝐨𝐧 - 𝐒𝐚𝐫𝐚𝐬𝐚: 𝐀 𝐁𝐈𝐆 𝐆𝐚𝐦𝐞 𝐂𝐡𝐚𝐧𝐠𝐞𝐫
𝐒𝐭𝐫𝐮𝐜𝐭𝐮𝐫𝐚𝐥 𝐬𝐡𝐢𝐟𝐭 𝐭𝐨 𝐚 𝐁𝟐𝐂 𝐩𝐥𝐚𝐲✅, but more importantly:
Freshara will be one of the very very rare companies with own 𝐛𝐫𝐚𝐧𝐝 + 𝐜𝐨𝐧𝐭𝐫𝐨𝐥 𝐨𝐟 𝐞𝐧𝐭𝐢𝐫𝐞 𝐬𝐮𝐩𝐩𝐥𝐲 𝐜𝐡𝐚𝐢𝐧 - right from sourcing directly from farmers to selling under its own brand in leading retail chains like Walmart
____________________________________
𝐀𝐜𝐪𝐮𝐢𝐬𝐢𝐭𝐢𝐨𝐧 𝐜𝐨𝐬𝐭 𝐣𝐮𝐬𝐭 𝟕𝟓𝐂𝐫 (𝐢𝐧𝐜𝐥 𝟒𝟓𝐂𝐫 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲) 𝐟𝐨𝐫 𝐚 𝐥𝐞𝐚𝐝𝐢𝐧𝐠 𝐛𝐫𝐚𝐧𝐝 𝐰𝐢𝐭𝐡 𝟐𝟎𝟎𝐂𝐫+ 𝐑𝐞𝐯𝐞𝐧𝐮𝐞
Spain is the largest producer of olives globally. This acquisition opens many potential opportunities for Freshara:
1️⃣Entry into retail chains like Walmart (currently Sarasa only selling in Spain) : Getting shelf space in Walmart in the US / UK is not an easy task. But Spanish olives brands have got preference with 3-4 brands already selling there
2️⃣Freshara will start selling its own products (Gherkins, etc) under brand ‘Sarasa’ & easier to push this as well in retail chains
___________________________________
Mgmt Guidance:
FY26E: Rev 325Cr ; PAT 33-35Cr
FY27E: Rev 600Cr (incl 200Cr Spain) ; PAT 60-62Cr
✅𝐓𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟕𝐏𝐄 (𝐅𝐘𝟐𝟕 𝐛𝐚𝐬𝐢𝐬) ; 𝐰𝐢𝐭𝐡 𝟒𝟎% 𝐁𝟐𝐂 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬 !!
___________________________________
More on the turnaround plan for Sarasa and numbers soon 🔜
Not a buy / sell reco | DYODD


𝐅𝐫𝐞𝐬𝐡𝐚𝐫𝐚 𝐀𝐠𝐫𝐨 (Alpha Ideas meet update)
▪️3rd largest Gherkins exporter. 𝐆𝐨𝐚𝐥 𝐭𝐨 𝐛𝐞 𝐭𝐡𝐞 𝐧𝐨. 𝟏 (𝐥𝐚𝐫𝐠𝐞𝐬𝐭) 𝐛𝐲 𝐅𝐘𝟐𝟕/𝐅𝐘𝟐𝟖✅
▪️Gherkins taste matters a lot - it is customised for each geography, customer stickiness also higher so not exactly a commodity play, but more B2B consumer play
▪️Currently exporting to 40 countries, plans to take this to 80 by FY27
▪️𝐖𝐚𝐥𝐦𝐚𝐫𝐭 𝐰𝐡𝐢𝐭𝐞 𝐥𝐚𝐛𝐞𝐥𝐥𝐢𝐧𝐠 𝐭𝐞𝐧𝐝𝐞𝐫 expected next month (Sep’25)✅
▪️New products like Baby corn, jalapeños, etc have lot of potential and to drive growth
_________________________________
Now coming to the numbers (my view)…
FY25: Revenue 250Cr ; PAT 29Cr
New unit which started in Jan’25, alone has revenue potential of 250-300 Crore✅✅
Currently, running at 45-50% utilisation, with plans to ramp up to 90% by Mar’26
𝐒𝐨, 𝐅𝐘𝟐𝟔𝐄: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝟑𝟖𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟒𝟖-𝟓𝟎𝐂𝐫✅
Further, few inorganic opportunities being evaluated and further capex being planned
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝟓𝟎𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟔𝟐-𝟔𝟒𝐂𝐫
View on Promoter Mr Junaid: Purely focused on execution with a well defined business plan
NOTE: Not a buy/sell reco | DYODD


𝐃𝐒𝐌 𝐅𝐫𝐞𝐬𝐡 𝐅𝐨𝐨𝐝𝐬 (𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡) - Concall Update
Revenue ambition of 1000 Crore🔥
Key takeaways:
F͟i͟n͟a͟n͟c͟i͟a͟l͟s͟:͟
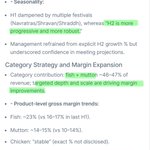
1. 𝐇𝟐 𝐭𝐨 𝐛𝐞 𝐦𝐮𝐜𝐡 𝐬𝐭𝐫𝐨𝐧𝐠𝐞𝐫 𝐭𝐡𝐚𝐧 𝐇𝟏 (as H1 sees festivals like Navratra, Shraddh, etc)
2. Margin improvement due to increased efficiency in Fish & Mutton categories.
✅𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐬𝐞𝐞𝐬 𝐟𝐮𝐫𝐭𝐡𝐞𝐫 𝐬𝐜𝐨𝐩𝐞 𝐟𝐨𝐫 𝐢𝐦𝐩𝐫𝐨𝐯𝐞𝐦𝐞𝐧𝐭 𝐢𝐧 𝐦𝐚𝐫𝐠𝐢𝐧𝐬
A͟d͟d͟i͟t͟i͟o͟n͟a͟l͟ ͟G͟r͟o͟w͟t͟h͟ ͟L͟e͟v͟e͟r͟s͟:͟
3. Big inorganic plans:
Co at advanced stages for 2 acquisitions in the 𝐒𝐧𝐚𝐜𝐤𝐢𝐧𝐠 𝐚𝐧𝐝 𝐑𝐓𝐂 𝐬𝐩𝐚𝐜𝐞 ✅. These are 𝐛𝐢𝐠 𝐬𝐢𝐳𝐞𝐝 𝐨𝐧𝐞𝐬.✅
✅Co has a brilliant track record of acquiring struggling assets and turning around within 6-12 months (𝐬𝐞𝐞 𝟑𝐫𝐝 𝐬𝐬 🔽). So anything on these lines will be huge boost for FY27
4. Local meat shop tie ups:
Pilot project of 15-20 stores done in Bangalore.
✅𝐋𝐨𝐨𝐤𝐢𝐧𝐠 𝐭𝐨 𝐫𝐚𝐦𝐩 𝐭𝐡𝐢𝐬 𝐮𝐩 𝐛𝐢𝐠 𝐭𝐢𝐦𝐞 - not baked this in projections
5. Public private partnerships:
In talks with certain State Govts for a PPP to improve local meat ecosystem
✅Even if Co can 𝐜𝐫𝐚𝐜𝐤 𝟏 𝐒𝐭𝐚𝐭𝐞, 𝐰𝐢𝐥𝐥 𝐛𝐞 𝐡𝐮𝐠𝐞
Previous FY27 projections are excluding Local meat shops , PPP and inorganic. If that kicks in, 𝐅𝐘𝟐𝟕 𝐜𝐚𝐧 𝐛𝐞 𝐇𝐔𝐆𝐄! ❇️
_____________________________
FY26E: Rev 220Cr ; PAT 17Cr
FY27E (excl above levers): Rev 320Cr ; PAT 24-25Cr
FY27E (incl above levers): Rev 400Cr+; PAT 30Cr+✅🔥
𝐂𝐨𝐧𝐬𝐮𝐦𝐞𝐫 𝐛𝐫𝐚𝐧𝐝 𝐠𝐫𝐨𝐰𝐢𝐧𝐠 𝐚𝐭 𝟕𝟎-𝟖𝟎% 𝐚𝐯𝐚𝐢𝐥𝐚𝐛𝐥𝐞 𝐚𝐭 𝟏𝟑𝐏𝐄 𝐅𝐘𝟐𝟕𝐄
vs other brands at 30-35 forward PE with 30-40% CAGR
No buy / sell reco | DYODD


𝐃𝐒𝐌 𝐅𝐫𝐞𝐬𝐡 𝐅𝐨𝐨𝐝𝐬 (𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡) - Update
Superb H1 nos
H1FY26 performance:
Rev 96Cr vs 66Cr YoY
PAT 7Cr🔥 vs 2.5Cr YoY
𝐅𝐮𝐫𝐭𝐡𝐞𝐫, 𝐇𝟐 𝐰𝐢𝐥𝐥 𝐛𝐞 𝐞𝐯𝐞𝐧 𝐬𝐭𝐫𝐨𝐧𝐠𝐞𝐫 𝐬𝐢𝐧𝐜𝐞 𝐌𝐞𝐚𝐭 𝐜𝐨𝐧𝐬𝐮𝐦𝐩𝐭𝐢𝐨𝐧 𝐢𝐬 𝐡𝐢𝐠𝐡𝐞𝐬𝐭 𝐢𝐧 𝐰𝐢𝐧𝐭𝐞𝐫 (Q3 & Q4)
▶️ FY26E: Rev 220Cr ; PAT 17Cr
(vs FY25 Rev 131Cr ; PAT 9Cr)
IPO funds full impact in FY27
▶️ FY27E: Rev 320Cr ; PAT 24-25Cr✅
_________________________________
Profitable D2C with high growth available at very reasonable valuations:
FY26 basis: 1.8x revenue ; 22x PE
FY27 basis: 1.3x revenue ; 16x PE
v/s
Exorbitant valuations of other platform / D2C businesses
DYODD | Not a buy / sell reco

Phantom Digital (Business Update)
⏩️𝐎𝐫𝐝𝐞𝐫 𝐛𝐨𝐨𝐤 𝟐𝟎𝟎𝐂𝐫🔥 𝐚𝐬 𝐨𝐟 𝐎𝐜𝐭’𝟐𝟓 𝐯𝐬 𝟕𝟐𝐂𝐫 𝐚𝐬 𝐨𝐟 𝐉𝐮𝐧’𝟐𝟓
𝐇𝟏 𝐧𝐨𝐬 𝐚𝐥𝐫𝐞𝐚𝐝𝐲 𝐬𝐮𝐩𝐞𝐫 𝐛𝐮𝐦𝐩𝐞𝐫. Huge order book gives 𝐯𝐢𝐬𝐢𝐛𝐢𝐥𝐢𝐭𝐲 𝐟𝐨𝐫 𝐠𝐫𝐨𝐰𝐭𝐡 𝐨𝐧 𝐭𝐡𝐞𝐬𝐞 𝐧𝐨𝐬 𝐚𝐬 𝐰𝐞𝐥𝐥
Tippet consolidation from Jul’25 and Milk consolidation from Oct’25
✅Collections of 14Crore (20% of Sep’25 Receivables) in Oct-Nov
Trading at just 9PE FY26E ; 6-7PE FY27E
Not a buy / sell reco | DYODD


𝐏𝐡𝐚𝐧𝐭𝐨𝐦 𝐃𝐢𝐠𝐢𝐭𝐚𝐥 (H1FY26 Update)
Absolute BLOCKBUSTER set 🔥🔥
Beyond everyone’s expectations. 𝐍𝐨𝐰 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟗𝐏𝐄 𝐅𝐘𝟐𝟔𝐄 𝐛𝐚𝐬𝐢𝐬
In my view, 𝐃𝐞𝐬𝐞𝐫𝐯𝐞𝐬 𝐚𝐭 𝐥𝐞𝐚𝐬𝐭 𝟐𝟓𝐏𝐄:
1. Creative capabilities + super portfolio of brands (Tippett, Milk, etc)
2. Serving Marquee customers directly: Netflix, Marvel, Warner Bros
3. High margin business: 20% PAT
4. Growth outlook of 70%+ (current year 100-120%)
____________________________________
H1FY26 performance:
Revenue: 89Cr vs 35Cr YoY vs 64Cr HoH
(vs management guidance 65Cr)
𝐏𝐀𝐓: 𝟐𝟏𝐂𝐫 🔥 vs 8Cr YoY vs 12Cr HoH
(vs management guidance 13Cr)
𝐀𝐛𝐨𝐯𝐞 𝐩𝐞𝐫𝐟𝐨𝐫𝐦𝐚𝐧𝐜𝐞 𝐰𝐢𝐭𝐡𝐨𝐮𝐭 𝐢𝐦𝐩𝐚𝐜𝐭 𝐨𝐟 𝐌𝐢𝐥𝐤 𝐚𝐧𝐝 𝐨𝐧𝐥𝐲 𝟏 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐢𝐦𝐩𝐚𝐜𝐭 𝐨𝐟 𝐓𝐢𝐩𝐩𝐞𝐭𝐭.
𝐈𝐧 𝐇𝟐 𝐰𝐞 𝐰𝐢𝐥𝐥 𝐬𝐞𝐞 𝐟𝐮𝐥𝐥 𝐓𝐢𝐩𝐩𝐞𝐭𝐭 𝐧𝐨𝐬 𝐚𝐧𝐝 𝐌𝐢𝐥𝐤 𝐧𝐨𝐬. 𝐒𝐨 𝐢𝐦𝐚𝐠𝐢𝐧𝐞 𝐭𝐡𝐞 𝐩𝐨𝐭𝐞𝐧𝐭𝐢𝐚𝐥
___________________________________
Market had been discounting / punishing phantom due to not meeting guidances in FY25 - but did not care to understand that entire industry was suffering then due to sudden external factors
✅Now with this performance exceeding guidance big way + huge valuation mismatch, potential for huge re-rating
___________________________________
Industry checks:
1. Big turnaround in VFX is already underway
2. Strong order inflow and very good collections recently
Phantom is best poised to benefit with its creative capabilities and especially with recent acquisitions of top studios in US and Europe: Tippett and Milk
𝐒𝐭𝐚𝐫 𝐈𝐦𝐚𝐠𝐢𝐧𝐠 (𝐔𝐩𝐝𝐚𝐭𝐞)
Very strong H1 performance
H1FY26: Rev 45Cr ; PAT 10Cr✅
𝐎𝐧 𝐭𝐫𝐚𝐜𝐤 𝐟𝐨𝐫 𝐅𝐘𝟐𝟔𝐄: 𝐑𝐞𝐯 𝟏𝟎𝟎-𝟏𝟏𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟐𝟐-𝟐𝟑𝐂𝐫
▶️Recent B2C and B2B expansion to see impact in H2
______________________________________
Further full impact of IPO funds in FY27
𝐅𝐘𝟐𝟕𝐄: 𝐑𝐞𝐯 𝟏𝟒𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟐𝟖𝐂𝐫
𝐁𝐲 𝐟𝐚𝐫 𝐭𝐡𝐞 𝐜𝐡𝐞𝐚𝐩𝐞𝐬𝐭 𝐝𝐢𝐚𝐠𝐧𝐨𝐬𝐭𝐢𝐜 𝐬𝐭𝐨𝐜𝐤. Just 11PE FY26E ; 8PE FY27E
Poised for re-rating
DYODD | No buy / sell reco

𝐒𝐭𝐚𝐫 𝐈𝐦𝐚𝐠𝐢𝐧𝐠 (𝐔𝐩𝐝𝐚𝐭𝐞)
✅𝐁𝟐𝐁 𝐭𝐢𝐞 𝐮𝐩 𝐟𝐨𝐫 𝟒 𝐧𝐞𝐰 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 to be added over next 6 months
⏩️Also since these will be within the hospital, 𝐢𝐦𝐦𝐞𝐝𝐢𝐚𝐭𝐞 𝐟𝐨𝐨𝐭𝐟𝐚𝐥𝐥. 𝐒𝐨 𝐡𝐢𝐠𝐡 𝐮𝐭𝐢𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 / 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐟𝐫𝐨𝐦 𝐝𝐚𝐲 𝟏 𝐢𝐭𝐬𝐞𝐥𝐟
Star Imaging currently has 4 B2C centres generating 45Crore revenue.
𝐓𝐡𝐞𝐬𝐞 𝟒 𝐧𝐞𝐰 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 𝐨𝐧 𝐁𝟐𝐁 𝐜𝐚𝐧 𝐚𝐥𝐬𝐨 𝐥𝐞𝐚𝐝 𝐭𝐨 𝟏𝟓 𝐂𝐫𝐨𝐫𝐞 𝐚𝐝𝐝𝐢𝐭𝐢𝐨𝐧𝐚𝐥 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (assuming these might be smaller ones)
After yesterday’s update on B2C centre expansion, now this. Seems like 𝐜𝐨𝐦𝐩𝐚𝐧𝐲 𝐢𝐬 𝐠𝐨𝐢𝐧𝐠 𝐛𝐢𝐠 𝐨𝐧 𝐁𝟐𝐂 𝐚𝐧𝐝 𝐁𝟐𝐁 𝐰𝐡𝐢𝐜𝐡 𝐰𝐢𝐥𝐥 𝐥𝐞𝐚𝐝 𝐭𝐨 𝐛𝐢𝐠 𝐫𝐞-𝐫𝐚𝐭𝐢𝐧𝐠✅✅
Not a buy / sell reco | DYODD

𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (𝐜𝐨𝐧𝐜𝐚𝐥𝐥 𝐮𝐩𝐝𝐚𝐭𝐞)
What a superb concall. This business will definitely 𝐬𝐭𝐚𝐫𝐭 𝐚𝐭𝐭𝐫𝐚𝐜𝐭𝐢𝐧𝐠 𝐢𝐧𝐬𝐭𝐢𝐭𝐮𝐭𝐢𝐨𝐧𝐚𝐥 𝐢𝐧𝐭𝐞𝐫𝐞𝐬𝐭 at the appropriate time
A few takeaways:
1️⃣Capacity expanded by 30% in H1FY26.
✅𝐁𝐲 𝐉𝐮𝐧’𝟐𝟔, 𝐰𝐢𝐥𝐥 𝐞𝐱𝐩𝐚𝐧𝐝 𝐛𝐲 𝐚𝐧𝐨𝐭𝐡𝐞𝐫 𝟏𝟓𝟎% 𝐢.𝐞. 𝟐.𝟓𝐱 𝐨𝐟 𝐞𝐱𝐢𝐬𝐭𝐢𝐧𝐠 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲
________________________________
2️⃣Largest client - Carbamide Forte has grown 4x in last 18 months. Influx is best positioned to serve them with its certifications etc
✅ 𝐃𝐞𝐝𝐢𝐜𝐚𝐭𝐞𝐝 𝐮𝐧𝐢𝐭 / 𝐥𝐢𝐧𝐞𝐬 𝐟𝐨𝐫 𝐭𝐡𝐞𝐦 𝐢𝐬 𝐨𝐧𝐞 𝐦𝐚𝐬𝐬𝐢𝐯𝐞 𝐩𝐨𝐭𝐞𝐧𝐭𝐢𝐚𝐥 𝐚𝐫𝐞𝐚
𝐓𝐡𝐢𝐬 𝐢𝐬 𝐞𝐱𝐚𝐜𝐭𝐥𝐲 𝐰𝐡𝐚𝐭 𝐇𝐢𝐧𝐝𝐮𝐬𝐭𝐚𝐧 𝐅𝐨𝐨𝐝𝐬 𝐢𝐬 𝐝𝐨𝐢𝐧𝐠 𝐟𝐨𝐫 𝐇𝐔𝐋, 𝐒𝐜𝐡𝐨𝐥𝐥𝐬, 𝐞𝐭𝐜 (see ss 2 and 3)
________________________________
3️⃣Projections:
FY26 guidance Rev 160Cr ; PAT 24Cr
✅𝐂𝐚𝐧 𝐫𝐞𝐚𝐜𝐡 𝐨𝐩𝐭𝐢𝐦𝐮𝐦 𝐮𝐭𝐢𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 (𝟗𝟎%) 𝐛𝐲 𝐅𝐘𝟐𝟖 𝐢.𝐞. 𝟒𝟐𝟎𝐂𝐫 𝐫𝐞𝐯𝐞𝐧𝐮𝐞
__________________________________
See full concall notes here ▶️ xitter.cf/sachprat07/status/1988…
DYODD | Not a buy / sell reco


𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (H1 Update)
Very very strong set
H1FY26: Rev 69Cr ; PAT 10Cr 🔥
(vs guidance of 8.5Cr PAT)
Expanded capacity (out of internal accruals) in August to October will see full impact in H2FY26
𝐅𝐘𝟐𝟔𝐄: 𝟏𝟔𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟐𝟒𝐂𝐫
Also just look at the 𝐛𝐚𝐥𝐚𝐧𝐜𝐞 𝐬𝐡𝐞𝐞𝐭 𝐪𝐮𝐚𝐥𝐢𝐭𝐲 𝐚𝐧𝐝 𝐛𝐫𝐢𝐥𝐥𝐢𝐚𝐧𝐭 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐚𝐥 𝐫𝐚𝐭𝐢𝐨𝐬 , 𝐜𝐨𝐧𝐭𝐢𝐧𝐮𝐨𝐮𝐬𝐥𝐲 𝐢𝐦𝐩𝐫𝐨𝐯𝐢𝐧𝐠 ✅
___________________________________
Further, above is without IPO funds usage
𝐁𝐈𝐆 𝐞𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧 𝐮𝐧𝐝𝐞𝐫𝐰𝐚𝐲
FY27E: Rev 250Cr ; PAT 38Cr
FY28E: Rev 370Cr ; PAT 52Cr+
𝐂𝐡𝐞𝐚𝐩𝐞𝐬𝐭 𝐩𝐥𝐚𝐲 𝐢𝐧 𝐭𝐡𝐞 𝐜𝐨𝐧𝐬𝐮𝐦𝐞𝐫 𝐬𝐞𝐜𝐭𝐨𝐫 𝐭𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟏𝟖 𝐏𝐄 (𝐅𝐘𝟐𝟔𝐄) ; 𝟏𝟏 𝐏𝐄 (𝐅𝐘𝟐𝟕𝐄)
I feel in the future, company will be compared to the likes of Hindustan Foods, which are trading at 50PE+
__________________________
Will post concall update soon
Not a buy / sell reco | DYODD


𝐀𝐟𝐜𝐨𝐦 𝐇𝐨𝐥𝐝𝐢𝐧𝐠𝐬 (Update)
Good numbers
H1FY26 performance:
Rev: 240Cr vs 150Cr HoH vs 89Cr YoY
𝐏𝐀𝐓: 𝟓𝟓𝐂𝐫🔥 𝐯𝐬 𝟑𝟎𝐂𝐫 𝐇𝐨𝐇 𝐯𝐬 𝟏𝟗𝐂𝐫 𝐘𝐨𝐘
Q1 performance had been out of the park and co has maintained that performance in Q2
____________________________________
Now key is to track 3rd and 4th aircraft. Expecting these to come in soon
1️⃣Existing capacity: 44 tonnes
𝐓𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟏𝟗 𝐏𝐄 (𝐚𝐧𝐧𝐮𝐚𝐥𝐢𝐬𝐞𝐝 𝐇𝟏) - 𝐭𝐡𝐢𝐬 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐝𝐞𝐬𝐞𝐫𝐯𝐞𝐬 𝟑𝟎-𝟑𝟓𝐏𝐄
BUT, MAINLY, HUGE EXPANSION…
2️⃣By Q4FY26: Capacity 110 tonnes
And with fund raise plans in place
3️⃣By Q2FY27: Capacity 220 tonnes
4️⃣𝐁𝐲 𝐐𝟒𝐅𝐘𝟐𝟕: 𝐂𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝟑𝟑𝟎 𝐭𝐨𝐧𝐧𝐞𝐬
So with 𝟕-𝟖𝐱 𝐞𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧✅ 𝐢𝐧 𝐩𝐢𝐩𝐞𝐥𝐢𝐧𝐞, 𝐁𝐈𝐆 𝐁𝐈𝐆 𝐧𝐨𝐬 𝐩𝐨𝐬𝐬𝐢𝐛𝐥𝐞. Just need patience considering delays due to inherent limitations of this sector
DYODD | Not a buy / sell reco
𝐀𝐟𝐜𝐨𝐦 𝐇𝐨𝐥𝐝𝐢𝐧𝐠𝐬 (Alpha Ideas Meet update)
Good presentation - I’ll cover just an 𝐮𝐩𝐝𝐚𝐭𝐞 𝐨𝐧 𝐭𝐡𝐞 𝐟𝐥𝐞𝐞𝐭
(have covered all aspects previously so won’t repeat)
_____________________________________
Existing aircraft:
- 2 Boeing 737 at 85% utilisation
- Major destinations Male, Hanoi, Myanmar, Bangkok
New aircraft:
- 𝟑𝐫𝐝 𝟕𝟑𝟕 𝐭𝐨 𝐛𝐞 𝐢𝐧𝐝𝐮𝐜𝐭𝐞𝐝 𝐛𝐲 𝟖-𝟏𝟎𝐭𝐡 𝐒𝐞𝐩𝐭’𝟐𝟓✅ (𝐰𝐢𝐭𝐡𝐢𝐧 𝐧𝐞𝐱𝐭 𝟐-𝟑 𝐰𝐞𝐞𝐤)
- 𝟒𝐭𝐡 𝟕𝟑𝟕 𝐛𝐲 𝐄𝐚𝐫𝐥𝐲 𝐎𝐜𝐭’𝟐𝟓✅
- 5th 737 by Mar’26
Further, 2 Boeing 777 (wide body with 5x capacity vs 737) to be inducted by Dec’26
Faced some delays due to more stringent checks by Regulators after the recent Air India incident
Note: Not a buy / sell reco | DYODD


𝐃𝐒𝐌 𝐅𝐫𝐞𝐬𝐡 𝐅𝐨𝐨𝐝𝐬 (𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡) - Update
Superb H1 nos
H1FY26 performance:
Rev 96Cr vs 66Cr YoY
PAT 7Cr🔥 vs 2.5Cr YoY
𝐅𝐮𝐫𝐭𝐡𝐞𝐫, 𝐇𝟐 𝐰𝐢𝐥𝐥 𝐛𝐞 𝐞𝐯𝐞𝐧 𝐬𝐭𝐫𝐨𝐧𝐠𝐞𝐫 𝐬𝐢𝐧𝐜𝐞 𝐌𝐞𝐚𝐭 𝐜𝐨𝐧𝐬𝐮𝐦𝐩𝐭𝐢𝐨𝐧 𝐢𝐬 𝐡𝐢𝐠𝐡𝐞𝐬𝐭 𝐢𝐧 𝐰𝐢𝐧𝐭𝐞𝐫 (Q3 & Q4)
▶️ FY26E: Rev 220Cr ; PAT 17Cr
(vs FY25 Rev 131Cr ; PAT 9Cr)
IPO funds full impact in FY27
▶️ FY27E: Rev 320Cr ; PAT 24-25Cr✅
_________________________________
Profitable D2C with high growth available at very reasonable valuations:
FY26 basis: 1.8x revenue ; 22x PE
FY27 basis: 1.3x revenue ; 16x PE
v/s
Exorbitant valuations of other platform / D2C businesses
DYODD | Not a buy / sell reco
𝐃𝐒𝐌 𝐅𝐫𝐞𝐬𝐡 𝐅𝐨𝐨𝐝𝐬 (𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡) - Update
✅𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡 𝐡𝐚𝐬 𝐜𝐫𝐚𝐜𝐤𝐞𝐝 𝐭𝐡𝐞 𝐜𝐨𝐝𝐞 𝐟𝐨𝐫 ‘𝐏𝐫𝐨𝐟𝐢𝐭𝐚𝐛𝐥𝐞 𝐆𝐫𝐨𝐰𝐭𝐡’ - Very few new age consumer brands have managed to do this
A view on the business model below🔽
_________________________________
𝐌𝐞𝐚𝐭 𝐦𝐚𝐫𝐤𝐞𝐭 𝐢𝐧 𝐈𝐧𝐝𝐢𝐚 𝐡𝐚𝐬 𝐚 𝐦𝐚𝐣𝐨𝐫 𝐩𝐫𝐨𝐛𝐥𝐞𝐦 - Being 90% unorganised, absence of integrated supply chain and cold chain facilities leads to Poor quality , hygiene
𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡 𝐢𝐬 𝐬𝐨𝐥𝐯𝐢𝐧𝐠 𝐭𝐡𝐢𝐬 𝐯𝐢𝐚 𝐚 𝐟𝐚𝐫𝐦 𝐭𝐨 𝐟𝐨𝐫𝐤 𝐦𝐨𝐝𝐞𝐥 with an integrated supply chain - incl end-to-end cold chain facilties, delivering within 24hrs
__________________________________
Omnichannel strategy:
𝟏. 𝐃𝟐𝐂 (𝟓𝟎% 𝐨𝐟 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬)
- Targeting the mass segment with pricing 10-15% cheaper than licious and competitive (slightly higher) than local meat shops
- Personally liked the app a lot - superb interface / UI , easy tracking, etc
𝟐. 𝐇𝐨𝐫𝐞𝐜𝐚 𝐬𝐮𝐩𝐩𝐥𝐢𝐞𝐬:
- Supplying to select food service chains like Pop Tates, Tibbs, etc
- Supply chain for meat is much more intensive than groceries etc. Hence, ✅𝐙𝐚𝐩𝐩𝐟𝐫𝐞𝐬𝐡 𝐢𝐬 𝐛𝐞𝐬𝐭 𝐩𝐨𝐬𝐢𝐭𝐢𝐨𝐧𝐞𝐝 𝐭𝐨 𝐬𝐮𝐩𝐩𝐥𝐲 𝐭𝐨 𝐥𝐢𝐤𝐞𝐬 𝐨𝐟 𝐇𝐲𝐩𝐞𝐫𝐩𝐮𝐫𝐞 (𝐙𝐨𝐦𝐚𝐭𝐨), Zepto - (already existing customers)
𝟑. 𝐌𝐞𝐚𝐭 𝐬𝐡𝐨𝐩𝐬:
- Unique offline strategy where Co ties up with local meat shops
✅𝐄𝐧𝐚𝐛𝐥𝐞𝐬 𝐟𝐢𝐱𝐞𝐝 𝐯𝐨𝐥𝐮𝐦𝐞 𝐨𝐟𝐟𝐭𝐚𝐤𝐞 + 𝐁𝐫𝐚𝐧𝐝 𝐛𝐮𝐢𝐥𝐝𝐢𝐧𝐠 + 𝐀𝐬𝐬𝐞𝐭 𝐥𝐢𝐠𝐡𝐭 (𝐥𝐨𝐰 𝐜𝐚𝐩𝐞𝐱)
_________________________________
𝐏𝐨𝐢𝐧𝐭 𝟏 + 𝟐 𝐦𝐚𝐤𝐞𝐬 𝐢𝐭 𝐂𝐥𝐞𝐚𝐫 𝐭𝐡𝐚𝐭 𝐭𝐡𝐢𝐬 𝐢𝐬 𝐚 𝐡𝐮𝐠𝐞 𝐩𝐥𝐚𝐲 𝐨𝐧 𝐭𝐡𝐞 𝐛𝐨𝐨𝐦𝐢𝐧𝐠 𝐞-𝐜𝐨𝐦𝐦𝐞𝐫𝐜𝐞 𝐢𝐧𝐝𝐮𝐬𝐭𝐫𝐲 / 𝐝𝐢𝐠𝐢𝐭𝐚𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 𝐭𝐡𝐞𝐦𝐞
Licious struggling since 3 years, with no growth (stuck at 700-800Cr) and burning huge cash (majorly in marketing)
On the other hand, Zappfresh has carved a niche with its pricing & omnichannel strategy without going berserk on marketing spends
_________________________________
Will cover Growth potential soon 🔜
(Valuation covered in tagged tweet)
Note: Not a buy/sell reco | DYODD


𝐒𝐭𝐚𝐫 𝐈𝐦𝐚𝐠𝐢𝐧𝐠 (𝐔𝐩𝐝𝐚𝐭𝐞)
✅𝐁𝟐𝐁 𝐭𝐢𝐞 𝐮𝐩 𝐟𝐨𝐫 𝟒 𝐧𝐞𝐰 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 to be added over next 6 months
⏩️Also since these will be within the hospital, 𝐢𝐦𝐦𝐞𝐝𝐢𝐚𝐭𝐞 𝐟𝐨𝐨𝐭𝐟𝐚𝐥𝐥. 𝐒𝐨 𝐡𝐢𝐠𝐡 𝐮𝐭𝐢𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 / 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐟𝐫𝐨𝐦 𝐝𝐚𝐲 𝟏 𝐢𝐭𝐬𝐞𝐥𝐟
Star Imaging currently has 4 B2C centres generating 45Crore revenue.
𝐓𝐡𝐞𝐬𝐞 𝟒 𝐧𝐞𝐰 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 𝐨𝐧 𝐁𝟐𝐁 𝐜𝐚𝐧 𝐚𝐥𝐬𝐨 𝐥𝐞𝐚𝐝 𝐭𝐨 𝟏𝟓 𝐂𝐫𝐨𝐫𝐞 𝐚𝐝𝐝𝐢𝐭𝐢𝐨𝐧𝐚𝐥 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (assuming these might be smaller ones)
After yesterday’s update on B2C centre expansion, now this. Seems like 𝐜𝐨𝐦𝐩𝐚𝐧𝐲 𝐢𝐬 𝐠𝐨𝐢𝐧𝐠 𝐛𝐢𝐠 𝐨𝐧 𝐁𝟐𝐂 𝐚𝐧𝐝 𝐁𝟐𝐁 𝐰𝐡𝐢𝐜𝐡 𝐰𝐢𝐥𝐥 𝐥𝐞𝐚𝐝 𝐭𝐨 𝐛𝐢𝐠 𝐫𝐞-𝐫𝐚𝐭𝐢𝐧𝐠✅✅
Not a buy / sell reco | DYODD
𝐒𝐭𝐚𝐫 𝐈𝐦𝐚𝐠𝐢𝐧𝐠 (𝐔𝐩𝐝𝐚𝐭𝐞)
I have added more. Now part of high conviction portfolio
Key updates (see ss):
1️⃣𝐑𝐞-𝐞𝐦𝐩𝐚𝐧𝐞𝐥𝐥𝐞𝐝 𝐰𝐢𝐭𝐡 𝐂𝐆𝐇𝐒 𝐬𝐜𝐡𝐞𝐦𝐞
▪️With 4 B2C centres in UP, considering the micro market population in these areas, there is easy potential to add revenue of 12Cr+ from CGHS linked footfall itself
▪️HoS company was previously doing 20Cr+ revenue from CGHS scheme
2️⃣𝐄𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧 𝐨𝐟 𝐢𝐭𝐬 𝐦𝐚𝐢𝐧 𝐁𝟐𝐂 𝐜𝐞𝐧𝐭𝐫𝐞 𝐚𝐭 𝐕𝐢𝐤𝐚𝐬 𝐏𝐮𝐫𝐢
▪️Added 1 CT scan and 3 MRI machines - this should roughly mean additional revenue potential of 3-4Crore p.a.
▪️Further, radiology margins are much higher + operating leverage as these machines are in existing space
▶️𝐒𝐨 𝐚𝐥𝐦𝐨𝐬𝐭 𝟐𝟎% 𝐨𝐫𝐠𝐚𝐧𝐢𝐜 𝐠𝐫𝐨𝐰𝐭𝐡 𝐚𝐝𝐝𝐞𝐝 𝐟𝐫𝐨𝐦 𝐚𝐛𝐨𝐯𝐞 𝟐.
⏩️𝐆𝐫𝐨𝐰𝐭𝐡 𝐟𝐫𝐨𝐦 𝐧𝐞𝐰 𝐜𝐞𝐧𝐭𝐫𝐞𝐬 𝐨𝐮𝐭 𝐨𝐟 𝐈𝐏𝐎 𝐟𝐮𝐧𝐝𝐬 𝐰𝐢𝐥𝐥 𝐛𝐞 𝐚𝐝𝐝𝐢𝐭𝐢𝐨𝐧𝐚𝐥
_______________________________________
✅Further, industry checks suggest UP 𝙂𝙤𝙫𝙩 𝙥𝙖𝙮𝙢𝙚𝙣𝙩 𝙙𝙚𝙡𝙖𝙮𝙨 𝙝𝙖𝙫𝙚 𝙗𝙚𝙚𝙣 𝙧𝙚𝙨𝙤𝙡𝙫𝙚𝙙 𝙖𝙣𝙙 𝙢𝙤𝙨𝙩 𝙘𝙤𝙢𝙥𝙖𝙣𝙞𝙚𝙨 𝙝𝙖𝙫𝙚 𝙨𝙩𝙖𝙧𝙩𝙚𝙙 𝙧𝙚𝙘𝙚𝙞𝙫𝙞𝙣𝙜 𝙩𝙝𝙚𝙞𝙧 𝙙𝙪𝙚𝙨
FY26E: Rev 110Cr ; PAT 22Cr
FY27E: Rev 140Cr ; PAT 28Cr
𝐒𝐭𝐚𝐫 𝐭𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟏𝟏𝐏𝐄 𝐅𝐘𝟐𝟔𝐄
vs Chandan Healthcare at 23PE
vs other main board peers at 30-35PE
𝘽𝙮 𝙛𝙖𝙧 𝙩𝙝𝙚 𝙘𝙝𝙚𝙖𝙥𝙚𝙨𝙩 𝙙𝙞𝙖𝙜𝙣𝙤𝙨𝙩𝙞𝙘 𝙨𝙝𝙖𝙧𝙚. With CGHS re-empanelment and if it’s true that receivables issue is resolved, 𝐁𝐈𝐆 𝐁𝐈𝐆 𝐫𝐞-𝐫𝐚𝐭𝐢𝐧𝐠 𝐜𝐚𝐧𝐝𝐢𝐝𝐚𝐭𝐞
For more details, my previous tweet▶️ xitter.cf/wealthsolitaire/status…
Not a buy / sell reco | DYODD

𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (H1 Update)
Very very strong set
H1FY26: Rev 69Cr ; PAT 10Cr 🔥
(vs guidance of 8.5Cr PAT)
Expanded capacity (out of internal accruals) in August to October will see full impact in H2FY26
𝐅𝐘𝟐𝟔𝐄: 𝟏𝟔𝟎𝐂𝐫 ; 𝐏𝐀𝐓 𝟐𝟒𝐂𝐫
Also just look at the 𝐛𝐚𝐥𝐚𝐧𝐜𝐞 𝐬𝐡𝐞𝐞𝐭 𝐪𝐮𝐚𝐥𝐢𝐭𝐲 𝐚𝐧𝐝 𝐛𝐫𝐢𝐥𝐥𝐢𝐚𝐧𝐭 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐚𝐥 𝐫𝐚𝐭𝐢𝐨𝐬 , 𝐜𝐨𝐧𝐭𝐢𝐧𝐮𝐨𝐮𝐬𝐥𝐲 𝐢𝐦𝐩𝐫𝐨𝐯𝐢𝐧𝐠 ✅
___________________________________
Further, above is without IPO funds usage
𝐁𝐈𝐆 𝐞𝐱𝐩𝐚𝐧𝐬𝐢𝐨𝐧 𝐮𝐧𝐝𝐞𝐫𝐰𝐚𝐲
FY27E: Rev 250Cr ; PAT 38Cr
FY28E: Rev 370Cr ; PAT 52Cr+
𝐂𝐡𝐞𝐚𝐩𝐞𝐬𝐭 𝐩𝐥𝐚𝐲 𝐢𝐧 𝐭𝐡𝐞 𝐜𝐨𝐧𝐬𝐮𝐦𝐞𝐫 𝐬𝐞𝐜𝐭𝐨𝐫 𝐭𝐫𝐚𝐝𝐢𝐧𝐠 𝐚𝐭 𝐣𝐮𝐬𝐭 𝟏𝟖 𝐏𝐄 (𝐅𝐘𝟐𝟔𝐄) ; 𝟏𝟏 𝐏𝐄 (𝐅𝐘𝟐𝟕𝐄)
I feel in the future, company will be compared to the likes of Hindustan Foods, which are trading at 50PE+
__________________________
Will post concall update soon
Not a buy / sell reco | DYODD
𝐈𝐧𝐟𝐥𝐮𝐱 𝐇𝐞𝐚𝐥𝐭𝐡𝐭𝐞𝐜𝐡 (Update)
𝐂𝐚𝐩𝐬𝐮𝐥𝐞𝐬 𝐦𝐚𝐧𝐮𝐟𝐚𝐜𝐭𝐮𝐫𝐢𝐧𝐠 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲 𝐭𝐨 𝐢𝐧𝐜𝐫𝐞𝐚𝐬𝐞 𝟔𝐱✅
From my limited understanding of the economics:
▪️23,000/hr capsule line might yield revenue of INR 4.5-5 Crore
▪️The new 122,000/hr capsule line should yield 𝐚𝐝𝐝𝐢𝐭𝐢𝐨𝐧𝐚𝐥 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐨𝐟 𝐈𝐍𝐑 𝟐𝟎-𝟐𝟐 𝐂𝐫𝐨𝐫𝐞 𝐚𝐭 𝐨𝐩𝐭𝐢𝐦𝐚𝐥 𝐮𝐭𝐢𝐥𝐢𝐬𝐚𝐭𝐢𝐨𝐧 ✅✅
(So this new line added 𝐨𝐮𝐭 𝐨𝐟 𝐢𝐧𝐭𝐞𝐫𝐧𝐚𝐥 𝐚𝐜𝐜𝐫𝐮𝐚𝐥𝐬 𝐰𝐢𝐥𝐥 𝐥𝐞𝐚𝐝 𝐭𝐨 𝐚𝐧𝐨𝐭𝐡𝐞𝐫 𝟏𝟎-𝟏𝟓% 𝐢𝐧𝐜𝐫𝐞𝐚𝐬𝐞 𝐢𝐧 𝐜𝐚𝐩𝐚𝐜𝐢𝐭𝐲)
