

All value. No advice | Stock Newsletter https://xitter.cf/t.co/9pEi00XIOe | all write-ups https://xitter.cf/t.co/x5vF9ws8qv | HoldCo https://xitter.cf/t.co/SMAxPD6QVx
Joined July 2014
- Tweets10.8K
- Following924
- Followers12.7K
- Likes12.1K





Another $GDOT deal delay + share price beatdown


For the ambulance chasers, someone getting carted out of $GDOT. Deal isn't dead yet and ample upside to close. Downside case really isn't that bad. Company performance stablised at ~1.50/share in adjusted EPS plus ~1.10/share in AOCI accretion.
1
6
1,418


Another huge downward revision in guidance at $ROCK
This one on the heels of a major levered acquisition

7
1,696

Ugly chart at $APTV
Maybe one of my favorite setups right now despite "tough industry" dynamics...
Lapping one-time VGNT spin costs so FCF should jump to $1B+ next year (on $8B market cap = 12.5% FCF yield) and committed to buyback stock with 100% of FCF through 2027
Assuming no operational/industry improvement, it's not hard to get $7-8 EPS by 2028 (vs. $5.70 in '26)
As a bonus, this management team has done 2 spins in 10 years and wouldn't be surprised if they spin the (better) engineered components business

What an interesting question... is there a repeatable "tough industry" playbook which creates value over time?
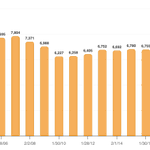
$DDS is a share cannibal with an ugly looking revenue picture (no growth from 1998-2026 / declining)


Dillard's $DDS is an interesting case study on shareholder value creation in the face of enormous industry headwinds.
My question - is there a repeatable "tough industry" playbook here, or were there one-off factors that allowed it to occur?
6
2,033
Seeing a handful of companies absolutely slash guidance recently...
$GIL moving from $4.65-4.75 EPS to $3.70-3.80 with only 1 quarter to go in the year is a pretty sharp turn in outlook...


Don’t see this often (ever?)

From $MNRO 10-Q (book value is over $18):
"during the second quarter of 2027, we experienced a decline in our market capitalization as a result of a decrease in our stock price. Our stock price has a history of volatility, however, given the decrease was sustained throughout the quarter, we viewed this event as a triggering event and performed a quantitative analysis of the fair value of the Company’s single reporting unit as of September 26, 2026 which resulted in an estimated fair value that exceeded its carrying value, including goodwill."


PSA: actively looking for a small, public “Berkshire-like” company with cash or assets :)
I already own a handful of high quality private companies that should compound for years to come, would love to find our “Berkshire” to bring them public
Hit me up if you find anything

In 1958, a company called Sanborn Map traded at $45 a share.
Its investment portfolio alone was worth $65 a share.
So you could buy $65 of stocks and bonds for $45 and get a map business thrown in for free.
A 28-year-old Warren Buffett put 35% of his partnership into it, joined the board and pushed them to unlock the portfolio.
Same playbook works today.
You just need to find those stocks.
$TFC CEO with another sizable insider buy…
New CEO, first bout of insider buying in years, discount to bank peers, etc.
Seems interesting…

3
2
1,949
Great arguments, and agreed the fundamental trends are downright bad
The stock is basically an “option” absent a legit plan to turn around performance
Tho should be fairly uncorrelated outcome to overall market and incentives for a sale are there
I own small amount of MNRO common and some call spreads (maybe 75bps total exposure w/ 6:1 payoff at $20 sale price)
Wouldn’t recommend making this a large/core holding, but still a place for this type of bet in the portfolio… just my 2c

I have no horse in the race, but I don't get why $MNRO bulls are so surprised by the market's reaction to a quarter as shitty as this one, especially after Monro brought in a “turnaround specialist” and closed a bunch of underperforming stores.
By now, I don't think anyone disputes that the company is in play, with Icahn and Gabelli pushing for a sale. That said, I'd guess Mavis is still digesting the Pep Boys acquisition, and there aren't all that many buyers willing and able to pay up for a deal like this.
With interest expenses set to rise further in 2027, net debt rising, and operating performance this poor, it seems potential buyers can afford to wait a lot longer than Monro can. And that's hardly the position you want to be negotiating from.
Lastly, correct me if I'm wrong, but I don't buy the hard-asset downside protection argument either. Sure, they own some of their store real estate, but its value doesn't come close to covering what the market is valuing the company at today.
I think there's a decent chance a transaction happens, which is why I'm following the situation. But until there's some sign of an operational turnaround, the bet seems pretty binary to me.
So I wanted to see if there's something I'm overlooking, or if you're simply more willing than I am to take the risk of "no deal."
2
6
1,918


