

Passionate about investing and markets. I invest in quality and growth, at a reasonable price. Background in Banking & Operations. DYOR
Joined February 2021
- Tweets1.6K
- Following1.2K
- Followers3.2K
- Likes15.9K


Pinned Tweet
I’m sharing my first investment article on the Finnish forum Sijoitustieto - covering $LMND.
Happy to hear your views and feedback - more articles to come in the future.
Summary:
I see $LMND as a high-risk, high-beta investment case, with its story centered on the company’s ability to disrupt the traditional insurance market over the coming years. The numbers show early signs that the fundamentals are moving in the right direction. During H2, I’ll be closely watching the development of IFP (in-force premium). As the business scales through growth investments, I believe the company can reach positive EBITDA next year.
sijoitustieto.fi/sijoitusart…


Sijoitustietoon saatiin uusi erinomainen kirjoittaja @ValueByMarkus . Ensimmäisessä artikkelissaan hän analysoi vakuutusalan disruptoijaa, Lemonadea.
”…ensimmäinen puhtaasti diginatiivi vakuutusyhtiö, joka lupasi mullistaa alan mm. tekoälyn avulla.”
sijoitustieto.fi/sijoitusart…

$IREN
I struggle to justify spending $20–50M per year on a Real Madrid partnership in the AI neocloud business.
When your business requires billions in capex, external financing and constant reinvestment in GPUs, capital allocation is critical.
Is the brand exposure really worth it?


$BSP up nearly 50% as Berkshire Hathaway doubles down on Bending Spoons, adding another $330M on top of its original $600M IPO investment.
Headquartered in Milan, Bending Spoons acquires established digital businesses, restructures operations, improves monetization and cash flow, then redeploys capital into further acquisitions.
Q2 2026:
Revenue: $704M, +126% YoY; organic growth + 3%
Adjusted operating income: $381M, a 54% margin
Leverage: 2.4x
The playbook is clear: buy mature digital assets, optimize costs and monetize existing users rather than rely on organic growth.
An Italian $CSU in the making?

$LVMH Q3: The weakness is concentrated in its most important profit engine.
Solid growth in the US, Europe and Japan, but weaker Chinese demand remains a headwind.
Q3 organic sales growth by segment:
- Fashion & Leather Goods: -5%
- Wines & Spirits: +6%
- Perfumes & Cosmetics: +1%
- Watches & Jewelry: +6%
- Selective Retailing: +8%
Imo, the key issue is China “Chinese clientele down mid-teens” (Asia ex-Japan -5% YoY), which is weighing on Fashion & Leather Goods, $LVMH crown jewel and a major profit contributor.
Loro Piana and the ultra-luxury segment have shown resilience, while demand for more accessible luxury, including Louis Vuitton, remains under pressure.
Interesting note from the earnings call:
“Management rejected price cuts at Louis Vuitton. It prefers to keep brand desirability and use self-help measures such as product newness. “
After a brutal ~40% YTD decline, the valuation at ~12 EV/EBIT multiple is starting to look very attractive.


$HGRAF So far, the timing has been spot on: ~70% downside since my original post, despite receiving some criticism for my initial views.
I still stand by my original thinking on this narrative-driven equity story. I see the potential for commercial scaling, and tech disruption but I still don’t see the hard evidence to justify even the current 1B$+ valuation.
I’ll keep following the story. I wish the business well, but based on the information available today, I’ll remain bearish and without a position.
Happy to change my mind if the facts or my view change.


I don’t short stocks, but if I were to take a mid-term short position, my candidate would be $HGRAF
@ 11.18 CAD share price
~4 B$ market cap
The stock is also up +30x over the past year, helped by heavy promotion across social media.
HydroGraph develops graphene, an advanced carbon material often called a “super-material” because it is:
- stronger than steel
- more conductive than copper
- extremely light and flexible
Graphene can be used as an additive to improve many products:
- coatings and lubricants
- batteries and energy storage
- plastics and composites
HydroGraph’s key claim is that its patented “Hyperion” detonation reactor produces ~99.8% pure graphene using industrial gases instead of mined graphite.
The graphene market could eventually be multi-B$ across multiple industries.
Sounds revolutionary, right?
2025 sales: 43k$.
That makes this essentially a pre-revenue narrative/story, while commercial contracts have not materialized at scale. The usual risks around financing and dilution are also present.
Graphene has been hyped for over a decade, yet widespread adoption remains limited:
- manufacturing at industrial scale
- integrating graphene into existing supply chains
- cost vs. alternative materials
Some short reports also argue that the company spends heavily on investment promotion relative to R&D and still lacks meaningful customers.
Short reports can be biased. But they highlight an important point:
The gap between narrative and revenue (and ultimately profitable operations) is very large.
Happy to be proven wrong and hear the arguments from the longs.
But in my view, investors should always do proper due diligence before investing, esp. in these kind of investment cases.
Is this a breakthrough material or just another market narrative?

$LMND is expanding its Tesla FSD insurance offering.
Tesla owners in 3 states with older HW3 cars can now get a 30% discount on miles driven with FSD engaged.
Newer HW4 cars already get a 50% discount.
$LMND uses Tesla’s Fleet API to see exactly when FSD is driving vs. the human.
I don’t see any significant financial impact on IFP or loss ratios in 2026, and likely only a very minor impact in 2027.
But this could become a very exciting feature to follow over time as autonomous driving adoption grows. Hopefully we get more insights at Investor Day or in the upcoming Q3 report.

Lemonade is upgrading its Car insurance game. By directly integrating with @Tesla vehicles, they’re eliminating the need for a UBI device in their Pay-Per-Mile product.
What this means strategically:
1. Lower costs, higher scale potential
No hardware or shipping means lower CAC and operational complexity. Tesla drivers get cheaper policies, Lemonade keeps more margin.
2. Better data, smarter pricing
Tesla’s API delivers richer driving behavior info than traditional UBI devices. More accurate risk assessment - more precise pricing and rewards for safe (potentially FSD) driving.
3. Stronger moat, seamless customer experience
A seamless Tesla experience may make Lemonade the go-to choice for EV owners. Switching friction rises when insurance is integrated directly into the car ecosystem, versus legacy players.
4. Optional upside to growth
While Tesla drivers are still a niche for Lemonade, this positions the company to capture a premium, tech-savvy customer segment first. Could be a small but strategic lever in gross-selling to other insurance products, and expand API capabilities for other EVs.
This isn’t just a product tweak, it’s a subtle but meaningful step toward smarter, lower-cost, data-driven insurance that could compound Lemonade’s competitive edge in EV insurance. Interesting to hear more about this in the Q3 report.
$LMND

"No real expectations for Sweden or Germany, both could easily be shut down given their ongoing struggles to scale profitably."
Closing the $Kamux Germany operations was announced today, and I wouldn’t be surprised if Sweden followed.
It’s sad to see the European expansion didn’t fly, but imo this is the right decision, just too late.
Germany H1 2025 adj. EBIT of -€2.4m justifies the tough decision. Closing costs of up to €14m are surprisingly expensive, but in the long term, exiting is the only right move in the current state.
$Kamux could still be a solid business if it focuses solely on the Finnish market, although the competition, especially from market leader Saka, is on a totally different level compared with 5 years ago.
From an investment perspective, I’d still definitely pass, even though you don’t often see companies trading at just 0.1x EV/Sales.
$Kamux – the gift that keeps giving:
First, an expected profit warning this morning.
"Kamux expects its adjusted operating profit for 2025 to decrease compared to the previous year."
The previos outlook was to improve.
Then, CEO Pajuharju steps down immediately. Founder & former CEO Kalliokoski returns from his COO role, an expected move ever since he came back to operative role.
IMO, $Kamux is now in crisis mode.
The Finnish business needs a major course correction just to keep its head above water.
Saka and others players have copied Kamux’s playbook and are executing more efficiently, leaving Kamux without a real moat. You can’t just blame the market anymore.
No real expectations for Sweden or Germany, both could easily be shut down given their ongoing struggles to scale profitably.
All the best to Pajuharju. While this wasn’t a great fit, I genuinely respect what he achieved at $Harvia - a proven leader with an impressive track record.

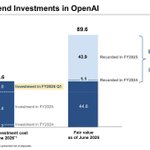
Want some early exposure to OpenAI ahead of its likely IPO in 2027?
As of today, SoftBank $SFTBY executed its final $10B investment and now owns ~13% of OpenAI, bringing its cumulative investment to ~$65B.
SoftBank has taken big positions before, with mixed results.
In its Q2 report, it was sitting on ~$45B in paper gains, likely even higher now.
That said, its NAV progress is impressive, while its largest position is still $ARM


$Boreo with another small but meaningful step.
The €1.6m TEXpro acquisition is small, but a nice proof that the M&A machine is working again after years of focus on organic operations. Following the hybrid debt restructuring, another positive development.
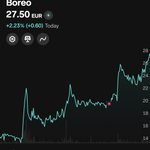
In hindsight, trimming around €19 wasn’t optimal short term, while still owning a sizable position. But this year Boreo has finally shown the long-awaited turnaround in its numbers, while the stock is already almost ~2x YTD.
Interesting side note: the former CEO + CFO duo has also launched “i2 enterprises”, seemingly pursuing a similar serial-acquirer model, still relatively new in Finland. Curious to hear more. Good luck to them.

$LMND Renters expanding, the new state this time: Alaska.
The expansion nicely supports the ~30% annual IFP growth trajectory. It’s not just the geographical expansion I’m watching, but especially the cross-selling across segments, including Car and Pet.
Solid execution ahead of Q2 and Investor Day.


Oura delaying its IPO despite “strong demand” raises questions:
Is this really just market environment, with investors focused on the upcoming Anthropic/OpenAI mega-IPOs or was demand for Oura weaker than suggested?
The financials are impressive:
$1.21B revenue in 9M, +74% YoY
$60.8M net income vs. $1.6M last year
The story is compelling, with strong growth, profitability and tailwinds. But competition is coming, potentially from Apple, while the valuation looks stretched on traditional metrics at + $10B

Big milestone for both Oura and $HOOD
Robinhood lands its first-ever IPO underwriting role with Oura.
Congrats to all Oura owners and employees.
Great to see a Nordic / Finnish success story potentially reaching a +$10B valuation.


Rolex is auctioning four unique Daytona watches today in London, with 100% of proceeds going to charity.
Each watch is a one-of-one, combining high jewellery, rare natural-stone dials and the latest-generation movement.
My guess: I wouldn’t be surprised to see eight-figure prices (€10m+) per watch.
Imagine if Rolex were a publicly listed business. I’d love to own it.

Is the greatest European venture investor of all time coming from Estonia?
Jaan Tallinn led Anthropic $124M Series A in 2021, when the company was valued at just ~$461M post-money.
He was also an early investor and board member at DeepMind before Google acquired it.
For many years, he has been putting significant focus on AI safety including the race between AI labs, US-China competition and AI growing ability to improve itself.
His philosophy is fascinating: invest in AI companies, generate outsized returns, and use those returns to fund nonprofits working on AI safety.
But not only Anthropic and DeepMind, but early investments in SpaceX and Oura, which is also heading toward the public markets.
And here’s where it gets crazy.
My estimate, based on publicly available sources, is that Tallinn owns around 1% of Anthropic after his early investment.
At current IPO valuation range speculations, that would imply a potential ~$20B position.
Potentially close to a 1,000x return in ~5 years, even accounting for the heavy dilution since the Series A.
Absolutely wild.
And perhaps even more exciting is seeing where Jaan Tallinn ultimately allocates the winnings from what could become one of the greatest venture investments in European history.


Trip booked to New York for the $LMND Investor Day in November.
Very grateful for the opportunity to participate, and I can’t wait to meet fellow investors and the management.
I’ll write a longer post on the current state of the business, but the Investor Day comes at a particularly interesting point for both $LMND and the broader insurance industry.
A few things I’ve been watching closely so far, and will focus on:
- Strong IFP compounding as scaling across products, states and cross-selling
- Continued improvement in loss ratios and reinsurance economics, with inprocing LAE ratios
- The $TSLA collaboration, with smaller pricing for FSD-enabled driving
- The path toward positive EBITDA and net income while still investing heavily in growth
- Rising Opex and management’s rationale behind the higher cost structure
- A potentially structurally changing insurance market, where AI agents can increasingly compare pricing and coverage across providers
A lot to unpack.
Exciting times ahead for $LMND
and hopefully I’ll be a shareholder for many years to come.


Rockstar, congratulations $REMEDY on the Control Resonant launch and what a strong start it has been, as indicated before go-live.
Very curious now to see how the sales will convert to the bottom line, given this is a major self-published game for $REMEDY.
Also, how will Rockstar’s upcoming, perhaps the biggest game, but also a global media product of all time, GTA 6 disrupt / impact the gaming market in a few months?

Congrats to our friends @remedygames on the launch of CONTROL Resonant!
controlgame.com

ALT CONTROL Resonant artwork
Good point on $Remedy.
I’m also rather confident that, given its niche AAA game genre and high quality, there would be an appetite to acquire the company. There have likely been multiple offers in recent years, especially when the market cap was only €200–300M.
$TTWO could be the most obvious buyer, but I could also see fully private players being interested in taking $Remedy private.
That said, given the current ownership structure, founder Markus Mäki owns ~20%, and my take would be that he is not interested in selling.
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more
In Good Company by @NicolaiTang1 one of my favourite podcasts, with a great guest: @alexstubb
Well-articulated on why he is one of the most influential European politicians at the moment, although I might have some Finnish bias.
Great takes, especially on tech disruption / AI from a political and societal perspective, and on how the global world order is changing as we speak.
open.spotify.com/episode/4Yp…

36/x
Vallan kolmio by @alexstubb
10/10
While I aim to keep my reading thread to English language books, I’m making an exception for this one, it’s that good.
The next world order won’t be decided in Washington or Beijing, but in the Global South.
That’s the core argument, one of the clearest frameworks I’ve read on how power is shifting between the West, East, and South.
“Value-based realism"
The West can’t defend democracy, open markets, and rules-based cooperation with moralism alone. It needs to stay anchored in its values and be pragmatic enough to strike deals, compromise, and build coalitions beyond its traditional partners.
If you’re trying to understand the next 5-10 years of global politics, this is a sharp map of the forces at play. Highly recommended, and the english version should be published also soon.
My takeaway:
The West doesn’t need a new ideology.
It needs discipline: hold the values, accept the world as it is, and engage the South with respect, compromises and pragmatism.

Is one of the hottest Nordic or even European IPOs of 2026 coming from Finland and the defence / drone sector?
Sensofusion is preparing to list, and the numbers immediately caught my attention:
EBIT margin >60%
ROIC in the triple digits
Sales growth ~100% annually in recent years
The company builds counter-drone systems combining detection, AI, software and electronic warfare. The interesting part is that this is already a real (and very profitable) business, with defence customers and systems deployed in actual conflict zones.
The IPO is also about funding the next leg of growth. Sensofusion is raising around €300M, targeting more R&D and production capacity as demand for counter-drone technology accelerates.
The obvious question is valuation.
At the indicated valuation at ~€1.3B, you’re paying a high multiple of today’s revenue and earnings. So the investment case depends heavily on whether Sensofusion can keep scaling while maintaining a meaningful part of those exceptional margins.
LTM EBIT sits around €30M, so let’s say EV/EBIT would be ~35x considering the IPO proceeds.
Sounds expensive on an absolute basis, but if they can keep compounding, that multiple could melt very quickly towards more attractive levels.
Also worth noting: the business has been bootstrapped, and the founder/CEO still owns ~80%. Wild.
The key for me: how much of today’s profitability is structural, and how much is simply the result of being in a very favourable part of the defence cycle?
How deep is their moat in the competition landscape given the highly lucrative defence and esp. (counter) drone sector?
Definitely one to follow closely.

$SSH1V, negative profit warning due to customer delivery delays, with 2026 profitability estimates being cut.
Operating margin is still expected to remain negative in 2026.
The strategic Leonardo partnership announced in summer 2025 is interesting, but concrete evidence of its impact in the numbers is clearly still lacking.
I’d like to see evidence of sales scaling, operating leverage and improving cash flow, as the defence domain is interesting.
That said, it was confusing to see the SSH chairman openly criticize $Inderes negative target price on LinkedIn last year. In hindsight, that clearly wasn’t the wrong call, with the stock now down ~43% YoY.
And IMO at the current price of EV/S ~5x definitely its still not cheap either.
