

Father, husband, veteran and business owner who also likes the stock market. Any stock speculation or charting is for Fun and Not Financial advice.
Saratoga Springs, NY
Joined May 2022
- Tweets11K
- Following443
- Followers478
- Likes8.8K






Canada built a global advantage that most Canadians don't know we have.
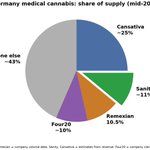
We're the world's largest exporter of medical cannabis, supplying roughly half of Germany's medical cannabis imports. That lead took nearly a decade to build. Other countries are now closing the gap.
In Maclean's, our CEO James Yamanaka argues the bigger risk isn't overseas. It's a policy framework still built for the market Canada had in 2018.
"Canada has built a global advantage in cannabis. Now we need public policy that helps us keep it."
Read the full article.
macleans.ca/sponsored/organi…
#CanadianTrade #Exports #CdnPoli


IndepenDan retweeted

Democrats: “Trump talking about Nikki Minaj was so disrespectful and unprofessional.”
Also Democrats:

$OGI Q4 FY26 projection 🧵
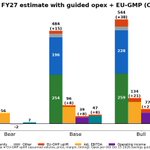
Guidance is over C$350M for FY26, and the first nine months were C$229.1M, so Q4 needs about C$121M.
Canada rec is about C$65.5M, from Headset store sales with the store and wholesale markups and excise taken out. Sanity in Germany fills the rest. Margins are about 40%: Canada recovering from the pre-roll problems, Germany in the 40s.
Q4 scenarios (C$M):
Bear: 112 rev, EBITDA 15
Base: 121 rev, EBITDA 22
Bull: 128 rev, EBITDA 27.5
Q3 actual: EBITDA 13.4
At guidance, EBITDA is up about 65% QoQ and operating income is positive. These are my estimates, not company figures.
$YOLO

Greg, the totals aren't wrong, but the comparison is. Most of that jump in liabilities isn't debt OGI has to pay back in cash. A big chunk is BAT's preferred-share stake, which accounting puts on the books as a liability and revalues every quarter. That's the same non-cash item that pushed Q3 net income to $105M. The rest mostly comes from buying Sanity: its payables, plus the 2027 earn-out (the extra price owed to Sanity's sellers if it hits targets). Cash fell because they spent it on Sanity and Germany, and you're comparing a 2023 company with a 2026 one that's about twice the size. Look at cash burn per quarter. It's shrinking, and the one-time deal costs (~$11M) roll off in FY27.
$OGI $CBWTF


"The Market" 🧐
$CBWTF


EU is part of the world big brain. yikes
$CBWTF


IndepenDan retweeted

Canada built a global advantage that most Canadians don't know we have.
We're the world's largest exporter of medical cannabis, supplying roughly half of Germany's medical cannabis imports. That lead took nearly a decade to build. Other countries are now closing the gap.
In Maclean's, our CEO James Yamanaka argues the bigger risk isn't overseas. It's a policy framework still built for the market Canada had in 2018.
"Canada has built a global advantage in cannabis. Now we need public policy that helps us keep it."
Read the full article.
macleans.ca/sponsored/organi…
#CanadianTrade #Exports #CdnPoli
Reading financial statements is useless if you don't understand the decisions behind the numbers. Understanding them is what helps you predict what comes next.
Comparing $OGI and Auxly ($CBWTF) on current numbers alone misses it. Ask why management does what it does.
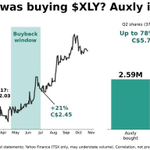
A buyback isn't a growth signal. It can mean management sees nowhere better to invest, or it's propping up the price ahead of the next share offering. Auxly has diluted about 22 times since 2017.
Think like a CEO and stay unemotional.

$OGI vs Auxly ($CBWTF): projected revenue through 2028
OGI: FY26 guided to C$350M or more (+35%). With Sanity/Germany, FY27 projects to C$428–495M, and C$524–700M in FY28 if that pace holds.
Auxly: about C$180M in 2026 (+19%), then just +3–6% in 2027. Its greenhouse is near capacity and inventory is falling.
The orange bars show Auxly's expansion: 30% in its written guidance, up to 50% per the CEO. Even starting Jan 2027, retrofit, grow, dry and test time push the first new sales to Q1 2028, reaching about C$220–239M that year.
Even at its best case, Auxly reaches about a third to half of OGI's projected FY28 revenue.
Only OGI's FY26 figure is company guidance. The rest are my projections from year-over-year growth.
IndepenDan retweeted

Promises made. Promises kept. $MSOS

Weed was never a carrot for midterms. Those people are using their own carrots . Democrats could have legalized cannabis 2 times over already and did absolutely nothing.
Actions speak louder than words, no matter how many quotes to wants to post.
Amendment 3 and schedule 3 vs trust me this time.
$MSOS
$CBWTF share price is due to buybacks and its limited market exposure helps during buybacks.if auxly ever dilutes, the drop will be pretty large since they made up 78% of the volume by themselves.


$OGI valuation math: EBITDA vs FCF 👇
Starting point: Q4 FY26 guidance (FY revenue >C$350M means Q4 ≥C$121M). I left out Q1/Q2 since they were hit by one-time issues.
Next 12 months (my est.):
Canada +2%/yr, Sanity +8%/qtr
Adj. EBITDA ~C$73M, or ~C$84M if EU-GMP lands ~Jan '27 (C$0.50/g saved plus Moncton supplying Sanity)
FCF ~C$44M, or ~C$54M with EU-GMP, after capex, R&D, German tax, leases and interest
Per fully diluted share (229.9M, includes BAT preferred and Sanity earn-out shares):
10x EBITDA: C$2.96–3.41 (US$2.09–2.41)
10x FCF: C$1.92–2.35 (US$1.36–1.66)
Today: C$1.31 / US$0.93, about 4–5x EBITDA and a ~15% FCF yield. Peers trade around 8–10x EBITDA.
Catalysts: Q4 results in Dec and Berlin's EU-GMP decision.
My estimates, not company guidance. +++ position
$CBWTF $CRON $SNDL $HITI $MSOS $VFF


