Founder of Northwise. Trying to understand technology, incentives, and where the value goes.

Joined September 2026
I've been adding to $NBIS during this correction because I think the market is still underestimating the business Nebius is building. The demand matters enormously, but so does the question of who pays for the infrastructure needed to serve it. That is why I've spent so much time on the asset-light program. Nebius wants partners to fund and own the data centers and GPUs while it provides the cloud platform, operating standards and customer access. If that works, growth can reach beyond what Nebius can finance on its own balance sheet. Partners supply the heavy capital, and Nebius earns a fee from making their infrastructure useful to customers. I see that as essential to the longer-term investment case. It could reduce the capital Nebius has to supply for each increment of growth, preserve funding for its own campuses, and add a higher-margin stream of platform revenue. Over time, more of the business could depend on the value of the software and service, with less revenue growth tied to another enormous hardware purchase. Our conditional 2030 Base case shows what that could mean: about $11.2 billion in annual asset-light revenue, $7.5 billion in adjusted EBITDA, and $4.5 billion in cash available to Nebius after taxes, reinvestment and liquidity needs. That is roughly a 67% adjusted EBITDA margin for the segment. These are modeled outcomes that require strong execution. Management has not guided to these figures, and more than half of our simulated portfolios landed in the lower outcome band. This connects directly to what I've been discussing recently: higher revenue potential from new hardware, faster deployment through brownfield sites and colocation, and a software stack that gives customers more reasons to choose Nebius. Asset light adds another way to capture that opportunity, provided the economics also work for the partners supplying the capital. The fee is where the hard questions start. Owners still have to earn an acceptable return after financing and replacing their hardware. Nebius has to keep delivering enough value to justify its share. I wanted to understand how those incentives affect the size, timing and cash generation of the business. Our new report, The Cloud Someone Else Pays to Build, works through that question in detail, with a separate 2030 asset-light model and 15 exhibits. Management has provided limited concrete specifics on the program. This is an assumption-driven framework, and I expect us to develop and revise it repeatedly over the next several quarters as contracts, fees and project delivery become clearer. The entire report is free. The companion Excel workbook is Premium and sits alongside our existing 2030 company model, which remains available. Full report in the first reply.
2
1
48
6,024
I would be careful about giving Celsius $CELH credit for closing the gross-margin gap with Monster. The energy drink companies put freight in different places on the income statement. Celsius includes outbound freight in cost of revenue. Monster reports distribution expense below gross profit. In the chart's hypothetical example, that change alone moves gross margin from 49% to 56%, with operating profit unchanged. I would count cheaper manufacturing, better truck routes and more productive marketing as progress. Before putting a margin improvement into a forecast, I want to identify the business decision that actually earns it.
166
Someone could use Meta $META's Muse on a phone, through glasses and on another device while paying for one subscription. That is the first thing I would check in a forecast built around device shipments. How many devices reach a new customer, and how many give an existing customer another way to use the same service? The October 9 Base model assumes 75% of Muse-enabled device users already belong to the organic user base. Devices still help: they add an estimated 4.76M paying users by 2030, including existing users who become more willing to pay. I like the hardware case better when it explains how convenience changes behavior. Counting every device as a new subscriber would skip the part that actually needs to be proven.
205
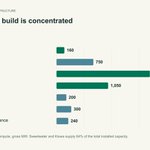
The site names I keep coming back to in our $IREN forecast are Sweetwater and Kiowa. Together they account for about 64% of Base installed compute at the end of 2030. That makes their delivery and customer acceptance disproportionately important to the result. A company-wide capacity headline can obscure that concentration. I would rather understand progress at the sites carrying most of the forecast than treat every announced megawatt as equally close to earning.
5
677
The enormous antenna on an AST SpaceMobile $ASTS satellite makes more sense when I start with the weakest part of the connection: the ordinary phone in someone's pocket. That phone has limited power and a small antenna. Asking the customer to buy a special terminal would change the product. AST is putting much of the engineering burden in orbit so the customer can keep using a familiar device. Moving from roughly 693 to 2,400 square feet of antenna area gives about 3.46 times the collecting area. Under ideal assumptions, that is approximately 5.4 dB of additional antenna gain. It does not translate directly into 3.46 times the revenue or network throughput. I find the commercial logic compelling: make the infrastructure more capable while keeping adoption simple. The execution test is whether AST can repeatedly build, launch, deploy and operate that infrastructure at a cost the service can support.
4
5
58
2,439
Alani, the energy drink owned by Celsius $CELH, grew retail sales about 56% in the second quarter of 2026. Revenue reported for the brand grew about 21%. I find the gap more useful than either number on its own. Retail data follows what shoppers buy. Company revenue also reflects distributor orders, inventory timing and how much of each sale Celsius keeps. More volume moving through delivery partners can put Alani in more coolers while leaving Celsius with less revenue per unit than a direct sale. I want to know whether better reach earns enough additional demand to justify that trade. An inventory adjustment can unwind. A different share of the shopper's dollar can persist. That distinction changes what I would expect from a rebound. I can give a temporary stocking problem time to settle. I would be less forgiving if strong retail growth depended on giving distribution partners an ever larger share of each sale.
1
458
Our $NBIS asset light model (ALM) will be dropping shortly! Don’t underestimate the importance of this model for a number of reasons. 1. Nebius is going to need extraordinary capex to develop and equip its data centers. The asset light model offers a high margin avenue for funding these requirements with little additional expenses. 2. The ALM will open up a number of partnership and geographical opportunities where the cost benefit equation didn’t before make sense for a full colocation or greenfield build. 3. With potential licensing of Nebius’s software stack, the team will receive real world data and feedback from an entirely new host of customers, many of which may become much larger long term spenders. 4. Reputation. Nebius has already overcome much of its history in Yandex and less than desirable questions surrounding its ability to be a trustworthy option for sovereign AI. By partnering with $PLTR and others to solve this issue head on, Nebius makes a clear stride to illustrate its status as a trusted collaborator in a growing emphasis to control sensitive internal data. 5. Optionality and diversification. The AI infrastructure buildout will undoubtedly face challenges of physical bottlenecks, as well as potential political roadblocks. The ALM gives Nebius a clear path to going to where access is already secured and a way to generate billions off of the execution of others globally. Very excited to hear more from management on this soon, hopefully providing us with guidance that can be used to better forecast individual deal economics, potential partner sizing, and different avenues of implementation. Cheers to shareholders. Nebius continues to surprise even our aggressive assumptions just about every week.
4
7
1
57
3,582
Despite recent market volatility and the AI selloff, $NBIS remains my highest-conviction investment and is once again the largest holding in our portfolios. It’s rare to find a generational opportunity at the intersection of seemingly insatiable demand, low-cost financing, and management execution that continues accelerating despite the company’s growing scale. The Street expects roughly $16B in exit ARR for 2027. Following Q2, our full-company model projected approximately $31B. I increasingly believe even that may prove too low. Management has discussed short-term capacity deals approaching $50M in annualized revenue per MW. If Nebius can capture more of this demand through short-term auctions rather than locking capacity into lower-priced multiyear agreements, revenue per MW could meaningfully exceed our assumptions. Combined with accelerating capacity deployment, $NBIS could potentially exit 2027 at more than 2x current Street expectations. I’ve been deploying significant cash from our flagship and active Growth portfolios during this selloff. Looking beyond 2027, our models suggest $NBIS could surpass $100B in annual revenue by 2030. I increasingly believe even that extraordinary forecast could be exceeded. Two developments are changing my expectations. First, Vera Rubin could materially increase the revenue potential of newly deployed capacity, particularly in short- and medium-term contracts. Alongside Nebius’s expanding software stack, including Token Factory and zero-day model support, the company is moving further beyond commodity GPU rentals. Second, capacity acquisition is accelerating. Much of our original forecast depended on greenfield developments across the US and Europe coming online in 2028 and 2029. Management’s hybrid approach, incorporating brownfield acquisitions, colocation, and faster near-term deployments, could pull substantial revenue forward. Higher revenue per MW combined with faster capacity deployment creates enormous upside to our existing scenarios. New management announcements continue strengthening the probability of our bull case. Of course, none of this comes cheaply. Our CapEx forecasts are also substantially above Street expectations. But unlike the financing concerns recently surrounding $CRWV , Nebius benefits from a strong cash position, attractive debt terms, and significant flexibility across debt, convertibles, equity, and potential subsidiary monetizations. Management has demonstrated an impressive ability to balance these financing sources without compromising growth. I suspect the upcoming Q3 earnings could be a major catalyst if management provides formal 2027 ARR and CapEx guidance. Both figures could catch Wall Street badly off guard. The market continues to underestimate not only the scale of infrastructure Nebius is building, but also the increasingly valuable software platform sitting on top of it. $NBIS remains my highest-conviction long-term holding, and recent volatility has only strengthened that conviction.
24
28
13
361
79,243
Awesome read from the team on why we see $NVDA as a solid growth compounder through the end of the decade. We entered the space through $AMD just a few years on ago on X and Reddit, and argued that the sector had more than enough room for two major players. Through our work with $NBIS and the other neoclouds, we believe we have a view of the sector that most analysts are missing by just focusing on hyperscaler capex. The three main neoclouds ALONE are projected to spend more than 750b in capex through 2030 in our models. A significant portion of that is going straight ti NVDA chips and networking. Nvidia is not purely reliant on increased debt capex from the big names. There’s a whole other angle here that is purely dominated by Nvidia that most analysts and the market is missing.
Our work on Nebius $NBIS and IREN $IREN keeps bringing us back to the same conclusion: we are bullish on NVIDIA $NVDA. These companies are building AI data centers, and the cost of filling them with computing and networking equipment is enormous. Add CoreWeave $CRWV, and our forecasts imply more than $415 billion of potential NVIDIA purchases across the three companies from 2026 through 2030. For the cloud operators, that spending creates hard questions about debt, dilution and how much cash will eventually reach shareholders. NVIDIA earns revenue when the equipment ships. The financing burden on one side of the transaction helps explain the growth opportunity on the other. If those buyers lose access to capital, NVIDIA's orders get hit too. We also see NVIDIA capturing more of each data center's equipment budget through CPUs, networking and complete systems. AMD $AMD and custom chips are becoming stronger alternatives, but the purchasing base is broadening across independent clouds, sovereign projects and enterprises. We think the market is still underestimating that combination. Our new NVIDIA report and editable 2030 financial model are live. The operating analysis is free to read, with the valuation, entry prices and workbook available to Premium members. Link in the first reply.
7
887
Awesome look at why we are so bullish on $SOFI at these levels. Stellar execution continues quarter to quarter and we believe many are underestimating the value of persistent member growth and increasing cross selling over time.
We are bullish on SoFi $SOFI because a larger customer base can earn more through infrastructure and capabilities the business has already spent years building. Our 2030 Base forecast reaches $14.14B of revenue and $4.42B of net income. That implies a 31.3% net margin using the ratio of the two averages, above management's long-term 25% to 30% objective. This is an ambitious Northwise forecast, not company guidance. It does not assume costs disappear. Operating costs before stock compensation and depreciation rise from about $3.34B in 2026 to $6.65B in 2030. Stock compensation, depreciation, credit provisions and taxes still reduce what reaches shareholders. The earnings upside requires revenue to grow faster than that cost base while lending losses and deposit pricing remain manageable. Cross-selling has to produce useful activity, and partner distribution has to retain attractive economics. That is the execution we are backing. The chart shows both the potential reward in the income statement and the operating commitments required to reach it.
1
5
549
Awesome read from the team into $ASTS as it moves much further up our watchlist recently. Very nice integration into our previous work on $SPCX $RKLB and $AMZN Leo
AST SpaceMobile $ASTS is trying to keep ordinary phones connected where cell towers stop. We think its technical lead and carrier relationships give it a real chance to turn that promise into a valuable business. We've followed AST for a long time, but valuation kept us cautious even as we liked the business. That discipline has paid off. After the recent selloff, AST is much higher on our watchlist today. A carrier can extend coverage without asking customers to buy a special handset or leave their existing plan. AST gains access to those customers through companies that already handle the billing and distribution. That is a strong starting point for a new network. We see a path to more than $5 billion in annual revenue by 2030, but getting there requires AST to deliver enough capacity where people actually use it. Spare capacity over the ocean does little for a crowded network over Texas. As more customers connect, the quality of service and the terms carriers will accept become central to the economics. Shareholders also have to fund the journey. Launching the constellation, expanding it and eventually replacing aging satellites will consume substantial cash. How much AST needs to raise along the way will shape how much of the growing business belongs to each share. We like the opportunity and would still be patient about a new position while performance under heavy traffic and carrier economics remain early. Our new report, ASTS Stock Forecast 2030: The Capacity Behind the Coverage, is now live. The operating analysis is free to read, with our full valuation, scenarios and editable workbook available to Premium members. Link in the first reply.
3
547
I think Celsius $CELH has a credible route back from its shelf reset. I also want to be careful about the numbers that could make the recovery look better than it is. Remove the weakest products and average sales per remaining product can rise even if the surviving products sell exactly the same amount. Grow from a depressed year and the percentage can look encouraging while sales remain well below the earlier level. The two examples in the image illustrate those traps; they are not Celsius's actual sales history. The evidence that would give me more confidence is comparable products selling better across consistent channels, alongside sustained growth in the whole brand. I would become more cautious if the strongest recovery claim were still an improving average over a shrinking range.
1
1
673
Big buys across our top neocloud names today, fintech, emerging markets, and a new position for Northwise. Updates pushing to members shortly. Always be ready for opportunities fuelled by short term narratives.
1
9
662
When I look at Meta $META's AI spending, I start with the advertiser deciding whether to run another campaign. A shop owner does not need to care which model helped someone find her product. If the campaign brings in enough profitable orders, she has a reason to spend again. Better recommendations and ad matching can earn a return through a business she already uses. That is a strong starting point for Meta. The separate question is how much it costs to deliver those improvements. I find the distinction useful when reading about Muse, subscriptions and new devices. Those products bring additional ways to earn, each with its own adoption and serving costs. I want to understand what the existing ad customer is already paying for before giving the newer businesses credit for what they might become.
1
2
325
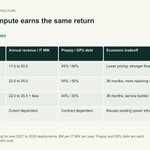
For $IREN, two customers using the same amount of power can create very different economics. An anchor customer brings a long commitment and financing support. A dedicated customer may pay a higher compute rate. A managed customer adds service fees, alongside more work and responsibility for IREN. I like the possibility of earning more from power the company already controls. But I would judge that progress through contract duration, credit quality, renewal terms and funding needs as well as revenue per megawatt. The most attractive customer is the one whose economics hold together across the whole relationship.
2
1
15
3,067
We see $KEEL $WULF and $CIFR as finally hitting buyable territory this week. We received a lot of flak for calling for caution as most on X pushed their audience to chase hundred percent plus moves. These are exciting companies with real long term opportunities, but there are real risks attached. At the end of the day, financing/dilution and determining how much of the value creation ahead actually reaches shareholders after the banks are paid is essential to crafting real models and valuations for these companies. Excitement and a cool sector are not excuses for abandoning fundamentals; this is a likely major opportunity for those willing to stay patient and to average into increased weakness.
2
23
3,716
Underrated piece of diversification that I think many people misunderstand on X is the ability of an active investor to liquidate uncorrelated or hedge like positions to take more concentrated risk at times like this. Just because you believe a $NBIS is a much better long term opportunity than SaaS (we do), doesn’t mean you can’t pick up $NOW and $CRM at criminal prices to play different sides of the game. We are putting up 100% TWR return this year without the anxiety that comes with 100% concentration and FUD generated market volatility. If neoclouds drop another 20%, we will have significant cash and other positions to liquidate to add concentration at the most optimal valuations possible. It helps to avoid chasing tops and if you’re smart about it many of these alternatives positions can offer pretty damn good returns in their own right if you are patient and selective. Don’t forget the importance of staying in the fight and keeping optionality. If Nebius dropped to $100 under catastrophic conditions, you’d never hear from a lot of the top names in the space ever again. While for us, it’d be an incredible long term rotation and concentration opportunity. Yes you may be young, yes you may have a high risk tolerance, but it doesn’t mean you have to sacrifice peace of mind and flexibility to chase in a sentiment driven environment. You can create a 100% growth driven portfolio and still survive when others liquidate. Highly recommend paying attention to the voices you hear at local tops vs local corrections. There are really savvy investors 100% allocated to our favorite names that will do very well long term. It doesn’t mean you have to mimic their exact strategy and take on the same stress. Most have other income sources and cashflows to make the risk tolerable for their individual circumstance. We don’t want our readers and members to copy us. We want you to challenge us and use us as a part of your investing strategy. If you agree with 100% of our takes, we encourage you to diversify your feed and resources. Some of our posts you should vehemently argue with. That’s our job and the service we offer. Offering retail institutional level processes, models, and analysis and asking for debate is where we are happy to take our stance. We’d be a lot more popular hyping trends and chasing the most popular stocks and always being agreeable and bullish at all times. Those names come and go, we are just getting started!
3
5
2
34
13,977
We are huge proponents for adding growth outside of our favorite neoclouds in $NBIS and $IREN $CELH offers one of the best noncorrelated outlooks, in our eyes, through 2030. I specifically see a lot of alpha in most analysts overestimating short term core Celcius problems as more than just a lapse in focus during the Alani and Rockstar SKU integrations. The other long term driver we see leading Celcius to potentially multiple hundred percent gains through 2030 is the international opportunity. Celcius is expanding abroad rapidly for the first time, and with Alani Nu, has a very very long runway ahead of it.
We are bullish on Celsius $CELH, the energy drink company behind Celsius and Alani Nu. A recovery in its namesake brand and a much larger Alani could leave shareholders with substantially more earnings by 2030. During the shelf reset, Celsius removed too many products and gave shoppers a reason to reach for another can. Restoring the assortment only starts the recovery. Repeat purchases will tell us whether customers are coming back. Alani gives us another reason to be bullish. Wider availability through Pepsi, more sales in existing stores and a growing overseas business could make it the largest source of new revenue through 2030. A steadier Celsius brand alongside a much larger Alani would leave shareholders with a very different earnings base. Our central forecast puts normalized earnings per common share at more than twice the 2026 level by 2030, after accounting for Pepsi's preferred claims. That distinction matters: growth at the company has to reach the people who own its common stock. The case still depends on Celsius winning shoppers back and Alani sustaining demand as it gets bigger. We think the potential reward justifies taking those risks seriously and doing the work before the recovery is fully proven. Our new report and editable 2030 financial model are now live. The operating analysis is free to read, with the full valuation and workbook available to Premium members. Link in the first reply.
1
1
9
1,638
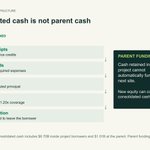
When I see a cash balance at $IREN, I want to know where that cash sits. A financed project may need to pay its own operating costs, service its debt and satisfy reserve tests before it can send money to the parent. Cash inside that project may be unavailable for the next build. Our Base 2030 forecast illustrates the issue: $7.7B of consolidated cash, with $6.7B inside project borrowers and roughly $1B at the parent. A healthy-looking group balance can therefore coexist with another equity raise. The location and restrictions on the cash matter to shareholders.
1
9
1,052