

Long-term investor. Looking for businesses I can own forever, knowing most don’t deserve that
Joined July 2022
- Tweets2.2K
- Following578
- Followers1.9K
- Likes15.3K




Zuck: “Muse is very compute-intensive to run, but we expect to improve its cost efficiency by more than 10x in the next year, which will enable it to be profitable once the revenue lines are at scale.“
$META


Morningstar: "[W]e continue to view ads, new products, and potentially subscriptions as much more enticing areas for AI monetization for Meta when compared with enterprise wallet share, an area in which the firm has little to no experience."
$META

"As a result, we will close approximately 250 coffeehouses later this week. This represents approximately 1% of our more than 18,000 North America coffeehouses."
$SBUX


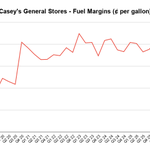
$CASY CEO: "We've taken significant share in fuel... with higher fuel prices, we're seeing exactly the type of behavior that we would expect to see. Fewer gallons per trip, but more trips made, which ultimately accrues to our benefit if we have more people coming to the store."

$MELI already +11% since the stock sold off after last earnings call
Slightly discouraging to see a stock move like that as I'm looking into it. But I also know that's an irrational way to look at it if the opportunity is still there
"We have a once-in-a-generation opportunity to transform how hundreds of millions of Latin Americans shop, pay and access financial services..
[W]e expect today's investments to compound into the same kind of structural advantages that our past investments have created."
$MELI

“Have you ever read management interviews that claim they aren’t innovative, don’t have the best business leaders, aren’t ‘leveraging’ technology…
Excellence is rare in this world, including the business world. You just won’t know it if you are relying on management interviews”

$MUSA: "New store growth will be closer to 45 new stores...While the stores are costing more, they're actually higher returning due to this fuel margin impact"
Murphy USA opened 51 stores last year, so 45 new locations in 2026 would be its 2nd fastest pace of openings since 2017

FY26 guide less than two months ago was for 7-9% organic sales growth and 7-10% EBIT growth
Now, 4-5% sales growth and low single digit EBIT growth
$HONA


Brian Niccol: "Sales growth in Q3 was broad-based across generations and income groups, and across both Starbucks Rewards members and non-members, even with the continued pressure on US consumer sentiment."
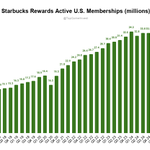
FYI, no YoY comp as $SBUX paused active member reporting in FY25

After two years of declines, Starbucks is expecting at least 6% growth in comparable store sales in FY26
Another positive is that a majority of the 8% Q3 SSS growth came from transactions (4.5%) compared to price (3.5%)
$SBUX

"For the 3rd quarter of 2026, Amphenol expects sales to be in the range of $9.3-$9.4 billion, representing a 50%-52% increase over the prior year. Adj. Diluted EPS is expected to be in the range of $1.40-$1.42, representing a 51%-53% increase from the 3rd quarter of 2025."
$APH
Morningstar on $TSCO: "We view shares as attractive and think the market is pricing in perpetual, rather than transitory, weakness in comps...We don’t see much change to our long-term prognosis"
Stock is now trading at ~16x trailing EPS
Moody's: "Hyperscalers have already exceeded our 2026 forecast for issuance and issued more debt this year than in the last three years combined"
$MCO

$GPC today:
“We are aware of recent market speculation about a potential transaction between the Global Automotive business and a competitor. I want to take this opportunity to officially confirm that we are not currently in discussions with any competitor.”


🇳🇴 Why I'm Adding To My Europris $EPR.OL Position
- Core business is stable and growing
- Acquired the loss-making ÖoB retail chain in Sweden (expected to turn a profit in 2028), losses blur the consolidated financials
- Stock close to 52-week lows, 4.5% div. yield
Link in bio!

The core business has reported EBIT margins of 13.9% and 13.6% over the past two years, but the losses in Sweden understate Europris' profitability
It also means the stock screens at a more expensive EV/EBIT multiple. The core business is valued at ~12x at today's price


Along with the fact that segment Sweden won't turn a profit for another 2 years, lack of catalysts until then + the boring industry Europris operates in, I think this has contributed to why the stock is at 52-wk lows and reasonably valued
*I own $EPR.OL and recently added more!