

Provides actionable trade ideas in real time before they trigger. My tweets are for entertainment purposes only and not financial advice.
Joined July 2020
- Tweets7.7K
- Following308
- Followers21.4K
- Likes4.6K




$PENG buy out rumors as well per betaville

BofA currently has $PENG at a Buy rating with a $100 price target, and the stock is at $55. That’s about 82% upside to their target.
What they see: Penguin sits at the intersection of AI and memory. AI driven businesses are already 78% of sales and grew 141% year over year last quarter. They think memory is becoming a bigger constraint than compute for inference and agentic AI, and a Tier-1 financial institution has already expanded its use of Penguin’s memory products.
The numbers are what stand out. BofA has 2028 EPS of $5.43 and revenue of $2.87B, versus the Street at $5.04 and $2.66B. At $55, that’s about 10x BofA’s 2028 EPS and about 11x the Street’s.
Their $100 target is only 18x that same $5.43. They also expect Advanced Computing revenue to almost double by 2028 and the memory cycle to last through 2028, with return on equity of about 45% in 2027.
A growing AI business, estimates above the Street, and a stock trading at about 10x forward earnings.

No matter how you feel about @chamath this is common sense. I have been saying it for 2 years $BTC will go to 0. It won't be long either with AI advancing rapidly every second.

CHAMATH SAYS BITCOIN WILL EVENTUALLY BE HACKED AND GO TO ZERO
Speaking on the Moonshots podcast, billionaire investor Chamath Palihapitiya warned that advances in AI could eventually break Bitcoin’s cryptography.
He argues that the community is too divided to coordinate a transition to quantum-resistant security.
“I just think it’s capped, and then I think eventually it gets hacked, and then it goes to zero.”
TheStockDon retweeted


PSA: In Q4, I always go into Shark mode hot or cold, it doesn’t matter. I don’t recommend it, but if you have a good risk tolerance, take your shots. $BBCI #LifeIsShort #RetirementGoals 🎯

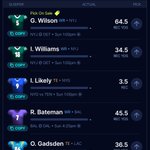
These are the overs I like this week. For daily fantasy the Geno, I Williams, Sadiq is a sneaky stack for GPP’s

$PPSI 10-K deep dive. Here's what the annual report tells you that the headlines don't.
First the customers everyone is guessing about.
Eneridge and SparkCharge are now named. 24% and 13% of FY2025 revenue respectively. That's 37% of sales disclosed. The Fortune 100 e-commerce depot customer and the rocket launch facility are separate relationships entirely, unnamed because they haven't hit the concentration threshold yet. The PRYMUS package delivery customer announced in May sits outside these two as well. Four distinct customer verticals. None of them overlap.
The package delivery customer. The 10-K language describes a national logistics business operating transit hubs. That's $UPS or $FDX territory, not e-commerce. Two 1.2MW PRYMUS systems. Delivery H2 2026. That customer has already signaled interest in additional systems for H1 2027 before the first unit ships. That is not a customer kicking the tires. That is a customer building a program.
The manufacturing base is locked. Champlin, Minnesota facility lease runs through March 2031. That covers the entire PRYMUS delivery and scale window without a facility constraint. They're not building this in a garage.
Service is the floor. 5,900 generators. 850 customers. Multi-site service contracts running one to five years. That recurring revenue base doesn't show up in the PRYMUS narrative but it funds the operation while the new platforms ramp.
The AI infrastructure case is in the 10-K verbatim. Global electricity demand for data centers projected to double by 2030. AI-optimized servers expected to account for 44% of total data center power consumption. The 5 to 10MW microgrid segment growing at 20.1% CAGR. PRYMUS is engineered for exactly that segment. This isn't management spin, it's in the risk factor section as a tailwind and a market sizing disclosure.
PowerCore is bigger than originally disclosed. The 10-K confirms 45kW, 150kW and 250kW versions targeting premium residential through estate-level. Level 2 infrastructure expected to see 5 million incremental units by 2026. PowerCore captures the convergence of residential resilience and high-speed EV charging in one product. H2 2026 shipments on track.
Now the setup.
$10.7M cash. Zero debt. $18.4M backlog up 32% sequentially. $200M active PRYMUS pipeline 80% data center. H2 2026 revenue guidance $15M. Manufacturing locked through 2031. First PRYMUS contract delivered to a major national logistics operator. Repeat order signaled before delivery.
$PPSI $BE $NVDA
NFA.
I called $PPSI back in April at 2.53 she ran to 6.29. I'm long again from $3 area for a huge rerate.
Let me tell you what the next 12 months could look like.
This is no longer a swing trade. It became a thesis.
April 17 the call was simple. Demand zone. $2.53. PRYMUS launching into the AI power gap. Stop $2.20.
Today the story is completely different.
$6M first PRYMUS contract signed. Package delivery customer already signaling repeat orders before first delivery.
$200M active pipeline. 80% data center. Five months after launch.
H2 2026 revenue guidance of $15M. 60%+ growth over H1. First time management has guided with that kind of conviction.
Backlog up 32% sequentially. Gross margin expanded three straight quarters. Zero bank debt. No dilution.
Here is what has to happen for this to re-rate over the next 12 months.
H2 deliveries execute on time. PRYMUS units hitting the P&L this year is what proves the hardware is real and the model works.
A second named contract. The first one took this from $2.53 to $4.61. The second one — especially a named data center customer — is what brings institutional money to the table.
Pipeline conversion. $200M in quotes is not $200M in orders. Even 10% converting is $20M in new PRYMUS revenue against a company that did $9.3M in all of H1.
PowerCore shipping H2. A second revenue vector nobody has modeled yet.
If those four things happen the valuation conversation becomes impossible to ignore. A $28M market cap against $25-30M in annualized revenue with 20%+ gross margins and a $200M pipeline is not a company that stays at $28M.
$BE was $16 before their Oracle moment. You know the rest.
PPSI still hasn't had its Oracle moment. The $6M contract was the proof of concept.
The Oracle moment is the next one.
$PPSI $BE $NVDA
NFA.

TheStockDon retweeted

Ive used trade alert for my options flow scanner for many many years...tried a bunch of other scanners and wasnt really what i wanted, so decided to build my own... after a couple months ive finally nailed it... if youd like to try it, offering 7 days for 7 bucks, let me know what you think...
scannerhack.com/
The "autonomy company so not NGSRI" logic doesn't really hold up. Anduril isn't autonomy-software-only, they build effectors. Roadrunner-M is a reusable air-defense interceptor and they moved into solid rocket motors with the Blue Ridge deal. A short-range interceptor is closer to their actual product line than the autonomy label suggests.
And NGSRI itself isn't as far from their wheelhouse as that argument assumes. A modern interceptor with an imaging IR seeker that detects, classifies and homes on a maneuvering target is doing a lot of onboard autonomy. The line between "autonomous system" and "smart interceptor" is blurry.
The AID language also reads like it was written to pull in exactly Anduril's profile, production ready, fast moving, non traditional. So I think they're a plausible entrant.
That said I'm not claiming it's a lock. Nobody posting on this has a source, it's a Sep 15 industry day that hasn't happened. Watch the attendee list.
What I am saying is with or w/o NGSRI is undervalued and this price action today is over blown.
$LPTH


I'm starting to scale back into one of my favorite companies $LASR for a swing here $43.70's.
$LPTH dump today is the market treating NGSRI as a lost Lockheed bid.
It’s not.
Army just added a 3rd competitor to LMT and RTX via the NGSRI Alternate Interceptor demo. Most likely Anduril. $LPTH already supplies Lockheed’s QuadStar seeker AND works with Anduril.
If Anduril the 3rd company which is likely, the odds this award involves LightPath didn’t go down. They went from a 50/50 LMT/RTX coin flip to something closer to 66%.
A 20% selloff on more paths into the same program is an overreaction.
Some of the greatest Optimus Prime Speeches. Rest easy Peter Cullen!
youtube.com/watch?v=86Y2a14P…
$INFQ NASA Awards Infleqtion $20 Million as World's First Quantum Gravity Mission Advances Toward Flight
$INFQ Q2 print. The EPS miss is noise. The quarter underneath is the opposite.
What matters:
Revenue of $12.6M, up 116% YoY, 100% organic and entirely from quantum. Beat the $10.6M estimate by ~19%. This is real commercial traction, not acquisition padding.
$582M cash, zero debt. The balance sheet gives them full runway to execute without dilution pressure near-term.
Commerce Dept LOI for up to $100M in proposed funding. Not a done deal, but that level of government validation doesn't come without a serious technical review.
30 logical qubits on track for 2026. Illinois quantum computer contracted for 2027. The roadmap is executing.
The EPS miss is entirely SBC-driven post-SPAC. The year-ago comp was when they were still private. The $(0.05) estimate was always going to be wrong. Non-GAAP net loss was $(0.06). Move on.
Full year guide raised to ~$43M. Neutral atom thesis getting validated at every level.
Execution phase has begun.
Not financial advice. Size accordingly.
I'm starting to scale back into one of my favorite companies $LASR for a swing here $43.70's.
$CLF 12.25 daily spot ✅ with 13.09 above there
Two federal arms are now funding $CLF's two monopolies:
DoW → $400M sole-source for grain-oriented electrical steel (only US producer)
DOE → $500M for Middletown, preserving the blast furnace route for automotive-exposed grade steel (the grade mini-mills can't match)
This is what industrial policy capture looks like.
NFA
$CLF Cleveland-Cliffs Announces $1 Billion Middletown Works Investment to be Supported by $500 Million U.S. Department of Energy Award


I called $PPSI back in April at 2.53 she ran to 6.29. I'm long again from $3 area for a huge rerate.
Let me tell you what the next 12 months could look like.
This is no longer a swing trade. It became a thesis.
April 17 the call was simple. Demand zone. $2.53. PRYMUS launching into the AI power gap. Stop $2.20.
Today the story is completely different.
$6M first PRYMUS contract signed. Package delivery customer already signaling repeat orders before first delivery.
$200M active pipeline. 80% data center. Five months after launch.
H2 2026 revenue guidance of $15M. 60%+ growth over H1. First time management has guided with that kind of conviction.
Backlog up 32% sequentially. Gross margin expanded three straight quarters. Zero bank debt. No dilution.
Here is what has to happen for this to re-rate over the next 12 months.
H2 deliveries execute on time. PRYMUS units hitting the P&L this year is what proves the hardware is real and the model works.
A second named contract. The first one took this from $2.53 to $4.61. The second one — especially a named data center customer — is what brings institutional money to the table.
Pipeline conversion. $200M in quotes is not $200M in orders. Even 10% converting is $20M in new PRYMUS revenue against a company that did $9.3M in all of H1.
PowerCore shipping H2. A second revenue vector nobody has modeled yet.
If those four things happen the valuation conversation becomes impossible to ignore. A $28M market cap against $25-30M in annualized revenue with 20%+ gross margins and a $200M pipeline is not a company that stays at $28M.
$BE was $16 before their Oracle moment. You know the rest.
PPSI still hasn't had its Oracle moment. The $6M contract was the proof of concept.
The Oracle moment is the next one.
$PPSI $BE $NVDA
NFA.
$PPSI Q2 just dropped. The story just got a lot bigger.
Forget the revenue line. Here's what matters.
$200 million.
That's the current PRYMUS pipeline in active customer quotes. 80% of it is data center projects. Five months after launch.
The $6M package delivery contract from May? That customer is already talking about additional systems for H1 2027. First units aren't even delivered yet.
Now the numbers.
Backlog up 32% sequentially. $18.4M at June 30 vs $13.9M at March 31. Order book is building fast.
Gross margin 19.6% in Q2 vs 13.6% in Q1 vs 2.2% a year ago. Three straight quarters of expansion. The one-time cost story is fully proven out.
H2 2026 revenue guidance: $15 million. That's 60%+ growth over H1. First time management has put a real number on it. PRYMUS deliveries hit the P&L this year, not just 2027.
$10.7M cash. Zero bank debt. Still no dilution.
And PowerCore just got bigger. Originally a 45kW system. Now adding 150kW and 250kW estate-level versions. Larger addressable market than anyone modeled.
PRYMUS had no contracts. No pipeline disclosed. No guidance.
Today: $6M first contract in hand. $200M active pipeline. 80% data center. H2 guidance issued. Backlog at 32% sequential growth.
This is what early looks like before the market fully prices it.
$PPSI $BE $NVDA
NFA.
$INFQ > 13
$INFQ Q2 print. The EPS miss is noise. The quarter underneath is the opposite.
What matters:
Revenue of $12.6M, up 116% YoY, 100% organic and entirely from quantum. Beat the $10.6M estimate by ~19%. This is real commercial traction, not acquisition padding.
$582M cash, zero debt. The balance sheet gives them full runway to execute without dilution pressure near-term.
Commerce Dept LOI for up to $100M in proposed funding. Not a done deal, but that level of government validation doesn't come without a serious technical review.
30 logical qubits on track for 2026. Illinois quantum computer contracted for 2027. The roadmap is executing.
The EPS miss is entirely SBC-driven post-SPAC. The year-ago comp was when they were still private. The $(0.05) estimate was always going to be wrong. Non-GAAP net loss was $(0.06). Move on.
Full year guide raised to ~$43M. Neutral atom thesis getting validated at every level.
Execution phase has begun.
Not financial advice. Size accordingly.