
Moonlighting as an Indian public markets investor. DYOD. Nothing is Investment recommendations.
Joined December 2020
- Tweets48
- Following1K
- Followers362
- Likes23






Pinned Tweet
Inspired by @persistencecap @9onecapital @SamitVartak @amitmantri @2point2capital @MGSolidarity and their efforts to discuss ideas in depth on X, wanted to share our thesis on PVR INOX. 🧵
Disclaimer: may hold a position. Academic discussion only, not investment advice.
A great lender at a bad-news price. Check out the full deck here - files.catbox.moe/vp77o1.pdf
Would love to hear your thoughts...
Not investment advice.
What we watch: the small-business book, rivals moving into its ticket size, Andhra Pradesh at 43% of AUM, and growth fading.
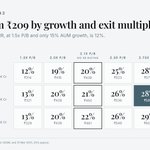
Each one runs through the multiple. On its own, none costs more than ~2 points of IRR at a 2.75x exit.

At a 2.75x exit, still 28% below the median, that is a ~28% IRR from ₹209.
With no re-rating at all, ~21%. The worst case on our grid, 1.5x book and only 15% growth, is ~12%.

Our base case sits below guidance: 17.5% growth (guide 22–24%), yields down 75 bps, funding cost up 25 bps, credit cost 0.55%.
Book value per share goes from ₹101 to ₹214 by FY31.

Four reasons, none about the franchise:
PE exit: WestBridge went ~37% to 4%, all above ₹290
Credit cost up to ~0.5–0.6%, partly a stricter write-off policy
Growth slowed to 21%, above the industry’s 19–21%
Debt costs ~70 bps more than peers; the gap is closing

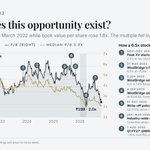
So why does this great business trade at 2.1x?
The price is down 45% since March 2022 while book value per share rose 1.8x. The whole affordable housing group de-rated, and Aptus de-rated the most, along with Aavas.

And the model travels. Tamil Nadu went from 72% to 31% of AUM as Andhra Pradesh became the largest state. Of ten regional lenders we looked at, none moved faster without an acquisition.

It is run by its founder. M Anandan spent 20 years at Cholamandalam before starting Aptus in 2010.
ROE has gone from 14.5% to 20.1% over FY21–26. The founder family holds 23.9%, unchanged through the PE exits.

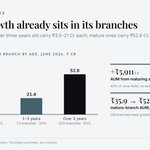
Growth is already sitting in the branches. 147 branches under three years old carry ₹3.5–21 Cr of AUM each; mature ones carry ₹52.6 Cr.
Maturing alone adds ~₹5,900 Cr, about 43% of today’s AUM.

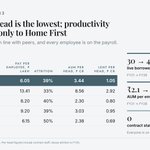
Cost per head is the lowest in the group (₹6.05 lakh), staff turnover is in line with peers, and everyone is on the payroll.
Live borrowers per employee went from 30 to 49 over FY21–26.

The underwriting has been tested: IL&FS, COVID, 250 bps of rate hikes, small-borrower stress.
Seven years, four shocks, ROA never below 7.4%.

And it does not give up credit quality for it. Credit cost averaged 0.44% of AUM over FY21–26. Gross NPA has never passed 1.7%. Average loan-to-value is ~40%, against 52–60% at peers.

The yield holds because of how loans are made:
No DSAs. 2,362 sales officers.
1,169 underwriting and collection staff.
325 in-house legal and technical staff.
80% self-employed borrowers that banks don’t serve.
Yield of 16.9–17.4% every year since FY22.

The higher ROA comes from a higher yield and lower opex: 17.2% on loans against 12.8–14.8% at peers, and opex of 2.7% of assets against 2.7–4.5%.

And with the lowest leverage among its peers: 2.6x assets to equity, against 3.0–4.2x.
7.8% ROA × 2.6x = 20% ROE. Low leverage leaves room to absorb a macro or industry shock.

While earning 2x the industry’s ROA: 7.8% in FY26, against 3.4% for affordable housing finance companies (CARE). The next-best listed peer is at 5.8%.

The business has grown at 25%+ a year over FY21–26:
AUM: 26.4%
Disbursements: 25.3%
Live borrowers: 26.5%
Branches grew 12.3% a year, so each branch now serves 1.8x the borrowers it did in FY21.

Aptus lends to self-employed families in Andhra Pradesh, Tamil Nadu, Telangana and Karnataka, secured on their homes. About ₹7 lakh outstanding per borrower.
Today: ₹209, 2.1x book, 11.1x earnings. Median since listing: 3.8x book.

It has happened before in Indian NBFCs:
Gold loans, 2013: Muthoot fell to 0.9x book, back to 2.0x in eight months.
Vehicle finance, 2020: Chola went from 1.6x to 5.7x within a year.
Microfinance: CreditAccess halved twice and re-rated twice.


One of our favourite mental models: when the market de-rates an entire industry, it throws the baby out with the bathwater.
The highest-quality names often fall more than the industry, then re-rate first and come out stronger.
We think Aptus Value Housing is one. A 🧵. Please share your thoughts, and happy to discuss this!
This is just for academic purposes, not a recommendation. Please do your own research and diligence.
