

Not Financial Advice - postings are never a recommendation to buy - perform your own due diligence before putting any money at risk. *NOT A FINANCIAL ADVISOR*
Joined December 2013
- Tweets8.1K
- Following287
- Followers961
- Likes30.3K


Investing 4 Life retweeted
Too little too late for the original shareholders you wiped out with your reverse split. We were just stepping stones. Good luck to you and anyone else investing in you.
Hope you never need another stepping stone to wipe out the next round of shareholders.
$FRQN
$MAJI
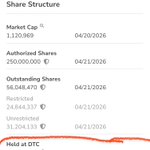
Matt did state at the beginning that the share structure is now MAXED out at 250mill shares. That is an insanely low 850k market cap at the current price of .0034!!


Investing 4 Life retweeted
xitter.cf/i/spaces/1AJEmvAoNPAJL @NexTelMedical @socialstartnow1 @OTCMarkets @papaspoppinpeny @CrusaderStocks
🤖 Made with AI

Staying dark with the whole OTC heating up is not the best idea
It’s more important now to update and keep shareholders informed
Update on the acquisitions?
Update on any contracts or agreements as revenues begin this month (last we heard)?
$MAJI
@NexTelMedical
@MikeSheikh2
$MAJI
@NexTelMedical
Any update on the closing of the acquisitions with Casey?
Should have been completed by now, right?
I remember hearing 60 days or sooner from Casey and he seemed optimistic in the initial interview.
I believe an update on where things are is warranted.
Investing 4 Life retweeted

$MAJI is pleased to unveil the final packaging design for Maxasome Health Check, our saliva-based cancer screening test kit. More updates to come.
🤖 Made with AI


Investing 4 Life retweeted
$MAJI — As part of our upcoming consumer education initiative, we are developing an educational video series detailing our diagnostic technology. Building on visual concepts similar to the cancer therapy video below, the series will demonstrate how tumor-derived exosomes travel through the lymphatic system and are collected in saliva using our non-invasive cancer screening test.
Investing 4 Life retweeted
NexTel Medical Corp. Announces Next-Generation Wellness Product Line Incorporating FDA-Approved Pharmaceuticals accessnewswire.com/newsroom/…

Investing 4 Life retweeted
Thrilled to announce a key milestone for $MAJI! We’ve received our initial bottle order to fill, label, and seal for pre-launch product sampling across multiple locations. With our first commercial pallet arriving next week, production is ramping up quickly for our full market launch!


Investing 4 Life retweeted
NexTel Medical Corp. Showcases Pioneer Exosome Technologies and Diagnostic Innovations at Leading Healthcare Conference accessnewswire.com/newsroom/…
Investing 4 Life retweeted

$MAJI this is huge! Beautiful catalog and ton of products, including ones we havent seen before
This should generate some nice opportunities for sales and distribution
Perfect Storm coming together auth maxed, reg a complete and product launches/sales
This quoted post is unavailable.
Investing 4 Life retweeted
$MAJI
Regardless of market action, opinions, updates, etc… the real question on any OTC company/stock is can they realistically achieve a certain anticipated/desired market valuation based on where they are and what they have (or expect to have).
In the case of $MAJI, a $10mm+ valuation would be a major success for shareholders from these levels. So that is the desired valuation in this scenario
Let’s take the assumptions that the 250 million authorized shares are fully issued and outstanding as well as the Regulation A offering is closed. Can $MAJI reasonably be framed as having a path to a valuation above $10 million. This implies a share price above $0.04 on a fully issued 250 million share count.
This is not a statement that the stock is currently worth that, or that it will get there. It is a case built on the company’s disclosed assets, pending commercial pieces, and the capitalization reset we are assuming.
Capitalization assumptions
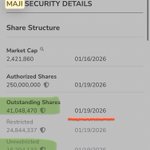
OTC Markets data as of September 18, 2026 shows 250 million authorized shares and 205.094,303 million outstanding (restricted ~133.6 million; unrestricted ~71.5 million). Market cap on that count is just over $1 million at recent prints near $0.006.
The assumption is that the remaining authorized shares are issued and the Reg A (File No. 024-12629; up to 50 million company shares plus selling-shareholder shares, price amended downward over time) is finished and closed. That removes the live “more cheap paper coming from this specific offering” overhang and sets a known 250 million share denominator. Any cash actually raised in the offering would sit on the balance sheet; any remaining authorized capacity would be gone.
A $10 million equity value on 250 million shares is $0.04. That is a large multiple from recent trading levels, but it is a modest absolute valuation for a company that claims a combination of (1) a revenue-generating telehealth/distribution platform, (2) a near-term consumer product launch, (3) a patented early-detection diagnostic, and (4) an FDA Orphan Drug Designation in glioblastoma.
What the company actually has
NexTel is developing mammalian and plant-derived exosomes with proprietary loading and targeting methods, initially in oncology and now also in wellness, diagnostics, and (via LOI) neurodegeneration.
1. Telehealth / distribution platform (Island 40 / JumpstartRx / NueVistraMed)
Definitive merger agreements were signed in May 2026 and later amended to acquire Island 40 Group and its subsidiaries for $12.75 million ($3.5 million cash + $9.25 million preferred). Management has claimed ~$135k–$140k per month in baseline recurring revenue (~$1.6–$1.7 million annualized), a network of 1,500+ online clinics and 350+ physical facilities, and hundreds of thousands of monthly patient interactions. The preferred is $1 stated value, convertible after 18 months at $1 (with a true-up), so it is not immediate common-stock dilution.
As of a September 4, 2026 offering circular supplement, the deals have not closed. The company stated it did not then have the cash and that the targets still needed to deliver PCAOB-audited financials. Closing is therefore still an execution item, not a completed fact. If it does close, even a conservative 5–8x revenue multiple on the stated run-rate, plus the distribution channel for Maxasome and diagnostics, is enough by itself to support mid-single-digit to low-double-digit millions of enterprise value.
2. Maxasome™ consumer / wellness line
Plant-derived (including mushroom) exosome products for dermatology, dentistry, and wellness. Management reported completion of contaminant screening (negative for key pathogens) and entry into final stability testing, with commercial launch targeted for late 2026.
A first-of-its-kind mass-spectrometry characterization study with Penn State (SAB members Dr. John Bitzer and Dr. Marvin Hausman) is intended to identify bioactive compounds (beta-glucans, polyphenols, terpenoids) and support new patents. That study was originally expected mid-2026 and later pushed.
Biospace
Exosome skincare and functional wellness is a crowded but high-multiple space. A clean, characterized, additive-free line sold through an owned clinic network is more valuable than a standalone “we have a cream” story.
3. Nanog saliva-based cancer screen + veterinary expansion
Patent US 11,193,174 covers a saliva (not blood) exosome isolation approach for ultra-early cancer-related signals. Management has targeted IRB work and a commercial window as early as fall 2026, and has separately announced a veterinary oncology screen aimed at the $1B+ North American companion-animal oncology spend. Central-lab processing would create a recurring test-volume model.
Diagnostics businesses are valued on volume, reimbursement, and clinical utility—not on hope. If the test is real and can be sold through the acquired clinic network plus vets, it is a second revenue engine. If it is not, it is a press-release asset.
4. GBM / malignant glioma — FDA Orphan Drug Designation
The company (via Exousia AI / related filings) received FDA Orphan Drug Designation for an exosome-loaded nucleic-acid approach intended to be used with temozolomide (TMZ) in malignant glioma / GBM. Preclinical work used humanized mice implanted with patient-derived GBM cells; management and SAB commentary have emphasized targeting of cancer stem-cell programs (NANOG/OCT4) that drive TMZ resistance. ODD brings fee waivers, tax credits, and seven years of U.S. exclusivity if a product is approved.
ODD does not equal a drug. It does, however, make the program partnerable and gives it a scarcity value that pre-revenue microcaps often lack. Even a modest option value on a GBM stem-cell delivery program is material relative to a $10 million cap.
5. Other pipeline and holdings
LOI to acquire Xycota Biosciences (preclinical exosome delivery for frontotemporal dementia; ODD application; expansion path into ALS and mTBI). Not closed.
CBD-loaded milk-derived exosomes for oral delivery (earlier commentary; the company has also announced a strategic exit from cannabis/CBD branding).
Controlling stake in L A M Y ($LMMY) from the November 2025 swap of Exousia AI for ~41.2 million LMMY shares. That stake is itself a small OTC position (recent prints near $0.02 imply low-seven-figure mark-to-market at most) and was intended as a funding source for acquisition cash.
Why >$10 million is a coherent (not guaranteed) number
On 250 million shares, $10 million is a small company.
The bull case is additive:
Closed telehealth platform at even $1.6 million ARR and a 6x multiple ≈ $10 million before any product attach.
Maxasome launch through that channel adds high-margin product revenue.
Nanog (human + vet) is a second product line with recurring test economics.
GBM ODD + preclinical data is an out-of-the-money call option that sophisticated buyers sometimes pay mid-single-digit millions for in isolation.
Closed Reg A + maxed authorized share count removes one source of surprise dilution and, if any cash was raised, improves the balance sheet.
Comparable private and small-public exosome, diagnostic, and specialty-telehealth stories have been financed well above $10 million with less distribution and no ODD. That does not mean MAJI will trade there; it means the asset mix is not inherently capped at sub-$1 million once the share count is known and the offering is finished.
What has to go right — and what already went wrong
Execution is the entire story. The Island 40 / Jumpstart transaction still required cash the company said it did not have as of early September 2026. Preferred stock issued in an acquisition is future common-stock supply. Historical share count has risen sharply (from the mid-40 millions a year earlier to ~197 million by September 9, 2026, including a 107 million share increase in two days). Financials are unaudited. The corporate history includes multiple name and business-model changes.
A closed Reg A and a hard 250 million share ceiling do not fix those issues. They only make the capitalization math honest. If the telehealth close happens, Maxasome ships, and the diagnostic generates even modest paid volume, a $10 million-plus equity value on that share count is not an extreme claim. If those items slip or the preferred converts into a new wave of paper, the same 250 million shares can stay a sub-$2 million stock.
This is not investment advice. It is a structured case under the two assumptions specified.


Investing 4 Life retweeted
$MAJI another strategic acquisition and auth is almost maxed out. Increase today was on previously completed reg a buys before re-pricing that weren't issued at the time... the push off theae lows could be explosive on a maxed out share structure and the product launch

Solid acquisition lately here for $MAJI share structure is perfect here for a really nice reversal off lows, only 71m unrestricted at .005


Investing 4 Life retweeted
$MAJI is pleased to announce that it has entered into a joint venture agreement to commercialize a novel patented formula within a rapidly growing health sector.
Market Highlights
U.S. Market Value: Currently exceeds $2.3 Billion
Global Market Value: Currently exceeds $8.0 Billion
Projected Global Valuation: Anticipated to reach $18.7 Billion – $23.1 Billion by 2030–2032
A comprehensive press release detailing the transaction structure, product specifications, and go-to-market strategy will be issued next week.
Investing 4 Life retweeted
$MAJI : we’ve refined the Health Check Screening kit to elevate the unboxing experience and protect kit integrity. The redesigned top-opening box features a custom component tray, a protective case for the saliva vial, and full shrink-wrap sealing. These enhancements deliver a significantly higher-value presentation at a minimal cost increase. Stay tuned for more updates.

Investing 4 Life retweeted

How u handle this Adversity tells many who, what & how u truly are. The good times comfort u but the hard times defines u. Let's be whom GOD has called us to be instead of whom the enemy wants us to be. You got this baby. Let's Live! #COACHPRIME