
Turning complex finance into simple steps | Family, investing, and building for the future
Joined October 2011
- Tweets1K
- Following705
- Followers269
- Likes1.2K



Pinned Tweet
But the most interesting part for me is was this -
J.P.Morgan thinks that SOFI will ultimately be a winner in the neo/digital bank space and could eventually become the "America Express" of fintech!

Donatas Macinskas 🇱🇹🇺🇦 retweeted

Here’s something almost no one knows:
A Lithuanian biotech team Genomika encoded the national anthem into DNA molecules.
Yes — literal music stored in living material.
They also encoded works by composer Čiurlionis.
Not science fiction.
Just Lithuanian innovation at work.

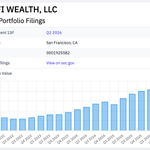
A small $SOFI data point few people track: SoFi Wealth (robo-advisor) 13F holdings.
Q2'22: ~$0.6B
Q2'25: ~$1.6B
Q2'26: ~$2.5B
+52% YoY, ~4x in 4 years. Part of it is market beta, but the trend is clear: members don't just borrow at SoFi, they invest there too. @FunOfInvesting @Futurenvesting @SoDakZak @AverageDipBuyer

Donatas Macinskas 🇱🇹🇺🇦 retweeted

Kaunas welcomed @NordVPN ambassador Shaquille O’Neal into their home. 👋💚

1/ In 2026, hitting estimates has been a reliable way for $SOFI to lose 9–15% in a day.
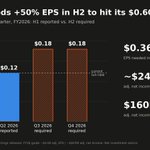
Now the guide asks for more: FY26 adj. EPS of ~$0.60. H1 delivered $0.24. That leaves $0.36 for H2: ~$0.18 a quarter, +50% vs the current run-rate.
Context: EPS has been stuck at $0.12 for three straight quarters (Q4'25, Q1'26, Q2'26), partly on dilution.
The bar is higher than the EPS math suggests. Adj. net income guide: ~$825M. H1: $327M. H2 needs ~$498M, i.e. ~$249M/qtr vs $160M in Q2 (+55%).
Diluted share count swung from 1.378B (Q1) to 1.325B (Q2) on convertible treatment, so EPS and dollar net income can diverge. Watch dollars, not just EPS.
Implied margin step-up: H1 adj. revenue was $2.29B, so the FY guide ($4.75–4.85B) leaves $2.46–2.56B for H2. Adj. net margin must go from ~14% in H1 (13.3% in Q2) to ~20% in H2.
Meanwhile Q2 S&M was +48% YoY, and the CFO said they chose growth over "adding even more profitability."
What happens to the stock if Q3 prints $0.18? A thread 🧵

4/ Valuation isn't the problem for $SOFI. Trust is.
At ~$16.55:
- 27.6x the FY26 guide
- 23x a $0.18 quarterly run-rate ($0.72 annualized)
- ~20x FY27 consensus ($0.81)
Not expensive for 30%+ growth. The discount is about accounting and dilution, and only proof of earnings quality closes it.
What I'll check in the first 10 minutes of the release:
- Adj. net income in $ (needs ~$249M), not just EPS
- S&M growth vs revenue growth
- Fair value marks and gain-on-sale share of revenue
- Is the $825M profit guide raised?
- Member and deposit growth
5/ The one explicit upside lever management named is macro, not execution.
Management now assumes 1–2 Fed hikes in 2026 (vs 2 cuts in the original guide). Noto: "If there are no rate increases, we probably have upside to the bottom line."
Scenario odds are my judgment, based on 2026 earnings reactions and short positioning. Not investment advice.
Sources: SoFi Q1/Q2 2026 releases, Q2 call transcript, FINRA short interest, MarketBeat, TipRanks, IBKR price and options data.
Interesting one from $SOFI today. They've put their whole card program (~$25B a year) on stablecoin settlement with Mastercard. First national bank to actually do this, not just announce a pilot.
Nobody with a SoFi card will notice anything. This is back-office stuff, how the bank and Mastercard square up with each other. But settling around the clock instead of in weekday batches means less cash sitting idle, and SoFi earns the yield on whatever backs SoFiUSD.
Doesn't move the numbers much yet. Worth watching if merchants start using the coin though.
investors.sofi.com/news/news…

Donatas Macinskas 🇱🇹🇺🇦 retweeted

🇱🇹🇱🇻🇪🇪 Thirty-seven years ago, two million Lithuanians, Latvians, and Estonians joined hands in the #BalticWay and sent a powerful message to the world: we will be free!
Standing shoulder to shoulder across more than 600 kilometers, they showed that truth is stronger than lies, courage stronger than fear, and unity stronger than oppression.
What began as a peaceful call for freedom became one of Europe’s greatest success stories. #Lithuania, #Latvia, and #Estonia broke free from the Soviet empire, restored their independence, and rebuilt their democracies. They returned to the family of free European nations, joined NATO and the EU, and built strong, resilient, and prosperous states.
Today, the Baltic Way stands as a tribute to people who refused to surrender their dignity, their identity, and their freedom. It reminds us that when free nations stand together, no tyranny can silence their voice or determine their future.


Donatas Macinskas 🇱🇹🇺🇦 retweeted

In the next few years @SoFiStadium will host the Super Bowl, World Cup, and Olympics!
Brand awareness 🐎🚀
Institutional ownership 🚀🚀
Memember growth 🦫🚀
📈📈 ?? 🤷🏼♂️
unavailable
Must-watch for every $SOFI investor and every finance investor. No empty words, just pure explanations and insights into how they think.
Also covers several new business lines with dates.

The Anthony Noto Episode:
youtu.be/_XkSWXi2j-Y?si=eASC…

The market grades quarterly. The thesis compounds annually.
Trust curves don’t show up in 90-day prints. They show up when a 2022 student loan customer suddenly has a SoFi mortgage, SoFi credit card, and Plus subscription in 2027.
You can’t model that in a Q3 estimate.
Base case 2030: ~$23B revenue, 36M members, 2.4 products each.
Apply a reasonable 4.5x multiple and you get a market cap roughly 5x today’s.
I’ve watched this exact pattern play out in my own wallet over a decade with another digital bank. It’s the most underpriced dynamic in fintech.
@DataDInvesting @anthonynoto @FunOfInvesting @Futurenvesting @SoFi @SoFiIR