

Focused on service, speed and communication NMLS: 209726 (206) 251-0818 A division of City Mortgage Brokers, LLC || MB# 2158059 https://xitter.cf/t.co/GO8pjTR3h4
Seattle, WA, US, 98104
Joined November 2017
- Tweets1.8K
- Following59
- Followers36
- Likes0





Sell first and you move twice: movers, a rental, then movers again.
The Contingency Buster Program lets you buy your next home before you sell the one you’re in, so you move once and pay once.
See if you qualify: seattlesmortgagebroker.com/c…
#BuyBeforeYouSell #SeattleHomeBuyers

Already refinanced once?
Seattle rates have fallen in small steps since 2022, and most homeowners are waiting on one big drop to go again.
There’s a way around that wait, and we break it down here: seattlesmortgagebroker.com/p…
#RefinanceMortgage #RefinanceAgain

2
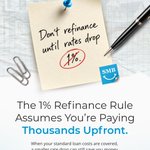
The old rule says to wait for a 1% rate drop before refinancing.
That holds when closing costs run into the thousands.
Our Step Down Refinance covers your standard loan costs, so a small dip saves you money.
See if you qualify: seattlesmortgagebroker.com/r…
#RefinanceMortgage

5
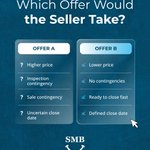
Two offers on the same home: one higher with contingencies, one lower and ready to close.
Sellers usually take the second, because every contingency is a question mark.
That's how buyers lose homes they loved and overbid on the next one.
Learn more at: seattlesmortgagebroker.com/c…

3
Refinancing usually adds the loan costs to your balance, so homeowners wait for a big rate drop.
Step Down Refinancing covers those costs, so even a small drop is worth taking.
Run your numbers at seattlesmortgagebroker.com/r…
Then refi again after six on-time payments.
3
Two lenders, same rate, very different deals.
The gap is in total loan costs, the fees to set up your mortgage.
Refinance and those fees get added to your balance, so you pay interest on them for years.
A low rate with high fees is still an expensive loan.

1
1
12
Most people know the home they're buying better than the one they're selling.
But one decision can swing your sale price by tens of thousands, and most make it without realizing.
Read this before you list: seattlesmortgagebroker.com/p…

1
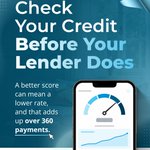
Most buyers check their credit when they apply, which is already too late to change the rate they're offered.
A 30-year loan has 360 payments, and a better score improves every one of them.
We review your credit early so you apply at your strongest.
#CreditScore #HomeBuying

1
The home you love won't wait for yours to sell.
Our Contingency Buster Program lets you safely waive contingencies and close fast.
So you can make a strong offer now without overpaying for the privilege.
See if you qualify: seattlesmortgagebroker.com/c…

2
Fixed or adjustable comes down to one question: how long will you stay?
Moving in a few years, and an ARM's lower starting rate can pay off.
Staying a decade, and a fixed rate's stability usually wins.
Message us, and we'll map your loan to your exit plan.

2
A client bought with us 18 months ago and has since done two step-down refinances.
Same monthly payment, lower rate each time, nothing added to their balance.
The result: 11.5 years off the loan and over $500K saved.
Run your own numbers: seattlesmortgagebroker.com/r…

1
1
A clean offer can beat a higher one, because sellers buy certainty.
Concierge Close front-loads your underwriting and locks a defined close date, so you negotiate on terms instead of just price.
See how it works: seattlesmortgagebroker.com/f…

1
A late closing is usually a small detail missed weeks earlier.
So answer underwriting fast, keep new credit closed, leave a paper trail on large deposits, and tell your lender before you change jobs.
We catch the rest from day one: seattlesmortgagebroker.com

Rates drop, but refinancing again adds thousands in loan costs to your balance.
So most homeowners refinance once and wait for the savings to catch up.
Step Down Refinancing removes that cost, so you can move down with rates.
see how it works: seattlesmortgagebroker.com/r…

1
Sell first & you're house hunting on a deadline.
Buy first & your contingency offer loses to cleaner bids.
Our Contingency Buster Program guarantees a backup contract on your home, so you can waive it & buy first.
See if you qualify: seattlesmortgagebroker.com/c…
#ContingencyBuster

1
Waiting on the perfect rate means paying extra interest while you wait.
If rates have dropped since your loan, the savings beat the costs, or your goals have shifted, it's worth a look.
See how our Step Down Refinance Program works: seattlesmortgagebroker.com/r…
#stepdownRefinance

1
10
Sellers don't always take the highest offer. They take the safest one.
A late loan or low appraisal can send them back to market weeks later.
Financed buyers can still win, often without being the highest bid.
Here's how we do ours: seattlesmortgagebroker.com
#SeattleRealEstate

3
Refinancing in Seattle can save you thousands, or cost you thousands.
It comes down to one line: total loan cost on your closing disclosure.
Check yours against these 8 mistakes: seattlesmortgagebroker.com/p…
#MortgageTips #SeattleRealEstate #RefinanceTips #ClosingCosts

3
Concierge Close finishes your financing upfront, then aligns your loan terms with your agent's contract strategy.
By the time you write an offer, you're already set for a clean contract and fast close.
Start here: seattlesmortgagebroker.com/f…
#conciergeclose #seattlehomebuyers

2
Your preapproval amount and the payment you can comfortably carry are two different numbers.
Guidelines don't know about daycare, repairs, or the trip you take every summer.
Before you shop, decide your own ceiling — then bring that number to your lender.
#mortgagepreapproval

1