
Macro & Rates
Joined August 2020
- Tweets583
- Following348
- Followers432
- Likes5.5K


RobertTimper retweeted

🇪🇺 Europe's borrowing costs now move with energy.
Our Chief Global Fixed Income Strategist @RobertTimper1 told @euronews:
⛽ Since Hormuz, EU yields track energy prices closely
🔥 Gas, not just oil, now driving inflation pressure
📈 Feeding through to higher yields
euronews.com/business/2026/0…

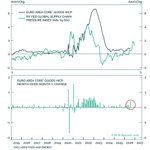
Today's euro area CPI data offers the first look at July inflation. The m/m increase in goods prices stood out at 0.41%, it was the largest increase in 3 years.
Could be a first sign of supply chain pressures from the SoH disruptions feeding into core goods inflation globally.

We get UK inflation data for June tomorrow. While the focus will be on the pass-through of higher energy costs, one thing to monitor is rent inflation.
Based on private market rent measures, disinflation in rent CPI has run its course.

After running well below pre-pandemic levels, rent inflation has picked up. Particularly, multi-family rent growth is rising in the last months, which is consistent with an apartment vacancy rate that has peaked.
To exceed current levels it would likely require tighter labor.

Japan's economy is booming and it's not (just) because of AI.
Wage growth has been very strong, with the 3-month annualized rate now at 5% in nominal terms. These high incomes are translating into strong consumption growth.
Yet the BoJ's policy rate is only at 1%...


Is US Monetary Policy Tight?
Credit growth is one way to assess the monetary policy stance. Corporate and credit card loan growth picking up strongly since the start of the year suggests policy isn't restrictive.
Meanwhile, it clearly remains restrictive for the housing market.

Unanchored UK Inflation Expectations?
Survey-based inflation expectations are well above their historical averages.
This should be the BoE's main concern amid this energy shock and could force it to act sooner rather than later. Market is only pricing a full hike by November.

RobertTimper retweeted

One of my favorite pod episodes ever! Cousin @JacobShap and I had my colleagues from BCA @ElClutch and @RobertTimper1 (the twin authors of the BCA World Cup Forecast) to talk about the Most Important Uninmportant Thing in the World!
podcasts.apple.com/us/podcas…

The 2026 World Cup is finally here!
As is BCA tradition by now, we have once again put together The Most Important Of All Unimportant Forecasts.
After correctly predicting Argentina to win in 2022, find out who we see lifting the cup this year: bcaresearch.com/reports/most…


A BoJ hike in June now seems all but certain.
April's meeting saw a 6/3 hold/hike vote split. Recent speeches suggest there are now enough votes on the Policy Board for a hike in June.
Both Masu's and Koeda's comments suggest they joined the hawks, making it 5 votes to hike.

Masu was extremely clear in his May 14 speech: "I believe it is desirable to raise the policy rate at the earliest stage possible"
Does the UK still have an inflation problem?
After yesterday's wage growth data and today's inflation data, the underlying inflation picture at least doesn't look different from DM peers.

That was quick. Bond market already won without even pricing any fiscal risk premium.
xitter.cf/alexwickham/status/205…

Despite the political turmoil and headlines in the UK, the gilt market has barely reacted to the risk of more fiscal spending. Yields have risen globally due to higher oil prices. The US/UK yield differential has been stable and largely driven by relative policy expectations.


The effect of last week’s yen intervention is already fading, with JPY/USD at 158. The real “intervention” necessary is BoJ rate hikes. 2-Year real yields are negative again, while rising long-term inflation expectations are hurting the yen. It’s time for BoJ hikes.

