

Founder of Pari Passu, research firm that provides all-encompassing coverage of the most consequential restructuring transactions. Join our free email list!
Join 25k+ investors/bankers 👉
Joined April 2022
- Tweets6.7K
- Following566
- Followers52.9K
- Likes5.3K





Restructuring__ retweeted

You know us as your creative asset toolkit.
Now meet @_MonoDesk, a whole new app from our team, built to handle the boring bits of creative work.
Less time on proposals, chasing approvals and sending invoices. More time on the creative side of your business.

Working in restructuring in 2026:
“Canva,
Create the org chart for Hertz:
- Increase a box to illustrate the restricted group
- Add a second box for the guarantor group
- Add a box for the Oro entity, which is now a JV
- Oh, add a middle finger for legacy 2L that got bought back at a 60% discount
Make no mistakes; you’re not an intern at a bottom-tier EB like Jefferies”
🤝 Paid partnership


Introducing Canva Craft 🚀
Extraordinary image generation is now available to everyone, powered by our first frontier model built specifically for design.
With Craft, Canva is now the world's second most advanced AI lab for image generation on @DesignArena's global leaderboard.
See what it can do 👇
"The liquidity bottleneck creates significant long-term pressures for LPs as they manage portfolio construction, pacing, and commitment levels.
With distributions still well below historical norms, LPs face complex decisions balancing immediate liquidity needs against continued exposure to potentially high-performing assets. Broker surveys show that 31% of LPs cite lack of distributions as the chief constraint on deployment."
What are you hearing from the market? What is impacting your fund the most?
Find full report below.
🤝 Paid partnership

Thanks to everyone for playing.
Getty Images is going back private.
The company went public in 1996, with a nice 30-year run.

Getty Images has filed for prepackaged Chapter 11 bankruptcy in Delaware as part of a Koch-backed take-private restructuring.
The plan includes up to $533mn in equity investment from the Getty family and Koch Equity Development, the retirement of $270mn in unsecured notes, and extensions to secured debt maturities.
Koch will also provide up to $143mn in bankruptcy financing. Existing shareholders will be wiped out, with the new investors owning 100% of the reorganized company upon emergence.

>lead product for news feed and creator monetization at meta and X
>spend years seeing exactly how things grow in the feed
>cofounder scaled facebook groups to 1bn+ users
>build nectar
>$40mm+ raised, backed by Anthropic's Anthology Fund
I spent way too much time doing busy marketing work while building Pari Passu, no alpha in that - great to see this!
🤝 Paid partnership

Engineers stopped writing every line of code and started directing agents.
Growth and marketing teams are in that moment now.
Meet the next chapter of Nectar: the agentic growth stack. One platform replacing 5+ legacy tools. Agents that work every message, creator outreach and creative research about your brand, and tie it all back to revenue 🍊

Congrats, key to have offline models especially for sensitive workflows
Not sure we want our healthcare info all over LLMs
Going a level deeper and quoting our legal analyst
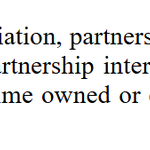
"At this stage, it’s worth getting granular about what a ‘Subsidiary’ actually means. For the purposes of credit documents and, by extension, LMEs, this is principally a contractual question: the documents themselves define which entities are classified as a Subsidiary.
In Xerox, the legalese largely boils down to identifying whether Xerox owns or controls more than 50% of the votes that can be used to choose the people who manage the entity. This would typically be ordinary shares in a company. If Company X controls more than 50% of the votes attached to equity interests entitled to elect Company Y’s directors, managers or trustees, Y falls within the Subsidiary definition and is a subsidiary of X. But if X owns 50% or less, Y may sit outside it. This creates a potential fourth recipient of dropdown assets: a ‘Non-Subsidiary’ (Non-sub), neither an NGRS nor an Unsub and therefore outside restrictions drafted solely by reference to those categories."
In Hertz, the same logic applies, see definition below.

Hertz, the next non-sub (JV) dropdown?
- Hertz has Oro Mobility in its own subsidiary
- Oro Mobility is Hertz’s side business that runs vehicle fleets for ride-hailing and robotaxi companies like Uber, a great asset
- Certares and Knighthead purchase 50% of voting units and 16% of common equity of that entity, the entity is therefore a JV (see next tweet)
- Hertz also agrees to retire $51mm of 2L due 2029 from Certares and Knighthead at 60% discount (which likely bought this debt before at even greater discount)
- Debt is retired at a discount, a JV is ready with unencumbered assets, Certares and Knighthead make a gain on the flip, everyone wins, right? Sorry to whoever sold their 2L to Certares and Knighthead ha!
The next step?
- Class, you now have a nice entity with unencumbered assets, a ParentCo which needs to extend its maturities. What do you suggest doing?
- Raise debt against those assets, a beautiful non-subsidiary dropdown. Maybe, yes!
Read our primer on Non-Subsidiary Dropdowns to learn more, awesome work from our legal analyst!


NON-SUBSIDIARY DROPDOWN PRIMER | PUBLISHED
This week, we are passing the pen from our financial analyst to our legal analyst to put the Xerox transaction structure under the microscope to understand how the Non-Subsidiary Joint Venture works, and where it sits alongside other landmark dropdown transactions.
We do this by looking at the history of both asset dropdowns and non-subsidiary LMEs (yes, Xerox was not the first, actually!), before running through a simple hypothetical transaction to demonstrate how the Xerox-style non-subsidiary dropdown works step-by-step and its use case: to get around popular asset dropdown blockers.
From there, this write-up takes an analytical and critical turn.
We think there are some features of the non-subsidiary dropdown that everyone is missing.
So we want to bring them to your attention and contribute to the wider discussion around these transactions. Our first claim is that it is too narrow to equate non-subsidiaries with minority-owned joint venture corporations. If we start from first principles, we can see that a joint venture corporation is a means to accomplish a non-subsidiary dropdown, but it is conceivable that there are other ways to achieve this.
Next, we claim that it is worthwhile to explore other options, as joint venture corporations do come with significant legal disadvantages for the borrower. In light of these disadvantages, we propose two alternative non-subsidiary structures, using US and UK law, that a borrower can use to avoid giving the incumbent lender majority voting power / an equity position in the entity with the valuable assets.
We then conclude with some thoughts on recent market developments and how to think about Xerox Blockers given what we’ve learned today.
We are incredibly excited to bring this analysis to you! Read below

