

Technology network for licensed banks and regulated financial institutions, bringing regulated stablecoins into bank workflows for cross-border payments.
Singapore
Joined December 2025
- Tweets86
- Following42
- Followers191
- Likes33


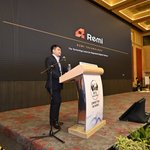




🛫Las Vegas → Houston🛬. A busy week for Remi. 👋
This week, our team joined Money20/20 USA and BAFT’s Regional Bank Conference.
Stablecoins can make a transfer faster. For a bank, though, there are still systems to run, compliance obligations to meet and customers to serve.
Remi connects existing banking systems with regulated stablecoin infrastructure, helping banks and licensed financial institutions add cross-border capabilities without starting from scratch.
Thanks to everyone who made time to meet the team. It was good to connect in person.
#Money2020 #BAFT


Buying a Treasury investment with stablecoins is different from earning interest just for holding those coins.
The US Office of the Comptroller of the Currency (OCC) published its final GENIUS Act stablecoin rule on 21 October. For covered issuers, one restriction remains: they cannot pay interest or yield solely because a customer holds, uses or retains a payment stablecoin.
An issuer promising “buy our coin and earn interest just by holding it” is describing the kind of payment the ban covers. Paying another company to deliver that prohibited interest does not get the issuer around the rule.
A customer using stablecoins to buy a separate short-term Treasury investment is buying an investment product. Think of buying a bond fund with dollars: the customer earns a return on the investment, not simply because dollars are sitting in an account. Paying with stablecoins does not, by itself, turn an investment return into interest on a stablecoin balance.
Calling something an “investment product” does not automatically make it compliant, either. If an issuer is still paying prohibited interest for holding a stablecoin, relabelling that payment “investment income” can still breach the ban.
Banks and licensed financial institutions should make the distinction clear: whether the customer holds stablecoins or has bought an investment, where the return comes from, and how to sell or redeem the investment when the money is needed.
The rule takes effect on 18 January 2027.
occ.gov/news-issuances/bulle…
#Stablecoins #Banking

How much a bank pays on deposits may influence how much people want to hold in stablecoins. A recent working paper published by the Bank for International Settlements examines that relationship.
Using weekly data from January 2019 to June 2025, the authors found that increases in US bank deposit rates were followed by slower growth in the total market capitalisation of reserve-backed stablecoins. They also tested the influence of crypto-market conditions and some DeFi yields; the main finding held.
One detail stands out: USDC responded more strongly to changes in US deposit rates than USDT. The authors suggest that USDC’s closer links to US depositors may help explain the difference.
We agree with the paper’s underlying assessment that deposits and stablecoins are partial substitutes. A bank considering stablecoin services, however, still needs to understand what its customers use stablecoins for.
Trading crypto assets and paying an overseas supplier are different uses. The paper does not separately estimate how demand for each responds to higher deposit rates.
Our view is that banks should account for the influence of deposit rates on stablecoin holdings. Deciding whether a stablecoin payment service is worth offering also requires understanding customers’ existing payment difficulties and whether the service can resolve them. Can the overseas recipient receive the money promptly? Are the fees reasonable? Changes in total stablecoin market capitalisation alone cannot answer those questions.
bis.org/publications/working…
#Stablecoins #Banking

Visa says one of its stablecoin payment pilots has moved into commercial production.
The interesting part isn’t another token launch. Eligible Visa Direct clients and partners can use USDC to prefund cross-border payouts through an existing platform and API connection.
The hard part isn’t making a token move. It’s making it fit the rest of the operation—funding, fraud controls, compliance and payout workflows.
That is the kind of connection Remi works on: bringing digital-money infrastructure into the bank workflows financial institutions already use.
Visa notes that availability depends on eligibility and geography.
corporate.visa.com/en/sites/…
#Stablecoins #Payments
A bank can have a stablecoin strategy without launching its own coin.
A customer paying an overseas supplier wants their bank to make it work. Using another institution’s token can be one way to offer that service.
Issuing a stablecoin means taking on reserve and redemption obligations.
Using an existing token calls for a different assessment: its issuer, how the asset works and what the bank is allowed to offer. It still takes homework.
Remi connects existing bank systems with infrastructure for bank-issued E-Money Tokens (EMTs). An issuing bank supplies the token; another bank can use it to serve its customers.
Start with the service you want to offer.
#Stablecoins #Banking
🎬 Back to Kuala Lumpur for a moment.
The official highlights from Asia Fintech Forum 2026 have landed.
Remi joined the 2 October event as Title Sponsor, with our team on stage and at the booth. We’re working to give banks new ways to serve their customers by connecting existing banking systems with regulated digital money infrastructure.
To everyone who stopped by for a chat: it was good to meet you. And thank you to the Responsible Fintech Institute for bringing everyone together.
See a familiar face? 👀
Watch the 1:44 recap:
youtube.com/watch?v=37QbxX7-…
#AFF2026 #Fintech
Fast money can still create slow work.
A cross-border payment may move in seconds, while the bank is left waiting for the instruction, the compliance data, or a clear status update to arrive. By the time operations teams start reconciling the records, one payment has become a small investigation.
New rails only help when they fit the systems, controls and responsibilities banks already run.
That is the layer Remi works on: helping institutions exchange transaction information, making status easier to see, and supporting the reconciliation and audit work that follows.
Speed matters. So does everything that happens after someone presses send.
#CrossBorderPayments #Banking
A bank shouldn’t have to build every piece of a new payment service itself.
On 26 September, Remi Co-Founder & US President David Cui joined the Payments Market Practice Group (PMPG) Annual Forum to discuss the future of correspondent banking—the network banks use to move money across borders. He was joined by Alejandro Pereyra of J.P. Morgan and Stephen Lindsay of Swift, with Sylvain Dauge of Société Générale moderating.
In his recap, David highlighted Alejandro’s practical advice on when banks should build, when to partner, and where their existing network remains an advantage.
That last point is easy to overlook. Banks already have customer relationships and knowledge of the markets they serve. New payment technology should help them do more with those strengths.
Remi’s work starts with those existing banking systems: connecting them with regulated stablecoin infrastructure and helping institutions exchange transaction information. The bank still decides how to serve its customers and remains responsible for compliance.
#PMPG #CrossBorderPayments
Being a licensed provider doesn’t make every stablecoin you support compliant.
That distinction is at the centre of ESMA’s 8 October opinion. The EU securities regulator says crypto-asset service providers authorised under MiCA, the EU’s crypto-asset rules, should stop offering EU clients services involving non-compliant stablecoins.
And it is not just about trading. Transfers and custody are covered too, with limited, supervised arrangements for winding down existing exposures.
For banks and payment firms, choosing a stablecoin is therefore part of designing the service itself. A token that works technically still needs to be suitable for the service and market where it will be used. That decision belongs near the start of a project, not on the checklist just before launch.
Remi’s focus is on bringing regulated stablecoins into the workflows of licensed banks and regulated financial institutions. New payment capabilities should fit the bank’s business, while the bank retains its customer relationships and responsibility for compliance decisions.
esma.europa.eu/press-news/es…
#Stablecoins #MiCA
At a financial forum, the spotlight belongs on the stage. That is where big ideas get their first public airing.
The harder part starts when those ideas move back into the bank. Can a new capability work with the systems and controls a financial institution already runs, without creating another isolated workflow?
That is the question behind many of our recent industry conversations. New digital finance only becomes useful when it can operate alongside the processes banks already depend on.
Remi works on that connection—bringing regulated digital finance infrastructure closer to the information, workflows and accountability banks already rely on.
A good idea can fill a room. A workable process is what keeps it moving afterward.
#BankingInfrastructure #DigitalFinance


Hello from Kuala Lumpur 👋
Remi was on stage and at the booth today as Title Sponsor of Asia Fintech Forum 2026.
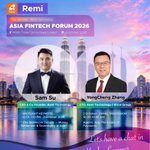
Our CEO & Co-Founder, Sam Su, delivered a keynote introducing Remi and our work to connect banks and financial institutions with digital finance.
YongCheng Zhang, CTO, Remi Technology / Bison Group, joined the “Agentic AI & The Future of Payments” panel, introducing Bison Bank’s E-Money Tokens (EMTs) and how Remi’s technology network supports cross-border payments.
Good to meet Kenneth Farrugia, CEO of the Malta Financial Services Authority, and Affendi Rashdi, Director-General of the Labuan Financial Services Authority, too.
Great to share what we’re building and hear what matters to people across banking and fintech. Thanks to @ResponsibleFT , our fellow speakers and everyone who stopped by our booth. Let’s keep the conversations going.
#AFF2026 #Fintech


AI agents and stablecoins usually show up in different conversations. On 2 October, both are on the programme at Asia Fintech Forum 2026, with Remi speakers taking part in both sessions.
Sam Su, Remi’s CEO & Co-Founder, will speak on “The Stablecoin Decade — Money, Settlement & Sovereignty in Asia.”
YongCheng Zhang, CTO, Remi Technology / Bison Group, will join the panel “Agentic AI & The Future of Payments,” exploring what changes when software moves from making recommendations to executing actions.
Different sessions, same practical test: can new financial technology fit the way banks actually work?
See you in Kuala Lumpur.
asiafintech.org/
#AFF2026 #Stablecoins #AgenticAI

More digital money shouldn't leave banks with more disconnected systems.
From Sibos in Miami, David Cui, Remi’s Co-Founder & US President, describes a shift from discussing tokenization to using it in real transactions. The next challenge is making sure all that building doesn't create a fresh set of “digital islands”.
Tokenized deposits, regulated stablecoins and central bank money may coexist. Banks need ways to work across those systems. Otherwise, every new network risks becoming another separate integration project.
That challenge reaches beyond the biggest institutions. Community and regional banks need practical ways to participate, too.
Remi helps connect financial institutions and link existing banking systems with regulated stablecoin infrastructure. For banks, the value of a new network grows when they can use it to work with other institutions and serve customers across markets.
#Sibos2026 #Tokenization
A payment can be fast and still be badly timed.
UK Finance says seven UK banks have completed live retail transactions through the Great British Tokenised Deposit (GBTD) initiative. In the pilots, mortgage funds were locked and released when completion took place. In a consumer marketplace transaction, funds were released only after the goods changed hands.
That is where tokenised deposits get interesting. The money does not just move faster; it can be linked to what is happening in the real world.
The underlying money remains commercial bank money, with the trust and protections customers already understand. Tokenisation adds programmability and a clearer link between the payment and the event it depends on.
The next test is operational. Can the bank’s own teams clearly track what was locked, what triggered the release, and what was finally completed? Connecting regulated digital-value infrastructure with the bank systems and transaction information teams already use is the kind of work Remi focuses on.
Read more: ukfinance.org.uk/tokenised-s…
#TokenisedDeposits #Banking
Miami next week. Let's talk banking over coffee.
David Cui and Steven Marshall will be at Sibos in Miami Beach, 28 September–1 October, representing Remi.
We'd love to compare notes with banks and financial institutions exploring bank-issued E-Money Tokens (EMTs) and cross-border payments. Especially the practical part: making new technology work with the systems and services a bank already has.
If you'll be there too, come and say hello.
#Sibos #Banking


A shop shouldn't need a crash course in crypto just to get paid.
On September 22, SoFi and Mastercard announced that stablecoin settlement is live for SoFi Bank's debit and credit card programme, using the bank's own stablecoin, SoFiUSD. Migration of the full programme is still underway.
SoFi says merchants don't need to hold stablecoins, build new infrastructure or change how they operate.
Keeping things simple for customers takes work inside the bank. Remi helps banks and regulated financial institutions connect their existing systems with bank-issued E-Money Tokens (EMTs). The aim is to make new digital-asset services fit into everyday banking, so customers don't have to figure out the technology themselves.
Running a shop is enough of a full-time job.
businesswire.com/news/home/2…
#Stablecoins #Payments

The interesting part of the ECB’s tokenisation push is not the token. It is what settles it.
On 21 September, the ECB launched Pontes, a Eurosystem solution for settling wholesale transactions in tokenised assets with central bank money. An initial group of market participants and DLT operators has completed onboarding and is ready to use it. More features and longer operating hours will be added gradually, with full implementation expected by 2028.
That is a useful reality check for the industry. Putting an asset on a DLT does not make the rest of the financial system disappear. The money, participant controls, transaction records, operating status and reconciliation still have to line up with the bank’s existing processes.
The less glamorous plumbing may decide whether tokenisation can move beyond a demo. For banks and regulated financial institutions, a new rail only becomes useful when it fits the controls and workflows already in place. It is the connective layer Remi is built around.
ecb.europa.eu/press/pr/date/…
#Tokenisation #Banking

Sending money home is usually framed as a question of speed and fees. The harder question is what happens after the transfer arrives.
The 2026 Sending Money Home report estimates that global remittances reached US$728.6 billion in 2025, with an estimated US$233 billion going to rural areas, where jobs, financial services and infrastructure are often more limited.
A payment is not really finished just because the value crossed a border. Banks still need to see what happened, reconcile the records, investigate exceptions and keep serving the person on the receiving end.
That is the less visible side of payment infrastructure: making faster digital transfers work with the institutions and controls already doing the job. It is the layer Remi focuses on with banks and other financial institutions.
Read the report:
ffremittances.org/data/sendi…
#Remittances #FinancialInclusion