

Event Driven, Deep Value w/ Catalyst, Real Assets, EM. 中文/Eng
Hong Kong
Joined June 2021
- Tweets13.1K
- Following5.1K
- Followers3.1K
- Likes18.7K


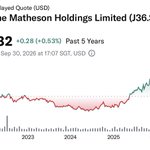




Jardine Matheson $J36.SI mean-reversion underway, catalyzed by mgmt empire building in healthcare sector. I’m a buyer in the low/mid 40s, assuming a pause in acquisitions.

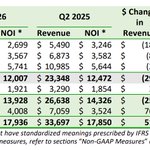
Sunbelt multifamily reit $BRT reported same-store NOI growth, while all peers are still negative. Not a bad result. Perhaps less oversupply in its less institutional markets.

My sense is that $GO.UN will eventually be sold, and this is effectively a pre-deal roll-up.
1997.HK reports solid results and 42% dividend hike. Total return >50% from 2024.

$AHH trading at nearly an 11 cap rate, noticing that 2Q results and stabilized NOI look much better vs 1Q. New mgmt conveniently negotiated a new share based comp package at the all-time low (after cutting the dividend and raising new equity).


Mr Market is offering a rare opportunity to buy Airports of Thailand $AOT.TB at a 50% discount.

I remain long Airports of Thailand $AOT.TB xitter.cf/justmikemckay/status/2…
All good things must come to an end. It's time to exit $AOT.TB to redeploy into another Hong Kong holdco discount situation. "Good boys go to heaven bad boys go to Bangkok"

SF REIT $2191.HK cuts rents payable by its parent by 20-45% in "realignment with prevailing market". Leverage was elevated at >7x ND/EBITDA before the rental cut, 90% payout ratio also elevated. Not uncommon for REITs to be listed with above-market rents, followed by a rug pull.

I'm long Krung Thai Card $KTC.TB, the only listed pure-play credit card operator in Asia, with an amazing track-record of compounding shareholder value. Shares crashed last year as a result of a margin call effecting a large shareholder. Trades at 11x PE after recent run-up.


Spectacular news for $CSR shareholders. Which mid-cap REIT is next?
ir.centerspacehomes.com/corp…


🏢 Centerspace Reportedly Weighs a Potential Sale
Centerspace $CSR — a multifamily REIT focused on apartment communities across the U.S. Midwest and Mountain West — is exploring strategic options, including a possible sale, according to sources familiar with the matter.
💼 Key Details
* Exploring strategic options: The company is working with advisers to review takeover interest.
* No final decision yet: Talks are in the early stages, and Centerspace could still decide to remain independent.
* Market reaction: Shares rose 2.5% to $60.22 on Tuesday following the report.
🏘️ Portfolio Snapshot
* 13,000 apartment units across 85+ properties.
* Core markets: Minneapolis, Denver, and Salt Lake City.
* Secondary markets: Grand Forks (ND), Billings (MT), Rapid City (SD), and other smaller Western cities.
* Strategy: Focused on stable, workforce-oriented housing in mid-sized and overlooked growth markets.
* Market cap: Roughly $1 billion.
📉 Recent Performance
* Shares are down 9% year-to-date, underperforming the broader apartment REIT sector.
* Faces similar headwinds as other multifamily REITs — rising financing costs, soft rent growth, and limited transaction liquidity.
🧭 Why It Matters
* A sale would mark one of the first major mid-cap apartment REIT takeovers since interest rates surged in 2022.
* Centerspace’s Midwest and Mountain West footprint could appeal to private equity or larger REITs seeking diversification outside high-cost coastal markets.
* As capital markets stabilize, multifamily M&A is expected to pick up — positioning Centerspace as a possible early mover.
investing.businessweek.com/n…
Theoretically $CSR should be sold at up to $90/sh (high 5s), but given recent precedents, I would expect a valuation closer to $75-80/sh (low to mid 6s) reflecting a 25-33% deal premium.
Huge disappointment with $CSR strategic review, tiny deal, cap rate not disclosed (suggestive of FFO dilutive deal). Seems like institutional appetite for multi-family is possibly tapped out.
$IMAX finally up for sale, its China sub $1970.HK accounts for ~50% of group NPAT, nearly 100% of historical cumulative FCF, trades at low single digit EBITDA mul vs. Parentco trading at a mid-teens mul. Chain rule applies to HKSE companies making the situation highly asymmetric.

$EPR restructuring of theatre leases with Regal, estimated to generate 96% of pre-bankruptcy rent, and 100% or pre-bankruptcy rent after reinvestment of asset sale proceeds.

$EPR selling its casino ground lease to Genting for $200mn at undisclosed "highly attractive cap rate". Transaction deleverages $EPR to sub 5x ND/EBITDA and funds growth for 2026, ATM tap no longer on the horizon. asgam.com/2025/09/17/genting…
