

Sovereign banking stress — the data that moves before markets do. Monitoring 30 countries. Real purchasing power for 190 currencies. Reserve Letter every Sunday
Joined May 2026
- Tweets1.4K
- Following74
- Followers242
- Likes2K





Banking fundamentals led every major crisis of the last 20 years. The data was always there — months before markets moved. Most people weren’t watching it.
We are. 🧵
QT has always been smaller and shorter than the QE before it — the historical record is unambiguous. The reason: structural buyers arrive every quarter regardless of Fed path. GPIF, Norges, US pensions, SNB rebalance into Treasuries mechanically. The system absorbs the balance sheet before the Fed admits it.

When the Fed does QE, the QT that follows is invariably smaller and shorter than QE. That's because we don't have the stomach for higher yields and higher volatility this would imply. We've shown - over and over - we can't handle a smaller balance sheet...
robinjbrooks.substack.com/p/…

The Dollar Milkshake Just Proved Itself Again.
@SantiagoAuFund dropped his most important episode in months this week. If you haven't watched it, stop and watch it first. This is my attempt to extend what he said with what's happening in real time right now.
THE CORE ARGUMENT
Brent's thesis in one sentence: The debasement trade is correct over decades. It is brutal over quarters. The path is where people get destroyed.
Gold peaked above $5,500. It closed below $4,000 on June 24. That's a 28% drawdown. Silver went from $88+ to below $58 — over 40% off peak. Crude -20%. Copper -8%. Wheat, corn, soft commodities all hit. The people who went all-in on the debasement trade at the highs earlier this year are now learning a lesson that Brent has been trying to teach for years.
The debasement thesis is not wrong. Fiat currencies lose purchasing power over time. Governments want it that way — it's a feature of fiat, not a bug. If they wanted a currency that held value they would use gold. They don't use gold because fiat helps them. That will never change. Over 10, 20, 30, 40 years — hard assets win. That's not the argument.
The argument is the path. And the path is determined by the mechanics of the dollar system.
THE DUAL CARRY TRADE — THE MECHANISM NOBODY TALKS ABOUT
This is the part of Brent's episode I want to focus on because it's the most under-appreciated concept in macro and it explains everything happening right now.
The entire world runs on a US dollar global carry trade. You borrow in dollars. You invest in something that returns more than the cost of those dollars. That's the game. The US does it. Every other country does it.
But here's what's different for the rest of the world: they fight TWO carry trades simultaneously.
When the US operates domestically, it uses dollars. When it operates globally, it uses dollars. One currency. One carry trade.
When Brazil operates domestically, it uses reais. Interest rates, loans, mortgages — all in reais. That's carry trade number one. When Brazil operates globally — buying oil, importing goods, settling international obligations — it uses dollars. That's carry trade number two.
One of those two carry trades is ALWAYS going against the rest of the world. Always. That's not a temporary condition. That's the structural design of the system.
When the dollar rises: the global dollar carry trade becomes harder to service. Dollar-denominated debt costs more in local currency terms. Every barrel of oil, every LNG shipment, every commodity priced in dollars costs more. EM central banks have to sell reserves to get dollars. Gold gets sold. Assets get sold. The debasement trade unwinds.
When the dollar falls: the local carry trade becomes harder to service. The local currency is strengthening — which means the local interest rate environment tightens in real terms. That's carry trade number two going against them.
There is no escape. One is always running against them. The question is only WHICH ONE and HOW BADLY.
WHY THIS EXPLAINS EVERYTHING HAPPENING RIGHT NOW
Bolivia broke its 15-year dollar peg this week. The official framing: "transitioning to a flexible exchange rate system to restore economic stability." The real framing: severe dollar shortage. Both carry trades went against Bolivia simultaneously. Gas revenue collapsed 18 months ago — the local carry trade broke first. Then the dollar strengthened — the global carry trade followed. When both go against you at once, you don't choose to abandon your peg. You run out of dollars and the peg abandons you. That's not a Bolivia story. That's the Milkshake mechanics playing out in real time.
Indonesia is doing an emergency dollar bond roadshow at 6-year yield highs. INR at ₹94. JPY at 161.77 — meaning Japan's dollar-denominated LNG contracts cost 58% more in yen than they did 10 years ago, before a single molecule of gas changed price. Philippines absorbing 122% diesel spike through the currency channel on top of the supply shock. These are all the same mechanism. Dollar carry trade going against them while local currencies collapse under the weight of it.
Meanwhile Americas EM is holding. BRL, MXN, COP stable. Mexico raised $9B internationally — 2.6x oversubscribed despite S&P negative outlook. Brazil $58B private infrastructure investment record. Colombia just completed a full five-leg sequence from banking stress to Pentagon security integration in under five months. The divergence between Asian EM and Americas EM isn't coincidence. It's structural. Americas EM is on the supply side of the disruption. Asian EM is absorbing the demand destruction.
WHY GOLD SOLD OFF AND WHY THAT'S NOT THE STORY
Brent explained this better than almost anyone has. Gold became a bigger portion of central bank reserves than Treasuries over the last 12 months. Two reasons: central banks bought aggressively post-COVID and post-Russia sanctions freeze. And Treasury bonds lost value as rates rose while gold more than doubled.
So when the Iran war started and a liquidity squeeze hit: central banks looked at their reserve portfolios. Treasuries were depressed. Gold had doubled. What do you sell to get dollars to settle global obligations? You sell the thing that went up the most and is the most liquid. Gold.
This is gold doing exactly what it's supposed to do. Insurance gets redeemed in a crisis. The fact that you CAN sell gold to cover liabilities in a crisis is gold acting as designed. This is not gold failing. This is gold succeeding.
But the price goes down while it's succeeding. And that's the part that breaks people.
When the crisis resolves — and crises are almost always met with more money creation in some form — gold recovers faster than almost everything else. That's the pattern from 2008. From 2020. From every prior episode. But first it gets sold. And if you bought at $5,500 because someone told you this was a one-way trade and fiat only loses value, you're now down 28% and the long-term thesis feels a lot less certain at 2am when you're looking at your portfolio.
THE DOLLARIZATION PARADOX
This is Brent's most counterintuitive point and it's the one that most people don't fully internalize.
When the dollar WEAKENS, that is actually MORE dollarization — not less.
Here's why. The only way new dollars enter the global system is through dollar-denominated debt. When the dollar index falls, that means foreign currencies are strengthening. That makes dollar borrowing cheaper for foreigners in local currency terms. So they borrow MORE dollars. More dollar debt = more dollar liabilities on foreign balance sheets = more dollarization.
Then the cycle turns. Local currencies start to fall again. The dollar rises. Now all that new dollar debt that was taken on during the cheap-dollar period has to be serviced with more expensive dollars. And the carry trade unwind begins again — but from a higher debt base than the last cycle. Each cycle leaves the world MORE dollar-dependent than before, not less.
This is why every dedollarization prediction fails. The mechanism that's supposed to kill the dollar — dollar weakness — is the mechanism that creates more dollar dependency. The trap is structural.
Bolivia tried. Venezuela tried. Iran is trying right now. Iran allowed to sell oil in dollars by US Treasury waiver through August 21 — not because the US offered relief, but because CNY couldn't stop the collapse. GDP -6.1%. Inflation 70%. Rial -30% even while dark CNY trades ran. A 1 million Rial banknote was issued weeks into the conflict. The central bank printing the largest denomination note in its history is the physical manifestation of currency failure. Venezuela ran the same sequence. Zimbabwe ran it. Turkey is running a slower version of it now.
Brazil is now moving to issue $740M in panda bonds — yuan-denominated debt. The first Latin American country to do so. Filed the same week its banks were calling Mexico for compliance guidance on US dollar AML requirements following PCC/CV terrorist designations. Brazil is trying to run both tracks simultaneously — yuan diversification and dollar compliance integration. That dual track is not sustainable. October elections will determine which one wins. The sequence is already loading.
THE BAND CONCEPT AND WHERE WE ARE NOW
Brent mentioned a concept from his new 80-page research paper: the dollar index trades within a band. When it stays within the band, the global system can manage both carry trades. When it breaks outside the band in either direction, carry trade unwinds begin.
DXY at 101.24 today. Up from the ~96 trough. Breaking back above 50-day, 100-day, and 200-day moving averages simultaneously. Banks that were calling for 80s and 90s are now scrambling to revise. BofA just turned more dollar bullish — EUR/USD 1.12 Q3, 1.15 end 2026. Direction right. Magnitude almost certainly wrong.
The mechanism taking the dollar higher isn't the one most analysts are modeling. They're anchoring to Fed rate differentials. Warsh holds at 3.5-3.75%, shifts to neutral, markets price one hike. BofA calls three hikes then reverses. The consensus is fighting the last war.
The dollar is going higher because:
The AI leverage unwind is removing the suppression weight from the dollar trampoline. Trillions in dollar-denominated leverage was used to fund long tech, long crypto, long commodity positions — all of which were simultaneously Treasury shorts. As that unwind proceeds, Treasury shorts get squeezed, bonds rally, dollar rises. Without a single Fed hike.
EM treasury depletion is forcing dollar buying. Countries with 4 billion people combined have had their sovereign reserves drained through commodity import costs, debt service, and capital flight. They need dollars. They sell whatever they have — gold, local assets, commodity positions — to get them.
The energy architecture is now structurally dollar-enforced. $750B in EU LNG contracts locked at Henry Hub dollar pricing for 15 years. Japan's 7.5M MTPA new contracts dollar-denominated and Henry Hub indexed. South Korea $100B. Every molecule of US LNG that replaces Hormuz-disrupted supply is a new dollar demand obligation that cannot be renegotiated.
THE BOTTOM LINE
Brent Johnson has been right about the mechanics for years. The people who dismissed him are now watching gold at $3,900 and silver below $58 and trying to explain why their one-way trade went the wrong way.
The debasement thesis is correct. Hard assets win over full cycles. Nobody serious disputes that.
But the path is determined by the dollar. And the dollar is determined by the mechanics of a system that is far more robust than most people understand.
The dual carry trade means one of the two is always going against the rest of the world. The dollarization paradox means dollar weakness creates more dollar dependency, not less. The liquidity valve means commodity prices don't go up in a straight line — stairway up, elevator down.
The destination of the debasement trade is still correct.
The path just went through here first.
Understand the mechanics or get destroyed by them.
The Secret Mechanics behind the Debasement Trade Unwind... youtu.be/KQdKsc7fsXM?si=gyMC… via @YouTube

Correct — Hormuz hit everyone. But Japan’s import collapse has a second layer: JPY at 161, up 58% over 10 years, on dollar-denominated energy contracts. Every barrel costs 58% more in yen than a decade ago before Hormuz closed. China’s drop is supply shock. Japan’s is supply shock plus structural currency compression.
The story that China capped oil prices by reducing its imports is just more nonsense from the $200 oil crowd that seeks to explain away its awful forecast. Japan's imports fell by more than China's. Newsflash: the SoH was closed. Everyone's imports fell.
robinjbrooks.substack.com/p/…

Two deflationary shocks converging simultaneously — oil and Warsh. Breakevens collapsing while real yields surge. The next step in the sequence: note vol rises, bond vol compresses, curve flattens through the short end. The deflation trade is Bond Gravity loading from the real rate side.
Welcome to the "Deflation Trade." Markets are trading two shocks: (i) the rapid fall in oil prices, a deflationary impulse; and (ii) a hawkish shift in the Fed's reaction function, which is also deflationary. Real rates are up, which sends gold tumbling...
robinjbrooks.substack.com/p/…

World Dollar Value | Sovereign Risk | Macro Intel retweeted
$3T in sidelined US housing demand waiting for rate compression. 30Y near 3-month lows. $165B in mandatory institutional bond buying hitting quarter end now. And tonight Congress passes the most significant housing supply legislation in 36 years — 358-32, 85-5, zoning reform, permitting streamlined. Demand side and supply side loading simultaneously. When the 30Y completes the move the $400T mortgage wave resonates and this legislation is already waiting on the other side. Coincidence? @PolarityRadio

Breaking News: Congress overwhelmingly passed the most significant piece of housing legislation in 36 years, in a rare bipartisan feat. nyti.ms/4aPVX3v

Banking stress to Pentagon coalition invite in under 5 months. The Colombia sequence: Bancolombia February → Pimco $2B → De la Espriella wins → Pentagon “Coalition of the Americas against the Cartels” within 48 hours. Security integration is the final architecture layer. Brazil’s banks are already calling Mexico for compliance guidance. October elections coming. The sequence is already running next door.

$165B in institutional equity-to-bond rotation hitting this week. Mechanical. Mandatory. Happens regardless of Fed path.
GPIF $60B. Norges Bank $40B. US defined benefit pensions $55B. SNB $25B.
30Y already near 3-month lows. VXTLT down 38% past year. Curve flattening across every tenor.
The quarter-end rebalancing doesn’t care about BofA’s three-hike call. It doesn’t wait for PCE. It executes by mandate.
$165B in forced duration buying into a bond market already loading the sequence. This week.

We are about to experience is massive end-of-Q2 rebalancing period:
Institutional investors are estimated to sell up to $165 billion in equities and purchase an equivalent amount of bonds by quarter-end, the highest in at least 4 years, according to JPMorgan.
Japan's Government Pension Investment Fund (GPIF), with ~$1.9 trillion in assets, is estimated to sell ~$60 billion in equities, while Norway's Norges Bank, managing a ~$2.1 trillion sovereign wealth fund, is expected to sell ~$40 billion.
At the same time, US defined benefit pension funds, managing ~$9.6 trillion in assets, could account for another ~$55 billion in equity sales.
The Swiss National Bank is estimated to sell ~$25 billion, though this figure could fall to ~$8 billion if its equity allocation rises to 30% from the current 28%.
Meanwhile, balanced mutual funds, managing ~$4.0 trillion in assets, are estimated to purchase ~$15 billion in equities.
A massive quarter-end rebalancing wave is about to hit global markets.

There's a new version of this post
The Monroe Doctrine 2.0 map as of June 21, 2026.
🇦🇷 Argentina — Milei 2023
🇺🇾 Uruguay — 2024
🇻🇪 Venezuela — Maduro captured January 2026
🇨🇱 Chile — 2025
🇧🇴 Bolivia — Revolution May 2026, IMF program running
🇭🇳 Honduras — 2025
🇨🇴 Colombia — De la Espriella wins today
Every flip followed the same sequence. Banking stress first. Economic restructuring second. Political resolution third. Capital entry fourth.
Brazil is the last domino. PCC and Comando Vermelho designated foreign terrorist organizations May 28. October elections coming.
The hemisphere isn’t being reshaped by ideology. It’s being reshaped by capital flows, energy architecture, and the sequencing of economic stress.
The map doesn’t lie.


World Dollar Value | Sovereign Risk | Macro Intel retweeted
The strategic read on today’s Ras Laffan explosion: Qatar declared force majeure to China, South Korea, Italy and Belgium. 17% of capacity offline for years. Restart was already fragile — end of August at earliest. Today sets that back further. Asia and Europe were watching Qatar before signing more US LNG contracts. Every additional day of Qatari uncertainty is another day US Gulf Coast terminals are the only reliable supply architecture on earth
The Colombia sequence is complete.
February 2026: Bancolombia showed banking stress — 50 days before S&P acted.
April 2026: Pimco put $2B into Colombian local debt ahead of the first round.
June 18: Banking profits +20% YoY. Oil exports at highest since July 2022.
June 21: De la Espriella wins.
The sequence: banking stress first. Capital entry second. Political resolution third.
The data leads the headline by months. Every time.
This is what the terminal tracks.
September 29, 2025 — David Levenson (@PolarityRadio): “The NOB is flattening. 5/10 flattening. 5/30 flattening. 2/30 flattening. 2/10 flattening. This is curve deflation. Don’t ignore it.”
Same day: “The deflation of mortgages and treasuries and the yield curve are going to destroy a lot of money and flow capital from tech outwards.”
That was nine months ago. Before Warsh was chair. Before the MOU. Before the ceasefire.
The 30Y-2Y has since compressed from 140bp to 70bp. The long end refused to sell off despite Warsh explicitly signaling financial conditions are too loose and yields should rise. The market heard him. Disagreed. Immediately and decisively.
This isn’t the market misreading the Fed. It’s the bond market nine months into a sequence that was already mapped before the inputs changed.
The mechanism: the curve isn’t flattening because of policy — it’s flattening despite policy. The Fed can’t ease more than already priced without counterproductive effects. The curve knows this. It’s pricing the destination, not the journey.
2-year breakevens collapsing. VXTLT down 38%. 7Y-5Y through its 200 week moving average. 30Y at 3-month lows. Every dimension confirming the same sequence simultaneously.
Bond Gravity doesn’t wait for policy acknowledgment. It loads in the vol. It loads in the curve. The market isn’t misreading Warsh — it’s nine months ahead of him.
Levenson called it September 29. The chart you posted today is the confirmation.
The one thing Kevin Warsh said on Wednesday that gave a clue to his view on policy is that financial conditions look too loose for the stock market. That means long-term yields should rise, but markets gave him the opposite: a massive bear flattening...
robinjbrooks.substack.com/p/…

.@SantiagoAuFund great breakdown of Iran’s cost of victory this week.
Brent is right that in the court of public opinion, Iran won. The IRGC survived. They kept some uranium. They forced the world’s largest military to pause. On optics, that reads as a victory.
But optics and outcomes are two different scoreboards.
What actually happened to the Iranian state:
Supreme leader eliminated. Entire command tier gone — IRGC commander, defense minister, navy commander, intelligence minister, chief of general staff. Brent compared it to taking out Trump and his entire cabinet simultaneously. That’s not winning a round. That’s having your corner team removed from the fight while the clock is still running.
The military cost:
🪖 90% of the navy destroyed
🪖 85% of the missile, drone, and naval industrial base gone — the ability to rebuild is what was destroyed, not just the inventory
🪖 80% of missile launchers eliminated (480 → 100)
🪖 Missiles: 2,500 → 1,000
🪖 75% of nuclear centrifuges lost
🪖 3,000-10,000 military deaths
The economic cost:
💵 GDP -6.1%
💵 Inflation 70%
💵 Rial -30%
💵 Oil exports recovering from -89%
💵 Petrochemical industry -85%
💵 Steel production -70%
💵 $270B total rebuild cost
💵 Some of this takes decades to replace. You cannot replace the people.
The “victory” terms:
The $6B frozen funds: phased release, contingent on compliance, contingent on Hormuz reopening, oil export waiver lasts 60 days only. Every dollar Iran receives is conditional on behavior Washington approves. That’s not a payment. That’s a compliance mechanism.
The $300B reconstruction fund: Western firms rebuild Iran on Washington’s terms. The reconstruction of Iran will be financed, designed, built, and controlled by the same side that destroyed it. That’s not a victory condition. That’s an occupation by contract.
The 60-day MOU: 14 points unresolved. 60% of highly enriched uranium still retained. Brent himself said he doesn’t expect this MOU to last. If it collapses, Iran re-enters the next round with no supreme leader, no command tier, 90% of its navy gone, 85% of its industrial base destroyed, and $270B in damage unrepaired. That is not a strong position for round two.
The court of public opinion vs the court of contract law:
Public opinion doesn’t pay for $270B in reconstruction. Public opinion doesn’t restore 75% of your centrifuges. Public opinion doesn’t unfreeze the funds — compliance does.
Iran kept its sovereignty in name. The terms of that sovereignty are now set by the compliance architecture Washington built into every clause of the deal.
My conclusion:
The IRGC survived. That’s real. Iran kept uranium. That’s real. They forced a pause. That’s real.
But surviving isn’t winning when the terms of your survival are written by the other side.
While Iran was fighting to survive — the United States was building:
⚡ $750B Turnberry LNG deal — Europe locked into 15-year US contracts signed before the first missile flew
⚡ US world’s largest LNG exporter — 15 Bcf/day, forecast 18.1 Bcf/day by 2027
⚡ Japan $550B + South Korea $100B — major Asian importers locked into Henry Hub indexed contracts
⚡ 36.6 gigawatts of gas-powered data centers under construction — AI creating permanent second demand anchor for the same commodity
⚡ US crude exports 13.6M bbl/day during the closure — second highest on record
Iran closed the Strait for 110 days. The US used those 110 days to lock every major energy importer into 15-year dollar-denominated contracts with no exit clause.
That’s not losing the round. That’s winning the next decade.
How much did it Cost for Iran to win its Political Victory...? youtu.be/PP5OX48tAL4?is=JlGM… via @YouTube

World Dollar Value | Sovereign Risk | Macro Intel retweeted
@SantiagoAuFund Every dollar is conditional. Phased release. Hormuz reopening required. 60-day oil export window. “Financial incentive” is what you call a compliance mechanism when you don’t want to say leash. GDP -6.1%, inflation 68.9%. Iran needs every dollar back. That need is the enforcement architecture. The blockade didn’t end — it converted.
World Dollar Value | Sovereign Risk | Macro Intel retweeted
Spot oil priced the MOU in hours. The production forecast shows why that was premature — Iran exits 2026 at ~1.35mb/d, well below the 3.2mb/d it entered the year at. Sanctioned tanker fleet frozen. Export infrastructure recovering from -89%. The compliance leash on the $6B fund release adds another variable. Physical recovery is measured in quarters, not sessions.
World Dollar Value | Sovereign Risk | Macro Intel retweeted
+3.2% since the start of the “foolish misadventure.” The Band doesn’t need permission. $14.5T in external dollar liabilities, every energy invoice dollar-denominated, every EM restructuring clearing in dollars. The rejection is on the chart. So is the result.
Removing forward guidance created a vacuum. Markets filled it with hawkish assumptions — the default when uncertainty is high. The bond market immediately disagreed. 2Y rejected the hawk spike Wednesday. 30Y at 3-month lows. VXTLT down 38% past year. Two markets, two readings. The bond market has more information than the rates market does right now.
Kevin Warsh refused to give any kind of forward guidance on Wednesday, so - in the absence of any guidance - markets did the predictable thing and priced a much more hawkish Fed (orange). I don't think that's right and this Q&A on Warsh highlights why...
robinjbrooks.substack.com/p/…

Diversion to “random places” is the proof the primary tool worked — and the mechanism by which the pressure spreads. China redirecting at distressed prices floods EM markets. Zimbabwe +130% import surge. Colombia 35% footwear tariff response. The Western tool is effective. The diversion is the secondary transmission — EM economies absorbing Chinese export pressure they didn’t create and can’t easily defend against.
Western defeatism is a scourge. Everything we've done - from the US blockade of Iran to China tariffs and Russia sanctions - has been highly effective. Just look at how China is having to divert exports to all kinds of random places due to US tariffs...
robinjbrooks.substack.com/p/…

Built pipeline by pipeline over 20 years. Then Hormuz closed and every buyer learned simultaneously that there was only one emergency valve. $750B EU deal, $550B Japan, $100B South Korea — all signed into those same terminals. The infrastructure was always the weapon. The war just proved it publicly.

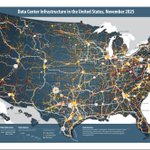
Everyone talks about US shale production.
Nobody talks about what makes it actually work.
This map.
This infrastructure didn't exist 20 years ago.
America built it from scratch during the shale revolution quietly, pipeline by pipeline, fractionator by fractionator until it became the most sophisticated NGL network on the planet.
The terminals at the bottom of that map?
They've been running flat out.
US propane to Japan.
US butane to South Korea.
US ethane to European petrochemical plants.
The shale revolution wasn't just about oil and gas prices.
It was about building the infrastructure to become the world's energy backstop.
When any chokepoint closes anywhere on Earth, those Gulf Coast terminals become the world's emergency valve.
That's the real American energy weapon.
Full analysis in my latest article.
Link in the comments 👇

Military survival confirmed. Economic survival still contingent. GDP -6.1%, inflation 68.9%, $300B reconstruction fund tied to compliance, frozen funds not yet released. The strike ended. The financial kill is still active. Brent’s right — the political realities that flow from here are unresolved. Survival is just the opening position for what comes next.
