

Macro intelligence for investors, entrepreneurs & high-performance thinkers. ProfitMindset Intelligence™ — built for the next cycle.
Africa
Joined June 2022
- Tweets6.8K
- Following5.5K
- Followers5.7K
- Likes14.7K




Pinned Tweet
THE SKILL THAT NEVER GREW
You worked for five years.
But did your earning ability grow for five years?
In a fast-changing economy, years of experience alone may not protect your standard of living.
If prices keep learning how to rise, your skills must keep learning how to earn.
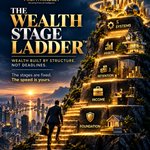
THE WEALTH STAGE LADDER™
A stage-based framework for building financial capacity without forcing wealth onto an artificial timeline.

The gap is often not another piece of financial information.
It is knowing what needs strengthening next.
Foundation → Income → Retention → Assets → Systems
You do not need to race someone else's calendar.
You need to make the stage beneath you strong enough to carry the next one.
Markets involve risk and returns are never guaranteed. Use this framework as education, then adapt it to your own circumstances.
Strengthen it. Clear it. Then climb.
The stages are fixed. The speed is yours.
ProfitMindset™ | Wealth built by structure, not deadlines.
Prepare rules before disruption arrives.
Income falls?
Protect essential liquidity and reassess discretionary commitments.
Markets fall?
Do not automatically abandon a long-term investment plan because prices declined. Reassess whether your circumstances, time horizon or investment thesis changed.
Job disappears?
Liquidity exists partly to reduce the need to sell long-term assets under pressure.
Good financial rules are easiest to design before emotion is involved.
If a controllable metric stalls for three months, diagnose the cause.
But do not mistake normal market volatility for personal financial failure.
A portfolio can fall while you are still:
Investing consistently.
Reducing expensive debt.
Increasing income.
Building liquidity.
Accumulating ownership.
Measure the process as well as the price.
Build a monthly financial dashboard.
Review these on the same date every month:
→ Income
→ Savings and investment rate
→ Essential-expense liquidity
→ High-cost debt
→ Amount invested
→ Investment assets
→ Income generated beyond primary employment
Do not merely ask:
“Did I make money this month?”
Ask:
“Did my financial structure become stronger?”
Your checkpoints should therefore be stage-based:
Foundation: spending understood, expensive debt being addressed, initial liquidity established.
Income: marketable capability producing measurable economic opportunities.
Retention: part of income consistently converted into capital.
Assets: liquidity strengthening while productive assets accumulate.
Systems: income begins extending beyond direct labour.
Progress becomes measurable without pretending everyone starts from the same position.
Why doesn't The Wealth Stage Ladder™ use fixed months?
Because starting positions differ.
Someone with stable income, valuable skills, low obligations and little expensive debt may progress quickly.
Someone rebuilding from debt, supporting dependants or dealing with unstable income may need considerably longer.
That is not failure.
The stages are fixed. The speed is yours.
And validate before scaling.
Do not spend months building something nobody has agreed to buy.
Find the problem.
Test the offer.
Get early customers.
Understand why they paid.
Improve the solution.
Then scale carefully.
Demand first. Scale second.
STAGE 5: SYSTEMS
Eventually, ask a different question:
Can some of my income continue without every unit depending directly on another hour of my labour?
Possible paths include:
→ Productised services
→ Specialist agencies
→ Software
→ Intellectual property
→ Licensing
→ Digital products
→ Subscription businesses
→ Other scalable systems
Start from a problem people already pay to solve.
This is not a get-rich-quick framework.
Long-term investing is largely about repeatedly directing capital towards productive ownership, managing risk and allowing time to do work that excitement cannot.
Markets will rise.
Markets will fall.
Some businesses will disappoint.
Some investments will outperform.
Diversification exists partly because nobody knows every winner in advance.
Durability. Diversification. Discipline. Time.
The long-term mindset matters more than excitement.
A broad index fund does not need tomorrow's hottest stock to work.
A bond does not need to become a ten-bagger.
A dividend-paying company does not need to dominate social media.
A utility does not need to become fashionable.
Different assets perform different jobs: liquidity, income, diversification, capital preservation and long-term growth.
Do not demand the same job from every asset you own.
Then study the company.
Look for:
→ Sustainable cash flow
→ Manageable debt
→ Durable competitive advantages
→ Sensible valuation
→ Ability to survive difficult economic periods
→ Responsible capital allocation
→ A consistent dividend record where income is part of your strategy
Five or ten years of dividends can provide useful historical evidence, but dividends are never guaranteed.
A necessary industry does not automatically make every company inside it a good investment.
If you invest in individual stocks, think beyond what is fashionable today.
Study quality businesses connected to needs society is likely to keep paying for:
→ Agriculture and food
→ Pharmaceuticals, medicine and healthcare
→ Utilities, electricity and power infrastructure
→ Oil, gas and broader energy
→ Banking and financial infrastructure
→ Industrial production and physical infrastructure
→ Telecommunications
→ Semiconductors and durable technology infrastructure
These industries serve needs embedded deeply in modern economies.
But industry relevance is only the beginning.
STAGE 4: ASSETS
This is where retained income begins becoming financial defence and ownership.
Depending on your circumstances, build liquidity while gradually allocating capital across appropriate vehicles:
→ High-yield savings or money-market instruments for accessible cash
→ Treasury bills and high-quality bonds for defensive capital and income
→ Broad index funds and ETFs for diversified long-term ownership
→ REITs for listed property exposure
→ Individual stocks for investors prepared to research businesses
The objective is not quick riches.
It is to make today's income capable of creating value years after it was earned.
Consider the mathematics.
Earn $3,000 and retain 10%:
$300/month
Earn $6,000 and retain 40%:
$2,400/month
Income doubled.
Monthly capital formation increased 8×.
Higher income creates capacity.
Retention determines how much of that capacity survives long enough to become capital.
STAGE 3: RETENTION
Higher income does not automatically create wealth.
If every increase in income becomes an increase in lifestyle, earning power can rise while financial capacity barely moves.
Use a retention rule:
When income rises, direct a meaningful portion of the increase towards savings, investing or strengthening your financial position before lifestyle absorbs everything.
Automate where practical.
Then build evidence.
Complete real projects.
Create case studies.
Solve actual problems.
Apply for stronger roles, pitch clients or negotiate opportunities where appropriate.
A certificate proves you studied something.
Economic evidence shows whether someone will pay for what you can do.
Stage 2 strengthens when capability begins producing measurable earning opportunities.
STAGE 2: INCOME
Do not choose a skill simply because it is trending.
Check whether the market is actually paying for it.
Study at least 20 relevant job, contract or freelance listings.
Ask:
→ Is demand visible?
→ Can I demonstrate the skill?
→ Can it increase my earning power?
→ Can it eventually become a service, product or system?
→ Can AI strengthen my productivity within this field?
Demand first. Learning second.
STAGE 1: FOUNDATION
Track your spending for 30 days.
Remove recurring expenses that no longer provide value.
Prioritise expensive consumer debt.
Build an initial emergency buffer around your essential expenses.
Then identify the skill you intend to monetise.
Before wealth can compound, financial fragility has to decrease.
The 5 stages of The Wealth Stage Ladder™:
Stage 1: Foundation
Stage 2: Income
Stage 3: Retention
Stage 4: Assets
Stage 5: Systems
(FIRAS)
You climb when the current stage can carry your weight, not because a calendar tells you to move.
The stages are fixed. The speed is yours.
Most wealth content sells you a deadline.
Get rich in a year.
Get rich in five years.
But financial progress does not run neatly on a calendar. It moves through stages.
Some people may clear a stage in months. Others may need years.
What matters is whether the stage beneath you is strong enough to support the next one.