

Helping bond investors find what's rich or cheap, and why. Macro, rates & MBS today. Munis, ABS & corporates next.
San Francisco Bay Area
Joined September 2026
- Tweets82
- Following90
- Followers60
- Likes236
Pinned Tweet
We're live!

Today, I'm excited to bring @OasiveAI out of stealth and announce that we're backed by @ycombinator!
Oasive helps bond investors find better bonds to buy.
Uncover opportunities you might otherwise miss, compare investments and test the risks before putting on a trade.
Which Treasury maturities look cheap? Is there a curve trade worth putting on? Macro and Rates Research helps you explore both. In mortgage-backed securities (MBS), compare pools and see how changes in rates and prepayments affect your portfolio.
Our AI analysts bring the research and proprietary models together, so you can go from idea to decision in minutes.
Thank you to @kul and @garrytan for taking a chance on me and believing in @OasiveAI!
Start your Macro and Rates Research free trial or request an MBS demo: oasive.ai/join
Here's what you can do 👇
Oasive (YC F26) retweeted

Builder sentiment hit a 14y low... and more builders are cutting prices as buyer traffic falls.
@OasiveAI’s breakdown of October’s NAHB data shows > 43% of builders cutting prices, up from 38%
> 65% offering incentives
> confidence fell to 29, lowest since June 2012
> buyer traffic down 5 points to 18
The outlook is getting worse too: sales expectations fell to 32 from 54 just a year ago.
Mortgage rates rose from 6.65% in August to 7.40% so even even listing prices are lower, buyers still have to pay the monthly payment

Oasive (YC F26) retweeted
Bonds were a useful hedge to stocks this past week. A reliable hedge though? Still too soon to say.
Stock-bond correlation is still +0.34 over 60 days, almost identical to its 1y norm of +0.33 (they still tend to move together)
Last week’s biggest surprises vs the @OasiveAI cross-asset performance model:
> Oil: 10 ppts stronger than expected
> Rate vol: 10 points higher than expected
> Nasdaq: 0.9 ppt weaker than expected

Oasive (YC F26) retweeted
What happened last week in the market?
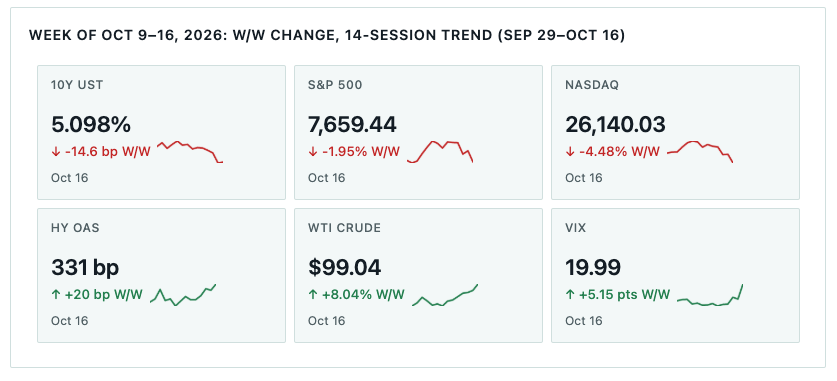
AI debt fears hit tech. Oil kept climbing. A rough week for markets!
> Nasdaq -4.5% (worst drop since June), S&P 500 -2%, VIX hit 20
> WTI oil +8% on middle east tensions
> Treasury yields fell: 10y -15bp, 30y -16bp and HY spreads widened +20bp
> Energy pushed inflation higher. Markets still pricing 85% chance of a Fed hike by December with no pushback from Warsh before the blackout
Get your market update in your mailbox daily with @OasiveAI!
Oasive (YC F26) retweeted
US manufacturing had a pretty modest month in September despite the headline beat.
Digging more into the breakdown with @OasiveAI:
> utilities jumped 3.5%
> manufacturing rose 0.3% (matching expectations)
> motor vehicles and parts fell 3.0%, their 3rd consecutive monthly decline
Outside autos, factory output grew 0.5% so there’s some encouraging growth here! But the jump in utilities helped lift the headline, while car production kept falling.
Encouraging growth, with some clear weak spots.

High-tech production is booming. The rest of manufacturing is growing much more slowly though.
September industrial production rose 0.7% m/m, beating the 0.4% consensus in Friday’s release. Looking deeper with @OasiveAI, the growth split is interesting:
> selected high-tech industries: +17.5% y/y
> semiconductors and related components: +19.9%
> manufacturing excl. high tech: just +0.7%
Meanwhile, industry was using 77% of its capacity, below the 79% long-run average.
Chip production is booming, but the rest of manufacturing is barely growing. That’s why the high-tech numbers alone can give an overly strong impression of how US factories are doing.

Oasive (YC F26) retweeted
High-tech production is booming. The rest of manufacturing is growing much more slowly though.
September industrial production rose 0.7% m/m, beating the 0.4% consensus in Friday’s release. Looking deeper with @OasiveAI, the growth split is interesting:
> selected high-tech industries: +17.5% y/y
> semiconductors and related components: +19.9%
> manufacturing excl. high tech: just +0.7%
Meanwhile, industry was using 77% of its capacity, below the 79% long-run average.
Chip production is booming, but the rest of manufacturing is barely growing. That’s why the high-tech numbers alone can give an overly strong impression of how US factories are doing.
Oasive (YC F26) retweeted
Last week’s auction stress was at the front-end, not the long-end.
The $22B 30y reopening cleared at 5.618% with a 2.54x bid-to-cover, and dealers took only 6.8% of competitive awards.
At Thursday’s $105B 8w bill sale, cover fell to 2.26x and dealers absorbed 47.4%. The difference suggests buyers were comfortable taking duration at 5.6%, while heavy front-end supply met much weaker non-dealer demand.
From @OasiveAI's Friday morning auction recap!

Oasive (YC F26) retweeted
From Sep 17 to Oct 15, the 30y mortgage rate climbed 45 bp, from 6.95% to 7.40%. The 10y Treasury yield rose just 16 bp, from 4.94% to 5.10%.
The gap widened by 29 bp to 2.3 percentage points. For homebuyers, borrowing became more expensive than the Treasury move alone would suggest. Even if Treasury yields stabilize, higher mortgage rates could keep home sales slow.
For investors, that raises a different question: where are you getting paid enough for the risk?
That’s what I’m building @OasiveAI to help answer: comparing value across fixed-income markets so investors can make better-informed decisions.

Oasive (YC F26) retweeted
@OasiveAI just released its Foreign Treasury Buyers report!
Foreign investors bought a net $109B of notes and bonds in August, the largest long-term inflow in 13 months, while running down $48B of bills.
Foreign governments & central banks sold $42B of bills but bought $18B of notes and bonds. Their share fell to a low of 40%. Japan and China’s reported Treasury holdings fell by a combined $225B over the 12m through August. But the mix is different: Japan’s retreat was concentrated in bills, while China sold a net $58B of longer duration bonds over that period.
The marginal foreign buyer is now private. September’s data (due Nov 18) will test whether that demand held up through a 54 bp rise in the 10y yield.
DM me if you want to see the full report!

Oasive (YC F26) retweeted
The hot PPI print yesterday didn't increase the odds of Fed hikes. Actually the bond rally took some out.
In our @OasiveAI analysis today: October 28 hike odds fell from 34% to 25%, close to the 22% priced before CPI. The front end still carries a hike premium the long end is shedding: the 2Y fell half as much as the 10Y.
A hawkish Warsh or data signal before the October 27-28 meeting would hit the 2Y first. Another risk-off day helps duration more than the front end.

Oasive (YC F26) retweeted
Treasuries rallied through a hot PPI. The 10Y fell 10.1bp to 5.09% and 2s10s flattened 4bp to 33bp, even though September producer prices rose 1.3% m/m. Demand for safety after an AI-led tech scare mattered more than the inflation print.
Equities rotated rather than sold off: the S&P 500 rose 0.3%, led by health care, materials and homebuilders, while tech and energy fell.
The dollar fell 0.5% and gold rose 1.6%. Rate volatility rose during the rally: the MOVE index gained 3.4 points when its usual relationship with rates and equities pointed to a drop.
From @OasiveAI's daily macro update delivered to your mailbox every morning!

Oasive (YC F26) retweeted
I’ll be in Boston next week October 19–20 for the FT Future of Asset Management North America!
I’d love to meet others working in fixed income, especially agency MBS, munis, and rates.
If you’ll be there, let me know. Would be great to connect in person!

Check out Oasive for a breakdown of all macro data!
We just released our @OasiveAI retail sales report. here are the takeaways:
> Headline was +0.8% but gas-station sales jumped 6.4% and accounted for 71% of the monthly dollar increase. If we exclude gas, sales rose just 0.2%
> The components were mixed: restaurant and bar sales rose 1.1%, auto-dealer sales edged up 0.2%, and building-material sales fell 0.6%
> The control group, which excludes autos, gas, building materials and restaurants, grew just 0.1 % after 1.2% in August. And after a broad inflation adjustment, total retail sales barely increased
Consumers are still spending, but this looks more like a slowdown after a strong August than a fresh burst of demand.

Oasive (YC F26) retweeted
We just released our @OasiveAI retail sales report. here are the takeaways:
> Headline was +0.8% but gas-station sales jumped 6.4% and accounted for 71% of the monthly dollar increase. If we exclude gas, sales rose just 0.2%
> The components were mixed: restaurant and bar sales rose 1.1%, auto-dealer sales edged up 0.2%, and building-material sales fell 0.6%
> The control group, which excludes autos, gas, building materials and restaurants, grew just 0.1 % after 1.2% in August. And after a broad inflation adjustment, total retail sales barely increased
Consumers are still spending, but this looks more like a slowdown after a strong August than a fresh burst of demand.
Drop a full dealer offering sheet into Oasive!
By request, you can now copy and paste an agency MBS dealer offer sheet directly into @OasiveAI in any format, and price the pools in just a few minutes and figure out what is attractive.
Run scenario analysis, then add the pools to your portfolio or build a hypothetical portfolio to see how they would change your risk before you trade.
Here’s a quick demo, let me know what you think! 👇
Oasive (YC F26) retweeted
Last inflation takeaway for the day: used cars and car insurance are cheaper than a year ago, but the recent price drops have stalled.
Used-car prices rose for 3 straight months, up about 1.4% from July through September. Car insurance was nearly unchanged in September after getting cheaper in August.
That means these costs stopped helping bring inflation down in September.
There’s still some good news: the prices dealers pay for used cars (Manheim’s wholesale used-car index) fell in September. If those savings reach buyers, used-car prices could ease again.

Shelter inflation picked up again in September, rising 0.4% after 0.3% in August and 0.1% in July. OER rose 0.3%.
Hotel prices explain a lot of that summer-to-September swing. Lodging fell 2.3% in June and 2.8% in July, holding down the shelter readings, before rebounding 2.4% in August and 2.0% in September.
Shelter moves more slowly and carries substantial weight in core CPI. But @OasiveAI's analysis showed that part of the shelter rebound is coming from volatile hotel prices, so it’s too early to call this a sustained pickup in rents inflation.
Though it will definitely keep pressure on rates in the near-term!

Oasive (YC F26) retweeted
Shelter inflation picked up again in September, rising 0.4% after 0.3% in August and 0.1% in July. OER rose 0.3%.
Hotel prices explain a lot of that summer-to-September swing. Lodging fell 2.3% in June and 2.8% in July, holding down the shelter readings, before rebounding 2.4% in August and 2.0% in September.
Shelter moves more slowly and carries substantial weight in core CPI. But @OasiveAI's analysis showed that part of the shelter rebound is coming from volatile hotel prices, so it’s too early to call this a sustained pickup in rents inflation.
Though it will definitely keep pressure on rates in the near-term!
We analyzed the recent CPI prints and impact on Fed policy path in our latest @OasiveAI piece:
Core CPI beat consensus, rising 0.335% m/m against a 0.2% median and lifting core YoY to 2.56%. Energy drove the 0.65% headline: gasoline rose 9.1%, and 3.74% YoY topped the 3.6% call. Core strength was broad, with shelter up 0.39% and airfares, lodging and used cars firm. 3m core is back to 3.4%.
The front end repriced an October hike, with odds up from 22% to between 39% and 54%.

Oasive (YC F26) retweeted
We analyzed the recent CPI prints and impact on Fed policy path in our latest @OasiveAI piece:
Core CPI beat consensus, rising 0.335% m/m against a 0.2% median and lifting core YoY to 2.56%. Energy drove the 0.65% headline: gasoline rose 9.1%, and 3.74% YoY topped the 3.6% call. Core strength was broad, with shelter up 0.39% and airfares, lodging and used cars firm. 3m core is back to 3.4%.
The front end repriced an October hike, with odds up from 22% to between 39% and 54%.
Oasive (YC F26) retweeted

Today we’re launching Papaya (YC F26)!
Papaya continuously improves the quality of your production AI agents.
When an agent doesn’t do what it is asked, or takes too long, customers get frustrated. As every company gets access to the same intelligence, agent quality becomes the competitive advantage.
Papaya learns how customers use your agent, pinpoints where they run into issues, then opens PRs to fix them and tracks the impact.
Built with @macyymay and @vpfaiz
Oasive (YC F26) retweeted
Housing did not get the same relief as Treasuries this past week.
From Sep 24 to Oct 8, the 30y mortgage rate rose 37 bp while the 10y Treasury added just 4 bp, widening the mortgage spread by 33 bp to 218 bp.
Affordability still continues to erode.
Chart from @OasiveAI chat platform
