

Data, insight, and analytics for forecasting, modelling, and trading European energy.
Europe
Joined April 2010
- Tweets8.2K
- Following369
- Followers9.7K
- Likes819





Set a price level. Get an alert when the market reaches it. See why it moved.
🔔 In Montel Markets, you choose the contract and the price level that matter to you, such as a hedging trigger or a budget limit. When the market reaches that level, you get an alert.
You can then check the context in the same platform:
📰 Montel News stories on what is moving the market
📈 Price history charts that show when the market was last at this level
The alert, the news and the price history are all in one place.
👉 Start your free trial: eu1.hubs.ly/H0yPlNn0
⚡When should industrial businesses buy electricity, and how can they manage the risks?
Electricity costs are shaped by more than wholesale prices. Generation, grid constraints, taxes and network charges all affect what businesses pay. And because gas-fired power plants often set the wholesale price, changes in gas markets can also have a significant impact.
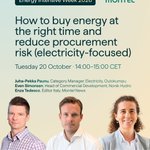
Tomorrow, Even Simonsen, Head of Commercial Development at Norsk Hydro, and Juha-Pekka Paunu of Outokumpu will discuss how industrial buyers can approach procurement in this complex market.
Enza Tedesco, Editor Italy at Montel News, will moderate the session.
🔎 They’ll cover the main risks for electricity buyers, which market indicators to monitor, and procurement strategies that can help manage price exposure and support longer-term planning.
🤝 Delivered in partnership with European Aluminium.
📅 20 October, 14:00–15:00 CET
Free webinar
Register here: eu1.hubs.ly/H0yWhZW0

Autumn arrived this morning.
At 9am, France was importing 420 MW.
Temperatures are finally closer to normal: low from 6 to 8° this week, 19 to 25 October, and high at 14°.
That's 4 to 8 degrees lower in the morning and close to 10 degrees less in the afternoon.
And load reacts. Immediate impact: this morning at 9am the load is at 53.7 GW after minimums at 6°C. Last week same time it was 49.4 GW with minimums at 10°C.
4°C colder, 4.3 GW more. That's the temperature gradient above 5°C.
When we pass below 5° the gradient increases, close to 1.5 GW per degree.
Below 0° it's closer to 2 GW.
How to cope with such a demand increase while all CCGTs were already running fully in morning and evening peaks?
No more exports. From 8:30 to 10am this morning France was importing.
Nuke availability is stuck at 38 GW. From Wednesday it should increase to 41 GW. Without significant change before the end of the month.
As long as nuke is not back, France will couple with Germany in peak hours and remain more expensive during solar (and off peaks).
Yes France above Germany on daily average.
👀💰 Every degree counts now. And it flips the dynamic. Get ready to make money 👍
^CB

Energy Intensive Week starts on Monday! ⚡
In partnership with EUROPEAN ALUMINIUM, we’re bringing together experts from across the energy sector for four free sessions on managing costs and navigating market uncertainty.
📅 Monday, 19 October | 13:00–14:00 CET
How to reduce industrial energy prices and costs in an increasingly volatile market
With Paul Voss of EUROPEAN ALUMINIUM, Cillian O'Donoghue of Eurelectric and Snjólfur Richard Sverrisson of Montel News.
📅 Tuesday, 20 October | 14:00–15:00 CET
How to buy energy at the right time and reduce procurement risk
With Juha-Pekka Paunu of Outokumpu, Even Simonsen of Norsk Hydro and Enza Tedesco of Montel News.
📅 Wednesday, 21 October | 14:00–15:00 CET
How to reduce energy costs through hedging and gas risk management
With Erisa Pasko of Energy Aspects, Wimmel Wick of Montel and Laurence Walker of Montel News.
📅 Thursday, 22 October | 14:00–15:00 CET
How to use PPAs to secure lower-cost and low-carbon electricity
With Josephine Steppat of Montel, Killian Daly of EnergyTag, Nick Bitsios of Metlen and Alina Trabattoni, PhD of Montel News.
Explore the sessions and register here: eu1.hubs.ly/H0yfTbc0


Montel Analytics retweeted

Thank you to everyone who joined us for Benelux Energy Day yesterday.
Across the programme, we explored how geopolitical uncertainty is influencing energy markets, the outlook for European gas prices and carbon, and the plans shaping the Dutch energy system.
We also looked at what growing electricity demand from data centres could mean, the factors driving long-term power prices, and the challenges of investing in volatile markets.
⚡ The afternoon turned to short-term and balancing markets, including Dutch imbalance prices, flexible portfolios and how market participants can respond to volatility.
A big thank you to our speakers, delegates and the Montel team for bringing the Benelux energy community together for a day of discussion and conversation.
📍 Next up: Italian Energy Day in Milan on 29 October.


Montel Analytics retweeted
What is the biggest risk the Benelux energy market is underestimating right now, and why? ⚡
We’ve had an excellent day so far at Benelux Energy Day, discussing the pressures shaping the region’s energy market. We put that question to four speakers, whose answers highlighted how tightly connected the challenges are.
🔌Joanna Pandera PhD, President of Forum Energii, pointed to the pressure on Europe to act quickly, while the policy options available come at a cost.
🔋Erisa Pasko, Lead European Gas Analyst at Energy Aspects, highlighted rising electricity demand from data centres, EVs and heat pumps. Flexible generation is not growing at the same pace as demand, and she said power markets look tight this winter.
🏭 Erika van der Linden, Senior Policy Officer for Dutch Energy System Strategy, focused on the need to invest in new industries as fossil industries decline, and the importance of having those industries in place for Europe’s competitiveness.
🌡️ Fleur Greetham, Director of the Management Consulting Division at AFRY, raised questions about how hotter summers and falling water levels could affect energy infrastructure, from transmission lines and power stations to solar panels.
Which of these risks do you think the market is underestimating most?
📊 Energy markets are more volatile than ever.
More wind and solar. More negative price hours. 15-minute day-ahead products.
That’s more data than any team can work through by hand.
🤖 AI tools can build a forecasting model in minutes.
But can you tell if it’s any good?
A model can look excellent in a backtest because future data leaked into its training. Catching that takes machine learning knowledge, not a better prompt.
🎓 Our new course, Machine Learning for Energy Professionals, teaches you to build, test and explain ML models on real spot and forward curve data.
👩🏫 Taught by:
🔹 sjur westgaard, Professor of Finance at NTNU and Adjunct Professor at Inland Norway University of Applied Sciences
🔹 Morten Risstad, Associate Professor at NTNU
📅 Three live online sessions: 29 October, 5 November and 12 November.
You’ll learn to:
✅ Tell when machine learning beats traditional econometrics
✅ Build forecasting and classification models on EQ market data
✅ Test time series models and spot overfitting or leakage
✅ Explain forecast uncertainty to traders and risk committees
No ML experience needed, just comfort with data and basic statistics. Everything runs in Python in Google Colab, so there’s nothing to install.
⏳ Register here: eu1.hubs.ly/H0z61B20
Battery revenue potential across Europe moved sharply between September 2025 and September 2026. 🔋
For a 2-hour battery, Greece leads our benchmark at €1,755,068 per MW per year in September 2026, ahead of Poland (€978,981) and Spain (€655,228). 📊
Year on year, Belgium grew fastest at +79.31%, followed by Poland (+72.03%) and Greece (+67.18%). Germany fell 42.03%, the steepest decline in the index. 📉
These figures come from a standardised battery index model that applies the same configuration and perfect foresight optimisation in every market. That makes markets directly comparable, so you can see where structural value is created before moving into asset-level modelling.
The Battery section in Montel EQ covers three areas: theoretical revenue across wholesale and balancing markets, top-bottom spread indexes that measure potential arbitrage and volatility, and installed battery capacity tracking that shows competitive pressure. It is built for market screening, revenue analysis, and early-stage investment discussions, not project-level returns.
Learn more about the Battery Index by Montel EQ here:
That’s a wrap on Montel Energy Deep Dives – Benelux.
A fully booked afternoon brought energy professionals together to explore the fast-moving Benelux power market. ⚡
The programme covered short-term forecasting in the Netherlands and Belgium, co-location and hybrid PPAs, battery revenues and the ramp-rate question, as well as the key issues facing the region.
In a conversation with Benjamin Wrigley, he highlighted gas stocks and temperatures as two things to watch this winter. If either stays too low for too long, he expects a bumpy ride.
Thanks to everyone who joined us, and to our speakers and moderator for sharing their expertise.
Couldn’t make it today? Join us tomorrow, 15 October, for Benelux Energy Day: eu1.hubs.ly/H0yFjGR0


Could low gas stocks make for a difficult winter in the Benelux? ⛽
We’ve had an excellent Benelux Deep Dives so far.
We asked Benjamin Wrigley what market participants should prepare for. He pointed to persistently low gas stocks, with the Strait of Hormuz blockage still unresolved.
Temperatures will also be important to watch. If either stocks or temperatures stay low for too long, market conditions could become more challenging. 🌡️
⚡ Italy has recorded its first negative day-ahead power prices in three of its seven market zones, on both quarter-hourly and hourly bases.
📊 Year to date, Italy’s seven zones have logged 772 hours of zero prices. That’s more than double the 291 hours over the same period last year.
📍 Sicily recorded the most zero-price hours, at 179. Central Italy saw the sharpest rise, from 12 hours to 91 in a year. Sardinia was the only zone where these hours fell, down about 20%.
Market participants can bid at negative prices in both the day-ahead and intraday markets, within the technical limits set by EU regulation. In the first half of 2026, the share of volumes offered at negative prices was 9.6% in day-ahead and 2.5% in intraday.
Reported by @montelnews. Alfredo Spalla and Enza Tedesco

German baseload power for Jan-2027 has risen roughly 75% since late spring, from around €115/MWh to just above €200 on the latest trade. Pushed by gas.
The path hasn’t been a straight line. Prices rose steadily through the summer, with a sharp move from late July into August. Mid-September brought a consolidation, with the contract trading in a range of roughly €167 to €195 and sellers pushing back on several sessions. That range has since given way to new highs.
Track this in Montel Markets: eu1.hubs.ly/H0yPlNn0

A sharp move in a power contract can be a warning sign, or it can be normal seasonal behaviour. You only know which once you check.
The questions worth asking are usually the same:
📅 Is this a seasonal pattern, or something new?
⚡ Is gas moving the same way?
🌍 Are neighbouring markets following, or is this a local move?
📈 Is it only the front of the curve, or the whole curve?
Montel Markets answers all four on one chart. Compare power with gas, put countries side by side, set the front quarter against the front year and look back over years of price history.
That way, you can quickly see whether a move matters before you act on it.
👉 Try it with the markets you follow: eu1.hubs.ly/H0yPlNn0
Extreme imbalance prices in France are driven by aFRR.
Last week is a good example.
Tuesday 6 October, 16:30 to 18:00: a first price spike, from 380.48 to 538.69€/MWh.
Thursday 8 October: three spikes, with a low at -727.98€/MWh, as shown in the picture.
Friday 9 October: two peaks, 10:15 to 10:30 and 12:00 to 12:15, at -298.27€/MWh.
The story is the same each time. The last MW of the aFRR curves are expensive. aFRR is pay as cleared.
So the whole activated volume is priced at that extreme.
And the imbalance price spikes.
CRE is currently reviewing the balancing ans service systems rules.
In the last consultation, market participants were clear: the balancing price signal is important and so far is working as expected.
But more important.
That consultation ran alongside a bigger reform: the capacity procurement big bang expected by 2029, and RTE's intervention window cut from 1 hour to 30 minutes.
By design, the shorter window will exclude several slow assets from balancing.
And make RTE more reactive.
Reactive means more aFRR.
And that's where we loop back to last week.
Requested aFRR exceeded the available volume 81 times.
102 quarters out of 672. More than 15% of the week.
Sometimes PICASSO covered the gap.
Sometimes nothing did.
Until September, contracted aFRR moves from 600 MW to 1.5 GW depending on the hour.
France should probably contract more aFRR.
And with the 2029 setup, the need will only grow.
Germany, a market of comparable size, contracts up to 2 GW per hour.
That would be a drastic change in habits.
And a support for aFRR capacity prices and BESS development.
The key question.
More aFRR volume. Higher aFRR energy prices? More spikes?
Maybe. Maybe not.
One thing is certain: an imbalance price more correlated to aFRR energy prices.
And easier to anticipate.
👀💰 The imbalance price is becoming an aFRR price. Forecast one, and you forecast the other. Now you know. 👍
^CB
PS: Surprisingly, RTE's published aFRR needs for this winter (1 October 2026 to 31 March 2027) do not exceed 752 MW upward, from 16:00 to 20:00. Link in the comments.

Gas price movements can affect electricity costs and make planning harder for energy-intensive businesses. What should buyers watch, and how can they approach hedging?
Join us for How to reduce energy costs through hedging and gas risk management (Energy extensive week session) in partnership with EUROPEAN ALUMINIUM.
Erisa Pasko, Lead European Gas Analyst at Energy Aspects, and Wimmel Wick, Quantitative Developer at Montel, will discuss:
• The outlook for European gas markets this winter and beyond
• Key indicators for industrial consumers
• Procurement timing and hedging approaches
Laurence Walker, Deputy Editor-in-Chief at Montel News, will moderate.
📅 21 October, 14:00–15:00 CET
Free webinar
Register here: eu1.hubs.ly/H0z0bMP0

⚡ €9,999/MWh in German intraday on 9 October. A distressed short, or an algo gone wrong?
The 08Q1 quarter-hour (delivery 08:00-08:15) hit the intraday technical price limit several times in the final minute of trading.
📈 The numbers
- €9,999/MWh reached more than once in 08Q1
- Up to €2,300/MWh for the 08-09 hourly product
- 1.2 GW traded in 08Q1 in the final minute, plus 340 MW in the hourly product
- Imbalance price up to €6,600/MWh
📊 What we know
Aggressive buying kept executing orders until the order book ran thin. The spike stayed confined to 08Q1, while 08Q2 to 08Q4 traded only slightly higher. That points to a very short-lived event, not a repricing of the whole hour.
The intraday prices then fed into the German imbalance price through the ID AEP component, and the system turned long afterwards.
🔎 What could explain it
Wind actuals were broadly in line with forecast, so a wind miss does not appear to be the cause. Possible drivers include a distressed short position forced to buy back at any price, or a badly configured algo, as suggested in early market discussion. Around 2.5 GW of downward redispatch asymmetry and expensive aFRR and mFRR stacks may also have added pressure.
🎥 Watch the video for the full breakdown.
Analysis by Vincent Thevenin.
Learn how you can stay ahead with Montel EnAppSys: eu1.hubs.ly/H0t98m20
Breaking news, Cal 2027 hit 100€/MWh in France.
Where will it stop ?
^CB
PS: chart from Montel Markets. Watching a round number break in real time is a different job than reading about it the next morning.

When should you buy electricity, and how much price risk should your business take on?
For energy-intensive businesses, these decisions affect both production costs and budget certainty. A structured procurement strategy can help manage exposure to volatile markets and support longer-term planning.
Join our free Energy Intensive Week session, held in partnership with EUROPEAN ALUMINIUM, “How to buy energy at the right time and reduce procurement risk”, to explore:
🔹 What is driving electricity price volatility
🔹 Procurement and timing strategies for managing exposure
🔹 Market indicators industrial buyers should monitor
🔹 How to build a more resilient procurement strategy
Hear industrial perspectives from Even Simonsen, Head of Commercial Development at Norsk Hydro, and Juha-Pekka Paunu, Category Manager, Electricity at Outokumpu. Montel’s Italy News Editor, Enza Tedesco, will moderate the discussion.
📅 20 October | 14:00–15:00 CET | Free webinar
Register for free: eu1.hubs.ly/H0yWhZW0
