

Looking for niche market leaders with long investment runways. Not financial advice. Always do your own due diligence.
Joined January 2021
- Tweets371
- Following345
- Followers9.7K
- Likes2.2K



$6135.T Makino was pitched today at the Sohn Tokyo Investment Conference. With Japanese machine tool exports at record levels, the company has strong momentum while its valuation remains reasonable. New orders and backlog are the key variables to watch in the upcoming results.


$6135.T In a March interview, Makino's sales executive said: “We’ve heard about Starlink-related components, so that might be a positive development for our company as well.” I checked, and he is right - SpaceX likely uses Makino's machines to make Starlink satellites.
SpaceX manufactures Starlink satellites at the dedicated facility in Redmond, Washington. GPT 5.5 helped me unearth local county permit records, which show new foundations for relocated machinery and related fire-alarm alterations in early 2025 under the project name "SPACEX SE03 - MAKINO EXPANSION AND HITL".
In addition, SpaceX is looking for experienced machinists for the Redmond facility to operate multi-axis CNC machines, including 5-axis mills and 6-axis lathes.
This convinced me that Elon is also a fan of Makino's gigantic "mother machines".


Tourists are getting liquidated while TSMC $TSM bulldozes ahead. Do investors really think this train will abruptly stop? The AI demand is strong, supply struggles to keep up, company fundamentals are solid, and semi valuations are attractive. End of story.

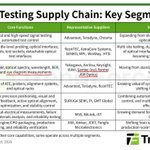
TrendForce analysts finally came across Santec $6777.T The “eye diagram measurements” instruments have nothing to do with the optical testing, though. They belong to Santec’s medical diagnostics business, MOVU, which competes with Carl Zeiss in the pre-cataract surgery market.

One of the main reasons I invested in Santec $6777.T was its highly lucrative medical business – MOVU. I generally understood where the optics are going, but couldn’t imagine the speed and scale of transition.
On the other hand, Santec’s success in the eye diagnostics market in partnership with Alcon $ALC was evident, but not everyone paid close attention. Two years ago, I thought investors failed to price in the upcoming launch of ARGONAUT – the new multi-modal eye imaging system that would supplement the ARGOS biometer. The irony is that the ARGONAUT is still awaiting FDA approval, while Santec’s share price took off without it. We might finally see the ARGONAUT later this year, though. On the recent earnings call, Alcon’s management indicated that Unity DX whole-eye analyzer (Alcon’s branded version of the ARGONAUT) is about to launch.
Considering Santec's rich valuation, I don’t think this will move the share price much when it happens, but it could still be a nice surprise.


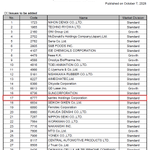
$6777.T Santec will be added to the TOPIX at the end of October. This will be a material liquidity event, given Santec's free-float market cap is only ¥128bn. My napkin math shows that theoretical index demand should be around 15% of the company's float at today's prices.

$295310.KQ HVM is rushing to meet SpaceX orders with additional melting and forging capacity. KIS is also reporting that HVM completed material testing for gas turbines made by a domestic power equipment manufacturer. The producer in question is almost certainly Doosan Enerbility ($034020.KS), which is aggressively expanding gas turbine production in Korea and localizing the material supply chain. This revenue opportunity will likely be small for HVM in the near future, but it opens up new markets and reinforces the company’s manufacturing capabilities.


Sold Sphere ($347700.KQ) at a small profit to double down on HVM ($295310.KQ). HVM is rapidly expanding output of advanced metal alloys to support Starship production. Orders from SpaceX are rising faster than sales, boosting near-term visibility. Now all we need is daily Starship launches by August 2027, as Musk promised. Easy-peasy 👍

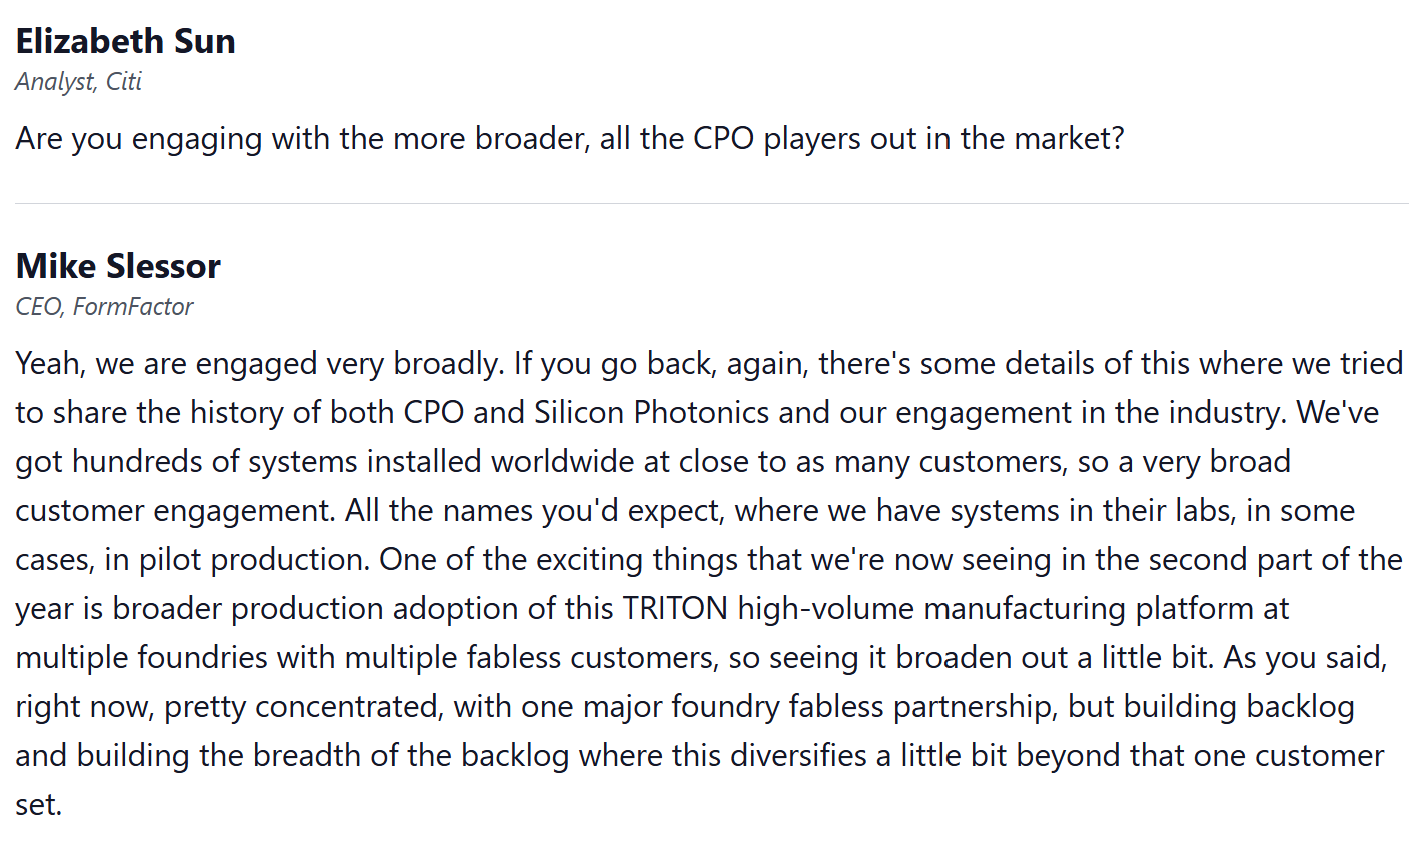
Are you sure about Advantest ($6857.T)? In the April earnings call, management said it received its first high-volume ATE order for silicon photonics (V93000-TRITON platform). Then in September, Advantest’s partner FormFactor discussed broader production adoption of the TRITON platform at multiple foundries. Finally, ficonTEC’s parent company, RoboTechnik, mentioned in the September prospects that it has shipped silicon photonics testing equipment to Customer Q, who “is a manufacturer of semiconductor automatic test equipment, headquartered in the United States. Shares of its parent company are listed on the Tokyo Stock Exchange.” I assume it is Advantest.




$4368.T FUSO Chemical trades at a discount to CMP slurry formulators (Fujifilm, Entegris, Qnity Electronics, Anji Microelectronics), even though its competitive advantage is arguably stronger and more durable. FUSO has effectively monopolized the ultra-high-purity colloidal silica market and has become a critical supplier to leading-edge chip production lines globally. Strong performance figures sustained over multiple quarters, recent silica price hikes, and investor outreach should improve the company’s perception over time.


$4368.T FUSO Chemical reported strong Q1 numbers across the board: revenue up 22%, operating profit up 32%, and net income up 115% (incl. government subsidies). This time, both the semiconductor materials and life sciences businesses contributed to earnings growth. Higher sales volumes of ultra-high-purity colloidal silica, price revisions announced earlier this year, and weak JPY were the key drivers. The life science business (food acids) finally began to recover with operating profit up 47%. The unchanged guidance implies a surprisingly weak Q2, which I think is too conservative. To meet overwhelming compute demand, chip foundries worldwide are ramping up wafer output and consuming increasing volumes of CMP slurries as they bring more production lines online. If anything, I expect an acceleration in FUSO’s silica sales over the next few quarters. Add to that 5-10% price hikes + moderating depreciation charges from the recently launched silica reactors, and you get 25%+ annual OP growth in the next three years. I think the company's valuation today leaves about 30-40% upside.

$6492.T I sold Okano Valve today for a 60% gain in six months. Thanks to @scg_oz astute comments, I revisited my valuation assumptions and realized they were too aggressive. I went through Okano’s numbers before the Fukushima disaster, made a few adjustments, and updated my earnings estimates. As a result, I now think Okano is worth around ¥17,000 per share instead of ¥22,000, when I implicitly assumed 9-10 reactors would be online by 2031. I believe 6-7 reactors is a more reasonable forecast today. I also don’t expect international expansion and next-generation reactors to move the needle soon, given regulatory hurdles. More inspection and restart work could create additional upside, but I wouldn't bet on it. Altogether, I think Okano is close to fair value today. Thanks everyone for the critical feedback, keep it coming!

I think Okano Valve Manufacturing (6492.JP) is an exceptional investment opportunity. It is the cleanest and cheapest way to invest in the nuclear renaissance I have found. I’m grateful to @JimJimmeny11 for the idea. Okano is a highly specialized manufacturer of high-temperature, high-pressure valves for nuclear and thermal power plants, with almost 50% of revenue from maintenance services. It holds a near-monopoly position in the Japanese market, protected by decades of operating experience and impassable qualification barriers. Okano is entering a multi-year earnings upcycle as Japanese utilities recommission reactors and replace aging valve infrastructure, driving revenue growth off a depressed base with significant operating leverage. I expect the recent disruptions to energy supply will break remaining political resistance to nuclear restarts and compress the launch timeline. Despite strong demand tailwinds, the firm’s valuation doesn’t price much growth. On my FY2026 numbers, P/E is 13, and EV/EBITDA is 8. Investors evidently do not consider international expansion or next-generation reactors as valuable options. Like Togami Electric Manufacturing (6643.JP), Okano’s risk/reward ratio is heavily skewed today, so I made a large investment last week under ¥10,000 without overthinking it.


Macquarie analysts recently met with Okano Valve Manufacturing ($6492.T) to get a feel for Japan’s nuclear restart cycle. The key takeaway is that once a reactor powers up, it creates long-term recurring demand for inspection, overhaul, and replacement services. Okano’s maintenance services already account for more than 50% of total revenue and reportedly generate 10-20% higher margins than initial equipment sales. As more reactors come online across Japan, Okano’s earnings durability and quality will continue to improve, ultimately increasing its terminal value.


At least Okano Valve ($6492.T) didn’t drop after Q3 results. The 9M numbers look good: 90% progress on revenue guide and 134% on OP (FY shift impacts YoY comp). There will be a seasonal slowdown in Q4, but I don’t see OP going negative. Last quarter’s OP margin hit 27%, driven by maintenance work at Onagawa No. 2, Kashiwazaki-Kariwa No. 7, and Fukushima Daiichi. New valve sales included Kashiwazaki-Kariwa, Tokai No. 2, and Fukushima Daiichi. Overall, the nuclear thesis remains on track. Okano remains undervalued, so I’m holding.

If you are researching a company with overseas sales, try asking your trusted AI companion to trace its product movements through customs over time. You will be surprised to find actual client names, specific products, and their likely applications. This exercise is especially useful in the small-cap land, where information is scarce.
For instance, it helped me link HVM ($295310.KQ) to SpaceX by revealing several multi-ton nickel alloy shipments from Korea to the US. I also became more confident in Nissei ASB's ($6284.T) razor-and-blades model because I saw machine shipments followed by molds, spare parts, and service kits.
The bottom is likely in for Okamoto Machine Tool Works ($6125.T). Capital spending on 300mm wafer manufacturing has already turned a corner: Okamoto posted a 370% YoY jump in wafer polisher orders last quarter, as SUMCO, Shin-Etsu, and GlobalWafers reported tight 300mm wafer capacity and planned production line upgrades. The company’s grinders for packaging applications have also stirred up interest, thanks to Mitsui’s commercial push in Taiwan.
I expect these two product families (wafer polishers and grinders) to power a strong earnings recovery starting this year. With demand stabilizing, the machine tool business should no longer depress margins after hitting its lowest profitability in 15 years. I believe Okamoto’s current valuation offers at least 50% upside. I bought a few thousand shares today.


At this point, I think it is a reasonable bet that further AI progress will lead to an R&D explosion. Logically, you would want to own suppliers of scientific instruments and systems that enable automated closed-loop experimentation. $BRKR Bruker’s X-ray diffractometer D8 Endeavor showed up in Periodic Labs’ setup. $268A.T Rigaku is pushing its LabLinc Studio and hardware for autonomous materials discovery. $7701.T Shimadzu demonstrated a modular robotic biotechnology laboratory. $TECN.SW Tecan's instruments are helping to speed up drug development. Any other good leads? I'm struggling to find pure-play ideas with sensible valuations.

We built high-throughput materials labs in Menlo Park to create a loop between experiments and models. The labs generate fresh data, the models learn from it, and then help us decide what to try next.
Using only 1,300 H200s, plus months of our experimental data, we mid-trained and RL’d an open-source model to surpass GPT-6 Astra on our analysis benchmark. We call it Neon.
This is real footage from our lab. We’re focusing first on hard problems in materials science, including superconductors, magnets, and semiconductor materials.
Read our blog posts below.
Here, an Nvidia engineer echoes Fabrinet's remarks: we need much more testing equipment as optics get messier. Tight technical specs and high manufacturing complexity require advanced optical instruments to maximize yield. $6777.T Santec is going all out to keep up the pace.

Very bullish read-through for Santec $6777.T from its major client, Fabrinet $FN. Bottom line: optical testing tools are taking center stage. On the earnings call yesterday, Fabrinet’s CEO noted that as NPO scales to 6.4, 12.8 TB, and beyond, manufacturing complexity and yield become increasingly important. He also outlined plans to double production capacity within 3 to 4 years. So, increased capex combined with higher test intensity = durable demand for Santec’s equipment.

Time for a rerun on Enplas $6961.T? Sales of GPU, ASIC, and CPU burn-in test sockets are booming. New lens connectors for 1.6T optical transceivers are about to enter mass production. Several clients are already evaluating next-gen CPO product samples. 14x P/E seems undemanding.


There is a sharp disconnect between the stock performance and the fundamental developments of my semiconductor holdings over the past two months. What am I missing? The market signals that the peak is around the corner and that current earnings are not sustainable. I don’t see it.
Unless demand collapses, solving the compute shortage requires a massive increase in supply, which will drive sustained, multi-year demand for equipment and material vendors. C.C. Wei stressed on the last earnings call that he refuses to overextend and shoulder the AI industry's risk. Even so, TSMC is aggressively expanding capacity to meet the compute demand through 2030. Nvidia’s numbers and comments yesterday only underscored the urgency. Against this backdrop, I expect FUSO Chemical $4368.T and GLTechno $255A.T to deliver strong returns as key suppliers of production consumables. FUSO is now back to ~16 P/E, while GLTechno is at 11.

$255A.T GLTechno had arguably the best quarter among my holdings, yet the stock fell 4% after the results came out last Friday and finished down 11%. The semiconductor business is firing on all cylinders: sales are accelerating, margins are expanding, and orders are booming. The order backlog is up 130% YoY and 51% QoQ, with a book-to-bill ratio at 1.7. Applied Materials $AMAT is placing massive orders for GLTechno’s quartz glass components to service installed equipment and build new tools. In turn, GLTechno plans to double its flame-processing capacity in Japan starting in January 2027. As a bonus, the analytical instruments business is also performing well, fueled by robust sales of water-testing consumables.
At 12 P/E, I think GLTechno has the highest risk-adjusted upside across my AI-related positions and buy candidates. It deserves a higher portfolio weight.


Monolith Capital retweeted

We're excited to announce that santec will be exhibiting at SEMICON Taiwan 2026!
Come to visit us to explore santec's latest optical test and measurement solutions for Silicon Photonics, PIC characterization, wafer & die testing, and photonic device manufacturing.


Sold Sphere ($347700.KQ) at a small profit to double down on HVM ($295310.KQ). HVM is rapidly expanding output of advanced metal alloys to support Starship production. Orders from SpaceX are rising faster than sales, boosting near-term visibility. Now all we need is daily Starship launches by August 2027, as Musk promised. Easy-peasy 👍
🤖 Made with AI
Short update on my SpaceX bags in Korea – Sphere Corp ($347700.KQ) and HVM ($295310.KQ). Sphere went on an investor roadshow last week and confirmed a few things. First, it almost certainly has a 10-year supply deal with SpaceX, but can’t name the client due to an NDA. Second, HVM is in fact Sphere’s qualified supplier of specialty alloys. Third, space orders are real and accelerating. Finally, Sphere is considering three new distribution centers near Los Angeles, Texas, and Florida, consistent with SpaceX’s operating footprint.
On the call yesterday, SpaceX CFO Bret Johnsen said: “We continue to make progress building the infrastructure required to support thousands of Starship launches per year, including accelerating Raptor and launch vehicle production, the build-out of our Gigabays and making significant progress towards activating multiple launch pads at Starbase and in Cape Canaveral at Pad 39A and Pad 37.” In short, Elon needs an absurd amount of metal, and the Koreans are working triple shifts to deliver it.


HM Solution works closely with Seikoh Giken $6834.T on an automatic fiber inspection system. With this acquisition, Santec $6777.T becomes more deeply integrated into the optical production ecosystem. Its earlier acquisitions of JGR Optics and OptoTest Corp have been home runs.


I’m no doomer, but such a tepid reaction to $SKHY $29 billion buyback spells trouble for the AI trade. That’s alongside a broader sell-off in semis after solid earnings. Investors are clearly tuning out the good news and obsessing over risks. Not a great setup.