

Investing for Financial Freedom
Joined November 2017
- Tweets6.4K
- Following776
- Followers2K
- Likes4.2K





Mike Romano retweeted

.@InvestmentGuru_ just opened a $OPEN (Opendoor) position on Slice, rate-sensitive housing play as 10-year yields roll back from 5.15% to 4.96%.
Full thesis: bit.ly/InvestmentGuru
Follow him on Slice for full access to his content.

Mike Romano retweeted

WHY $OPEN COULD BE THE BIGGEST TURNAROUND OPPORTUNITY OF 2026
Opendoor could be emerging as one of most interesting turnaround opportunities in the market because investors have become so focused on the deteriorating housing environment and the company's history of disappointing financial results that they're overlooking how much the underlying business is beginning to change under CEO Kaz Nejatian.
Opendoor has spent years struggling to demonstrate that buying and reselling homes can become a consistently profitable business, and the recent macroeconomic environment certainly hasn't made that any easier since mortgage rates have climbed back above 7%, housing affordability remains stretched and transaction volumes continue struggling, which helps explain why stock has fallen more than 40% since February which is what makes this situation particularly interesting is that management is no longer simply waiting for lower interest rates to rescue the business but is actively improving the economics of acquiring, holding and selling homes in an environment where broader housing market remains incredibly challenging.
I think that's an important distinction because if Opendoor can demonstrate improving profitability while housing activity is depressed, the potential operating leverage when transaction volumes eventually recover could be considerably greater than investors appreciate today.
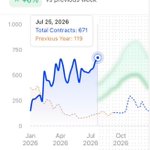
The biggest reason I'm becoming more interested in Opendoor is that we're finally seeing tangible evidence of operational improvements rather than simply listening to management promise a turnaround since during Q2 you can see how Opendoor increased home purchases 77% sequentially and 149% year over year to approximately 4,378 homes, while completing 6,908 acquisition contracts despite spending only about $5 million on marketing but what's particularly encouraging is that those improvements are beginning to show up in unit economics because contribution profit increased 59% sequentially to $51 million, contribution margins reached 4.8% and contribution profit per home sold improved by approximately $5,000 to $22,000.
Now, I wouldn't confuse improving contribution profit with reaching companywide profitability because Opendoor still reported an adjusted EBITDA loss and sold considerably fewer homes than a year earlier, but I think the direction of these operating metrics suggests the restructuring is beginning to produce measurable results.
Higher mortgage rates could absolutely delay the turnaround, especially because expanding home purchases requires significant capital while unsold inventory exposes shareholders to housing price declines and additional financing costs.
Dilution is another legitimate concern because Opendoor has issued substantial equity over the past year, while stock-based compensation remains elevated relative to the company's profitability.
However, I think there's a reasonable argument that the market is becoming so focused on those risks that it's overlooking the possibility of a much more efficient operating model emerging underneath them.
If Opendoor can sustain stronger unit economics and faster inventory turnover through this difficult environment, even a modest improvement in mortgage rates and housing activity could create meaningful operating leverage as fixed costs become spread across a larger volume of transactions.
Ultimately, I think the possibility of Opendoor becoming one of the deals of the year comes down to whether investors are valuing the company based on its historical inability to generate attractive returns or recognizing that its underlying economics could be approaching an important inflection point.
Management expects revenue, margins and transaction velocity to improve year over year in Q3, while continuing to target positive adjusted net income by the end of 2026, which would represent an important milestone if achieved.
With the stock trading at a relatively low multiple of trailing revenue and short interest around 22%, I think even modest evidence that the turnaround is working could create a substantial revaluation, although neither a low sales multiple nor elevated short interest guarantees attractive returns.
The biggest things I'll be watching are whether contribution profit per home continues improving, whether faster inventory turnover translates into stronger cash generation and whether Opendoor can expand transaction volumes without sacrificing underwriting discipline or requiring substantial additional dilution.
I still view this as a speculative opportunity rather than the type of durable compounder I'd want anchoring a long term portfolio, but I think the risk/reward becomes increasingly interesting if management can prove that the company is capable of generating sustainable profits before the housing market meaningfully recovers.
My thesis is that investors are waiting for mortgage rates to decline before reconsidering Opendoor, while the more important opportunity may be recognizing how much stronger the business could become by the time that recovery eventually arrives.
If management executes, I think today's valuation could eventually look extraordinarily attractive, but the next several quarters need to prove that the operational turnaround is creating real value for shareholders rather than simply increasing transaction volumes.

Mike Romano retweeted

I've been slowly adding to $ONDS again because after years of acquisitions across autonomous defense I think we're finally reaching the point where we get to see whether all those pieces can form a real platform.
The company now has counter-drone systems, long-endurance surveillance through ULTRA and World View, Mistral's defense relationships, ground robotics and a growing software layer through $PLTR, Omnisys, DefenseOS and Regna that could connect everything together.
The upside could be massive as modern warfare shifts toward coordinated autonomous systems across air and ground so Ondas has essentially bought all the pieces it needed to become a serious player but now they have to prove they built a company.
Mike Romano retweeted

$ONDS is doing big things.

Yesterday @PalantirTech named Ondas and @regna_ai among its flagship sovereign AI customers. Regna AI, built on Palantir AIP and @nvidia Nemotron, deploys mission-specialized AI on customer terms. $ONDS
businesswire.com/news/home/2…

Mike Romano retweeted

$IREN is already thinking about 2028 and beyond.
This is the easiest multi-year hold.

IREN is advancing sovereign AI in Europe, bringing together its European data center capacity and managed cloud services for customers seeking more choice over where their AI workloads run and how their data and infrastructure are managed.
Announced today at NVIDIA GTC Berlin, IREN has established IREN Europe and appointed Ángel Corcóstegui as Chair of the newly established board of directors.
IREN also secured the civil works license for its planned 300MW campus in Badajoz, Spain. Following the completion of its acquisition of Mirantis, IREN’s software capabilities include workload isolation and operational controls that can help customers address data residency, security and governance requirements.
Read more: iren.gcs-web.com/static-file…

Mike Romano retweeted

Before when Kaz joined $OPEN vs a year later 😂😂😂😂 @LiebermanAustin you don’t lost your mind FAKE ASS FAN looking for attention!!! Now you got our attention


Mike Romano retweeted

Fahd sums up the sentiment of myself as an employee. We’re executing or dying trying. There is no “well we gave it our best shot”. All in. My family and I are levered on opendoor’s success in multiple ways.

Hey Austin, I don’t know you but we seem to have a few mutuals. Looks like you have a decent track record as an emerging investor and your background is incredible. First and foremost, thank you for your service and serving the USA.
I’m Fahd, I work at Opendoor and joined with Kaz the day after he joined. I lead our product and design teams.
I just want to clear two things up:
1. Kaz will probably always understate this but he was responsible for saving Shopify at least once.
2. Turn arounds, especially in public, present a lot of challenges that you have to work through piece by piece. Like untangling wired headphones while the car is going over a bumpy road and your kids are screaming in the back. These things take time, focus, and clarity. I’ve seen these a few times from the stands (Carvana, Robinhood, Snapchat, etc). It’s a little bit different when you’re flying the thing.
We’ll have to let the rest play out and see where the chips fall. I will be on this mission through to the very end until we succeed or I will die trying. That’s all for now. All the best man.
Mike Romano retweeted

$OPEN 🚨 Kaz Nejatian now holds BOTH CEO and President titles following Lucas Matheson's departure.
This gives Kaz more direct control over Opendoor's execution.
✅ Fewer leadership layers
✅ Potentially faster decisions
✅ Greater control over strategy
✅ More accountability for results
Kaz is putting himself firmly in the driver's seat.
Bullish if he can execute. Now let's see the results.
What do you think, smart consolidation of power or a red flag? 👀

After a great deal of thought, I’ve decided to step down as President of @Opendoor. This was a deeply personal decision, and I’m grateful to have worked alongside an incredible team - working on an incredible mission. Looking forward to staying involved as an advisor. @Nejatian, thank you for everything! 🏡
Mike Romano retweeted

BREAKING: SPACEX-TESLA MERGER TARGETED FOR 1H 2027
SpaceX $SPCX and Tesla $TSLA are reportedly pushing to finalize a merger by the first half of 2027, with plans to close before the end of President Trump’s term.
The companies are exploring a potential deal, but no agreement has been finalized.

Mike Romano retweeted

Mike Romano retweeted

IREN is advancing sovereign AI in Europe, bringing together its European data center capacity and managed cloud services for customers seeking more choice over where their AI workloads run and how their data and infrastructure are managed.
Announced today at NVIDIA GTC Berlin, IREN has established IREN Europe and appointed Ángel Corcóstegui as Chair of the newly established board of directors.
IREN also secured the civil works license for its planned 300MW campus in Badajoz, Spain. Following the completion of its acquisition of Mirantis, IREN’s software capabilities include workload isolation and operational controls that can help customers address data residency, security and governance requirements.
Read more: iren.gcs-web.com/static-file…
Mike Romano retweeted
$IREN just created IREN Europe with plans for a 300 MW AI campus in Spain targeting operations in 2028.
The move comes as Europe pushes for greater control over its AI infrastructure giving IREN an opportunity to serve customers who want their data and compute managed locally.


Mike Romano retweeted

BREAKING: Elon Musk says SpaceX, $SPCX, and Tesla, $TSLA, have formed special committees to discuss a potential merger between the two companies.
"I do think there’s a lot of merit to combining the companies as we are pretty much in the superintelligence singularity, and there’s a lot to be gained from cooperating," Musk said.
"Do I think it would be a good idea? Yes, but at the end of the day, the shareholders have to be supportive of this," Musk said.
Mike Romano retweeted

Been obsessed with the stock market since I was a teenager. Have traded through the dotcom bubble, the financial crisis and just about every market mania since. But I’ve never seen anything like the skepticism surrounding AI. Not even close. Every time one bubble narrative falls apart a new one takes its place. Rumors become headlines. Misleading data goes viral. Claims that could be debunked with 5 minutes of research get repeated by major media outlets, influential investors and Wall Street analysts. It’s relentless and honestly pretty fascinating to watch. Of course there will be spectacular failures and massive wealth destruction along the way. That’s what happens during technological revolutions. But I’ve never witnessed this much effort to convince the world that something so transformative is actually one giant speculative bubble destined to take the entire economy down with it. I understand why AI scares people. What I find harder to understand is why so many investors seem to be rooting for it to fail.
Mike Romano retweeted

"They can kind of hijack the pilot, take over the signal and land the drone with parachutes." -@StockMarketNerd
Brad explains how Sentrycs, one of the companies $ONDS bought, takes over a hostile drone. With @StockSavvyShay.
Mike Romano retweeted

A lot of questions this week on funding, so here's how a GPU typically gets funded at $IREN.
First, the customer signs a multi-year take-or-pay contract and agrees to a prepayment. On our recent 3-year contracts, prepayments have been 45% to 55% of the associated GPU capex.
Second, financing is committed, secured by the contracted GPUs. On the Microsoft contract we secured an A-rated facility at around 6%, which together with prepayments covers 96% of GPU capex. More recently, for a non-investment grade counterparty at Mackenzie, we secured financing at 9% fixed, which together with prepayments covers more than the full cost of the GPUs.
That's the GPU side. The data centers are a separate, long-term asset base, and we own the ones our GPUs run in. Construction has been funded from cash to date, with no debt against these multi-billion dollar assets. As they come online with contracted customers, they can support financing in their own right.
The processes behind the next facilities are continuing, and new paper will cost what the market charges. With GPU paybacks of around two years on our recent 3-year contracts, a wider spread barely moves the economics.
There's more customer demand than we can build for. As we noted at our recent earnings, 2026 is largely sold out, recent 3-year contracts are at more than double the prior year's pricing, and demand for anything we can bring online in 2027 covers it several times over, with prepayments a focus in every negotiation. Conversations on 2028 capacity are already underway.
Meanwhile announced capacity keeps slipping across the industry, which is the point: signing deals isn't the bottleneck in this market, bringing GPUs online is, and that's our focus.
Mike Romano retweeted
THE $ONDS OFFICIAL DEEP-DIVE EPISODE JUST DROPPED
What I think people are missing with Ondas is that management has spent last 18 months buying its way towards becoming an emerging defense prime spanning counter drone systems, long endurance surveillance, precision strike, ground robotics, manufacturing and the software connecting everything together.
That creates a massive opportunity for Ondas but it also makes the stock so difficult to own in 2026 because so much of that growth was acquired and financed through share dilution meaning management now has to prove these businesses can grow organically and become more valuable together than they were separately.


Mike Romano retweeted

All week, the Ondas team has been meeting with Army leaders, program offices and industry partners at AUSA. We’ve been talking about how autonomous systems help soldiers sense, decide and act first while operators stay in command. $ONDS
