

Head of digital assets research @VanEck_us. PM, VanEck Onchain Economy ETF ($NODE). ❌️ Disclosures https://xitter.cf/t.co/oN8RR1GzoJ https://xitter.cf/t.co/kuyqdO3qgW
NYC
Joined July 2017
- Tweets20.4K
- Following2.6K
- Followers66.7K
- Likes37.1K






Anthropic odds of a pre-2027 IPO are back near all-time highs despite the market action and the decay in these contracts.
Media reporting bankers are advising them to get it out before a possible Democrat takeover of House which might prompt investigations and roadblocks.

This morning at Grand Central, I alerted a security guard to a man sprawled in a corner, his overpowering stench filling the hallway. I hoped he might notify the police.
His response: “What do you want me to do, wash him?”
Same "guards" who let people jump the turnstiles.


If the owner of FTX's old Bitcoin mines gave every American $2,500, they'd still have $75 billion left over.
Or so @TheEconomist would have you believe.

matthew sigel, recovering CFA retweeted
Scoop: Visa in talks to acquire Fireblocks for around $2.5B axios.com/pro/fintech-deals/…

META’s been saying for over a year that its AI ranking models are driving more clicks and conversions for advertisers, which should let it charge more per ad.
Seems the story is playing out.

$META +3% AH.
>Revenue $64.6B beat (guide was $61-64B)
>FY capex floor raised: $135-145B vs $130-145B, midpoint $140B.
>Q4 math: YTD capex (incl. finance leases) is $85.8B
>Raised capex guidance implies $49-59Bin Q4, ~$54B at midpoint, +55% q/q.
"Our AI investments are already delivering substantial incremental advertising revenue through stronger engagement, better recommendations, and more efficient monetization."
just now: "Improvements to Andromeda, such as scaling, model complexity, and throughput, increased conversions by 1.4% on Facebook. We're also leveraging AI to make it easier for businesses to manage campaigns, develop creative, and act on performance opportunities. Meta AI Business Assistant is becoming a more proactive and capable partner for advertisers.
We estimate that advertisers who adopted its recommendations drove almost 5% more conversions same cost per conversion and increased their advertising investment by 9% compared with similar non-adopters."
$META +3% AH.
>Revenue $64.6B beat (guide was $61-64B)
>FY capex floor raised: $135-145B vs $130-145B, midpoint $140B.
>Q4 math: YTD capex (incl. finance leases) is $85.8B
>Raised capex guidance implies $49-59Bin Q4, ~$54B at midpoint, +55% q/q.
"Our AI investments are already delivering substantial incremental advertising revenue through stronger engagement, better recommendations, and more efficient monetization."
$META reports after the close. We think 3Q26 earnings could be positive read through for $CLSK & $APLD (among all PSPs and neos)
- Look for Muse monetization and potential compute expansions to support it
- FY 2026 capex guide is currently $130-145B
- FY 2027 consensus capex guide is $193B
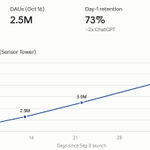
Muse early adoption looks strong with 10.9M downloads and ~2.5M DAUs, much faster growth than other launches (although caveats being Muse launched on IOS and Android at once while ChatGPT, Claude and Grok were initially IOS only, and it was heavily promoted taking up most of Metas house-ad impressions). DAU durability is an open question due to this heavy marketing push.
Lot of focus on Muse's monetization path and compute needed to support it, which is relevant for $CLSK which already has a 20-year lease with Meta at Sandersville (175MWs), and a LOI/exclusivity for 885MWs in its TX portfolio. Commentary supporting more 3P leases of capacity would be positive and would support lease execution of this additional power. Would be good to hear that Meta is back focused on utilizing its compute in-house rather than re-selling excess.
Meta is also expected to come to debt markets shortly after earnings to fund capex plans, a smooth process could support their ability to keep expanding capacity via 3P leases (CLSK).
It is also believed that APLD's two newest leases are with Meta (one unnamed hyperscaler), 300MW in Louisiana and 300MWs in North Dakota. Although this is unconfirmed. Also a potential beneficiary around commentary from Meta around wanting more 3P compute.
matthew sigel, recovering CFA retweeted

The GENIUS Act marks a watershed moment in American finance, further cementing the United States as the crypto capital of the world. Just as President Abraham Lincoln’s National Currency Act of 1863 established a national framework for bank-issued currency, the GENIUS Act establishes a federal framework for payment stablecoins in the digital age.
The @USOCC's final rule carries that landmark legislation forward, providing a clear, practical foundation for private-sector innovation, competition, and American leadership in digital assets.
Consolidation begins.

Soluna and Applied Digital are partnering to develop a 50 MW critical IT AI data center at Project Dorothy 3 in Briscoe County, Texas — powered by the Briscoe Wind Farm. ChronoScale Holdings has signed a letter of intent to lease the planned facility.
solunacomputing.com/news/sol…
$SLNH @APLDdigital #CHRN

Supermicro +11% $SMCI
Preannounced F1Q27 revs/GMs (full results 11/3) well above guidance: revenue of $18.5-19.5B (vs $14.5-15.5B guide) and GM of 12-12.5% (vs 10.5-10.8% guide) on increased demand for AI platforms.
They don't disclose any of their customers but mgmt characterized recent demand as mainly emerging neoclouds and cloud service providers, as well as some enterprise.
Read through is strength in the neocloud/AI lab buildout.
First sign of activism at powered shell company $IOND
Ionic has a triple net lease with Nscale (234 MW).
Investor could be looking for board seats (staggered board). Seems management already sunsetting legacy mining assets.

$BTDR +6% AH.
September production reports shows AI cloud backlog from $900M --> $2.9B. Most of that came from the A201 offtake (>$1.7B over 5 years), which was announced in September.
With 35% of float short, any good news, however duplicative, can move the stock.
$PAYO surveyed 265 senior payments/finance leaders at US based enterprises with >$100M in revenue that also have cross border operations.
Among respondents, 69% use stablecoins operationally, including 41% at meaningful scale, and 82% expect it to become part of their financial infrastructure within three years.
"The argument over whether stablecoin is a crypto curiosity or viable financial infrastructure is over, at least for the enterprises already in the arena. These businesses have stopped debating it and started seeing its impact."

Goldman Sachs: "We upgrade CoreWeave from Neutral to Buy with 73% upside to our price target of $106 (down from $139 prior). The stock is down 43% since Aug 11 (2Q EPS) and 24% in the last 5 trading days, per our understanding due to a) ongoing volatility in the credit market, which raises questions on if and at what rate CoreWeave will
be able to finance their next phase of growth; b) debate on demand for intelligence at the frontier vs. off frontier, and whether changing mix impacts token monetization at CoreWeave’s customers, which in turn is key for the ecosystem to realize returns on compute investments. Going back to Finance 101, we see CoreWeave’s enterprise value as being directly correlated to the magnitude and durability of the spread between its unlevered IRR and WACC — and we think investors may be underestimating the magnitude of upward revisions to uIRR, and overestimating the magnitude of upward revisions to WACC."
"Based on our industry conversations, CoreWeave will still likely be able to raise DDTLs; and DDTL 5.0 and 5.5 both trade at or above their originally issued discount."
$MSTR raises STRC buyback program from $2B to $3B
STRC hit $99.9 last week before fading to $97.72 after MSCI finalized rules to remove MSTR from indices.
Note MSCI is largely absent in preferred indices, making STRC par a key battleground to restart larger BTC buys via ATM.
