

Daily data-driven BUY/HOLD/SELL stock ratings. Every call tracked publicly: https://xitter.cf/t.co/6uZH5lFZNo Substack: https://xitter.cf/t.co/4zWEopnCvo
Barcelona / Madrid
Joined September 2019
- Tweets1.5K
- Following140
- Followers194
- Likes80



Pinned Tweet
Our public scorecard, updated weekly: 188 BUY/HOLD/SELL calls tracked, 80.0% hit rate, +11.7% average signal return.
Every call is timestamped and tracked against what the stock actually did. Latest numbers below 🧵

SEC What Changed — 20 Oct 2026 🧵
Penguin Solutions’ MD&A shows the SMART Brazil exit is complete and the business is being recast around AI and HPC demand. That shift removes a legacy drag, but it also ties growth more tightly to a narrower, more cyclical demand base.
FACTSET RESEARCH SYSTEMS INC Risk Factors changed most. The filing shows a sharper push into AI solutions, alongside restructuring and compensation costs that pressure near-term margins while recurring revenue growth continues.
If you liked this research, check out the full analysis 👇
lf0.com/research/penguin-sol…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.

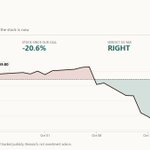
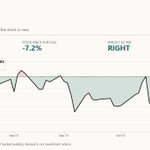
We rated $FTNT SELL. Tracked from Jul 2 at $156.25.
It closed Oct 20 at $170.93 (+9.4%). Against us so far.
Every call is tracked daily through Dec 31, so this can still change. We report the final result either way.

The original analysis behind the call:
lf0.com/research/fortinet-st…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.


Full review: lf0.com/research/scorecard-s…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.

HOLD
$POWL is a high-quality industrial, but the stock already prices in a clean execution path.
It trades at 56.7x trailing earnings, 42.2x forward and 43.7x EV/EBITDA. Q1 2026 revenue rose 6.5% to $296.6M, yet EBITDA slipped to $59.8M from $60.6M and net income to $45.9M from $46.3M.
The balance sheet is a strength: only $2.0M of total debt and a 2.3x current ratio. Backlog was $1.3B at September 30, 2024, with $849.0M expected to convert in fiscal 2025.
I would stay neutral until bookings reaccelerate.
Full breakdown:
lf0.com/research/powell-indu…
#Industrials #Stocks
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.

HOLD
$DVN generates a lot of cash, but the stock already prices it in.
Operating cash flow was $8.6B over the last twelve months, yet levered free cash flow was only $782.6M, a 1.4% FCF yield. At 7.4x EV/EBITDA and 9.4x forward P/E, this is fairly valued, not cheap.
The balance sheet is manageable: $11.9B of total debt and 1.23x net debt/EBITDA. The 0.7 current ratio and suspended buybacks under the Coterra merger leave less room for error.
I would get more constructive if free cash flow margin moves above 5.0% and the merger synergies show up in margins.
Full breakdown:
lf0.com/research/devon-energ…
#Energy #Stocks
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.

HOLD
$CDE is priced like a cash generator with clean balance-sheet support, but the valuation still assumes a lot of metal-price durability and execution staying near peak levels.
The market is not ignoring operating strength: Q1 2026 revenue reached $856.2M, up from $360.1M in Q1 2025, and EBITDA rose to $454.1M from $104.7M. That is a sharp step-up in earnings power, but it also sets a high bar for sustaining current results across the cycle.
The cash profile is real, not cosmetic. Levered free cash flow over the last twelve months was $511.8M, operating cash flow was $1.2B, and levered free cash flow equaled 20.0% of revenue. Those figures show the business is converting sales into cash at a meaningful rate, which is the main reason the stock does not screen as distressed.
The balance sheet does not add much urgency either: total debt was $773.2M, total cash was $843.2M, and debt/equity was 7.4%. On top of that, the stock trades at 8.0x forward P/E and 11.5x EV/EBITDA, which is not cheap enough to ignore the commodity and operating risks embedded in a miner.
The evidence supports HOLD.
Read the full breakdown here:
lf0.com/research/coeur-minin…
#Mining #Stocks
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
Also on LinkedIn: linkedin.com/company/1466901…


Full review: lf0.com/research/scorecard-g…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
HOLD
$ADM is priced like a stable compounder, but the cash generation and margin profile say the business is still working through a weaker cycle.
At $80.5, ADM trades at 22.1x trailing earnings and 15.8x EV/EBITDA, while the market is also assigning only 0.5x sales. That combination does not describe a distressed asset; it describes a company with real scale that is not being valued as a bargain on the headline multiple alone.
The balance sheet is not the issue, but leverage is not trivial. Total debt/equity stands at 39.1%, and the company still carries 2.8x net debt/EBITDA. Cash flow is positive, with $2.8B of operating cash flow and $1.2B of levered free cash flow over the last twelve months, but levered free cash flow converts to only 3.0% of market cap.
Profitability remains thin. ADM’s TTM operating margin is 4.0%, net margin is 2.2%, and EBITDA margin is 3.7%. The latest quarter showed revenue of $22.7B, up from $20.5B in Q1 2026, but the broader earnings base is still constrained by low margins rather than a lack of scale.
The operating trend also weakened in the annual results: total segment operating profit fell 23% to $3.2B in 2025, and the company recorded $473M of restructuring and impairment charges, including a $179M software impairment. That is not the setup of a business with clean, accelerating fundamentals.
The evidence supports HOLD.
Read the full breakdown here:
lf0.com/research/archer-dani…
#Stocks #Agriculture
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
Also on LinkedIn: linkedin.com/company/1466901…

HOLD
$AEM is priced like a premium gold compounder, but the cash flow and balance sheet say the story is already fully recognized.
The valuation is not cheap on operating earnings. AEM trades at 9x EV/EBITDA and 6.3x EV/Revenue, while the stock also carries a 16x trailing P/E and 15.6x forward P/E. Those multiples fit a business with strong margins, but they do not leave much room for disappointment.
The operating profile is still strong. TTM gross margin is 74.5%, EBITDA margin is 69.9%, and operating margin is 58.1%. Net margin sits at 40.4%, showing the company keeps a large share of revenue after costs. That is real quality, but it is already embedded in the current valuation.
Cash generation is the clearest support for the stock. Levered free cash flow is $4.3B, levered free cash flow to market cap is 4.5%, and levered free cash flow to revenue is 29.5%. The balance sheet is also conservative, with net debt/EBITDA at -0.3x and current ratio at 2.9x. That combination reduces financial risk, but it also explains why the market assigns a premium multiple.
Growth is positive, but the pace is not accelerating. Q2 2026 revenue was $3.8B versus $4.1B in Q1 2026, and Q2 2026 diluted EPS was 3.2 versus 3.4 in Q1 2026. Revenue was still up 35% year over year in Q2 2026, yet the sequential slowdown shows the market is not buying a fresh growth inflection.
The evidence supports HOLD for AEM.
Read the full breakdown here:
lf0.com/research/agnico-eagl…
#Gold #Stocks
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
Also on LinkedIn: linkedin.com/company/1466901…

HOLD
$CL looks priced like a steady cash compounder, but the valuation is already carrying a lot of that story before growth proves it out.
The stock trades at 36.8x trailing earnings and 22.8x forward earnings, with an EV/EBITDA multiple of 16.3x. That is a full multiple for a consumer staples business whose current share price is $93.4 and whose market cap is $74.4B.
The balance sheet does not show a stretched capital structure, but it also does not leave much room for error. Current ratio is 1.0x, and net debt to EBITDA is 1.3x. That combination supports stability, yet it does not create a clear valuation cushion when the equity is already priced for consistency.
Cash generation is solid, but not enough to make the setup cheap. Levered free cash flow is $3.5B, equal to 4.7% of market cap, while net margin sits at 9.68%. Gross margin is 60.4% and operating margin is 21.0%, which shows a strong spread, but the market is paying up for those economics rather than discounting them.
The operating trend is also mixed. FY2025 non-GAAP operating profit margin was 21.3%, down from 21.7%, and management cited 2025 gross profit margin pressure from 420 bps of higher raw and packaging material costs. Revenue in the Oral, Personal and Home Care segment was $15,769 in 2025, up 1.0%, with 1.8% pricing offset by 0.3% volume decline and 0.5% foreign exchange headwind.
The evidence supports HOLD: quality and cash flow are real, but the stock already reflects most of that strength.
Read the full breakdown here:
lf0.com/research/colgate-pal…
#Stocks #ConsumerStaples
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
Also on LinkedIn: linkedin.com/company/1466901…

Fair point on the risk, and our work is also bearish on CIFR. The latest quarter showed revenue of $34.8M, while operating margin was -249.4% TTM, so the business still looks far from steady profitability.


Full review: lf0.com/research/scorecard-r…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.

Full review: lf0.com/research/scorecard-p…
Follow for daily BUY/HOLD/SELL ratings. Every call is tracked publicly.
