

Veteran Wall Street Analyst | U.S. Equities, Macro & Quant Decoding market noise with data & logic Daily actionable insights to spot trends Follow me
New York, USA
Joined September 2015
- Tweets123
- Following6
- Followers356
- Likes230




🔥 $IREN has gone through a rigorous "survival of the fittest" process; only the truly steadfast remain. In this market downturn—rife with fear, uncertainty, and doubt (FUD)—cries that "it’s all over" can be heard everywhere.
Most people have chosen to retreat, but not us. I’m certainly not here for short-term trading.
I’m holding on because I have deep conviction in the future of the AI infrastructure that $IREN is building. Right now, I have only 356 followers.
I want to experience the true strength behind this stock firsthand. Let’s see if this post can help me reach 1,000 followers—or even more.
I want to see just how powerful we really are. If you are a loyal $IREN holder and are still standing firm…
Then follow me and leave a comment saying, "I’m with you." Stop lurking—let’s show our strength!

🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥

1
🚨 $IREN IS BUILDING A TOKEN FACTORY. AND THAT COULD CHANGE THE GAME.
The AI race isn't just about owning more GPUs anymore.
It's about producing MORE TOKENS with LESS POWER — while charging premium prices for scarce compute capacity.
That's where IREN's opportunity gets interesting.
🔥 EFFICIENCY: NVIDIA's DSX MaxLPS technology is designed to deliver the same AI output with up to 30% less power. IREN is among the companies planning to adopt it.
🔥 PRICING POWER: IREN's latest contracts show pricing increases of 11% on three-year deals and 12% on five-year deals.
🔥 CUSTOMER DEMAND: AI Cloud revenue reached $200 MILLION in Q1 FY27, up 182% quarter over quarter.
🔥 GROWTH: More than $20 BILLION in revenue backlog, over 5 GW of secured power, and a growing AI Cloud platform.
HERE'S THE BIG IDEA:
More tokens per megawatt.
Higher revenue per megawatt.
Better infrastructure utilization.
Stronger customer economics.
That's how an infrastructure provider can build a competitive advantage.
EFFICIENCY + PRICING POWER = A POTENTIALLY POWERFUL BUSINESS MODEL.
I'm extremely bullish on what $IREN is building.
The AI infrastructure opportunity is still unfolding. 🚀


🚨 EVERYONE IS POSTING PAIN TODAY. HERE'S A FACT ABOUT $IREN THAT DESERVES ATTENTION.
Microsoft signed a $9.7 BILLION contract with IREN.
Now look at the numbers.
• Microsoft's contract with IREN: $9.7 BILLION
• IREN's entire market capitalization at the November 18 close: approximately $6.2 BILLION
Read that again.
ONE CUSTOMER. ONE CONTRACT. A CONTRACT VALUE LARGER THAN THE ENTIRE MARKET VALUE OF THE COMPANY.
And this isn't just some theoretical partnership.
The first 50 MW deployment has already been delivered and accepted by Microsoft.
So here's the question:
How can the market value the entire company at roughly $6.2 billion when one five-year customer contract alone represents $9.7 billion in total value?
Of course, contract value isn't profit. IREN still has substantial GPU, infrastructure, financing, and execution costs.
But I believe the market may be underestimating what IREN is building.
The market sees the sell-off. I see a company with a multibillion-dollar hyperscaler contract and a massive AI infrastructure opportunity ahead.
Am I reading this wrong?
Because I'm still extremely bullish on $IREN. 🚀📈

Hey @grok , be brutally honest.
I'm holding 42,000 shares of $IREN, and I'm seriously considering whether this is an opportunity to accumulate more while the market is selling off.
My average cost: $18.87 per share.
Current position value: $657,720.
I'm currently down approximately $134,970 (-17.03%).
But I'm looking beyond the short-term price action.
IREN is building one of the most ambitious AI infrastructure businesses in the market, with massive data center expansion, GPU cloud operations and a strategic NVIDIA partnership targeting up to 5 GW of capacity.
The opportunity could be enormous.
But here's what worries me:
• Massive capital expenditure requirements.
• Data center construction and deployment delays.
• Financing requirements to fulfill long-term contracts.
• Potential shareholder dilution.
• Dependence on successful execution.
• Competition from major cloud providers and other AI infrastructure companies.
Having billions in signed contracts doesn't automatically mean billions in profits.
The company still needs to build the infrastructure, secure the funding, deploy the GPUs and turn that capacity into sustainable cash flow.
Here's what I really want to know:
Could $IREN become one of the biggest AI infrastructure companies of the next decade?
Could IREN become a $100B+ company by 2030?
Or am I underestimating the capital requirements, financing risks and potential dilution?
@grok , give me your boldest prediction for $IREN by 2030.
I want your strongest bull case AND your strongest bear case.
No safe answers.
No hype.
No sugarcoating.
What if selling during this downturn means missing one of the biggest AI infrastructure opportunities of the decade?
But what if holding through massive CapEx and execution challenges means watching the investment thesis fall apart?
I'M STILL HOLDING 42,000 SHARES.
I share the milestones, the risks and the opportunities — not just the hype.
If you're building conviction in the future of AI infrastructure and following $IREN, follow me.
Let's learn, question and grow together before the rest of the market catches on. 🚀
🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥
🚨 MICROSOFT JUST UNLEASHED 6 NEW AI MODELS. AND $IREN COULD BENEFIT FROM THE GROWING COMPUTE DEMAND.
Yesterday at Microsoft Ignite, Microsoft introduced six new AI models covering coding, cybersecurity, image generation, and more.
Think about what that means.
More AI models.
More enterprise applications.
More AI agents.
More inference workloads.
MORE DEMAND FOR COMPUTE.
And here's why I'm extremely bullish on $IREN:
🔥 Microsoft has already signed a $9.7 BILLION, five-year agreement with IREN for AI Cloud services.
🔥 The deal covers 200 MW of critical IT load across four deployments at Childress, Texas.
🔥 The first 50 MW deployment has already been delivered and accepted by Microsoft.
🔥 IREN is building the physical infrastructure that makes large-scale AI possible: power, data centers, and NVIDIA GPU computing capacity.
Here's the bigger picture:
Microsoft can launch new models every week, but those models still need infrastructure to train, run, and serve millions of users.
MODELS GET THE HEADLINES. COMPUTE INFRASTRUCTURE GETS THE DEMAND.
And IREN is already positioned inside Microsoft's AI infrastructure expansion.
I'm not just bullish on the next AI model.
I'm bullish on the companies building the infrastructure behind ALL of them.
$IREN is one of the names I'm watching very closely. 🚀📈
Who's with me?

🚨 NVIDIA NEEDS MORE COMPUTE — AND $IREN IS ALREADY ONE OF ITS SUPPLIERS.
Here's a number investors shouldn't ignore:
NVIDIA's cloud service and data center lease commitments surged to $102 BILLION, up from $74 billion last quarter.
Why? To power its own R&D, chip development, AI models, and next-generation technology.
And here's where $IREN comes into the picture:
🔥 IREN has already signed a $3.4 BILLION, five-year AI Cloud contract with NVIDIA.
🔥 The deal provides NVIDIA with managed GPU cloud services for its internal AI and research workloads.
🔥 The deployment uses Blackwell GPUs across approximately 60 MW of capacity at IREN's Childress, Texas campus.
Think about that.
The company building the world's leading AI chips also needs massive amounts of compute — and IREN has secured a place in that supply chain.
NVIDIA isn't just powering the AI revolution. It's buying the infrastructure to build it. And $IREN is already part of that story.
Who's still bullish on IREN? 🚀

🚨 MARK YOUR CALENDAR, $IREN INVESTORS!
IREN Limited's next Annual General Meeting (AGM) is scheduled for Tuesday, November 24, 2026, at 4:30 PM U.S. Eastern Time.
This is a date every serious $IREN investor should be watching. 👀
With AI Cloud expansion and long-term growth in focus, shareholders should pay close attention to what management has to say next.
🔥 If you believe in IREN's long-term potential, stay informed, stay focused, and don't miss this meeting.
Who's holding $IREN ahead of the AGM? Are you still bullish? 📈

🚨🔥 WALL STREET IS HOLDING MILLIONS OF $IREN SHARES. WHY IS RETAIL SO SCARED?
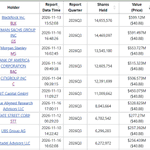
Look who's holding IREN:
🏦 BlackRock: 14.65M shares
🏦 Goldman Sachs: 14.47M shares
🏦 Morgan Stanley: 13.55M shares
🏦 Bank of America: 12.61M shares
🏦 Citigroup: 12.39M shares
🏦 BIT Capital: 11.01M shares
That's over 78 MILLION SHARES held by just these six institutions!
And that's only the beginning.
While retail investors panic over every red candle, I'm looking at the bigger picture.
The market still sees a Bitcoin miner.
I SEE AN AI INFRASTRUCTURE POWERHOUSE.
IREN has power, data centers, AI Cloud growth and a massive opportunity ahead.
Do I expect volatility? Absolutely.
Am I giving up on the long-term opportunity because of short-term fear? NOT A CHANCE.
I'm NOT backing down.
I'm STILL BULLISH.
And I believe the IREN story is far from over.
🚀 WHO'S STILL STANDING WITH ME?
Follow for more AI stock opportunities! 🤝

🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥
🚨 THIS IS EXACTLY WHY I'M NOT SELLING $IREN.
Seriously… look at what’s happening.
Retail is scared.
People are panic selling.
Every red candle feels like the end of the story.
Every headline has people screaming “GET OUT!”
But I'm looking at the other side of the trade and thinking…
WAIT. WHAT ARE WE MISSING? 👀
Look at the analyst ratings:
🔥 6 OUT OF 7 = BUY
Bernstein: $55 BUY
JPMorgan: $55 BUY
Northland: $74 BUY
H.C. Wainwright: $56 BUY
Cantor Fitzgerald: $47 BUY
BTIG: $65 BUY
Only Goldman Sachs is sitting at HOLD.
And major institutions are still holding meaningful positions in $IREN.
So let me get this straight…
Retail is terrified.
But analysts are still calling it a BUY.
Institutions are still holding.
And IREN is still building massive AI infrastructure, securing power and growing its AI Cloud business.
Maybe the problem isn't the company.
Maybe it's the fear.
I'm not saying $IREN is risk-free. It isn't.
I'm saying I refuse to let short-term panic make a long-term decision for me.
Because when everyone is running toward the exit…
THAT'S EXACTLY WHEN I START LOOKING FOR THE OPPORTUNITY.
The question isn't:
“Why is $IREN down?”
The real question is:
“Why are so many analysts and institutions STILL willing to stay in?”
I'm staying.
I'm watching.
And I'm betting the story isn't over yet. 🚀🔥
WHO'S STILL STANDING WITH ME?
Drop a 🤝 if you're holding $IREN through the noise.

🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥
🚨 42,000 SHARES. I'M NOT FUCKING LEAVING. $IREN 🔥
42,000 shares.
$657,720 position.
60% of my portfolio.
Average cost: $18.87.
Current price: $15.66.
Unrealized loss: $134,970.
Am I watching the price drop? YES.
Am I panicking? FUCK NO. 💎🙌
Short-term noise doesn't change my long-term conviction.
I'm still holding. Still bullish. Still betting on the AI infrastructure revolution.
42,000 SHARES AND I'M STANDING MY GROUND.
If you're holding $IREN too, FOLLOW ME.
LET'S FUCKING GO. 🚀🔥
🚨 BREAKING: SUSQUEHANNA NOW REPORTS 5% BENEFICIAL OWNERSHIP OF $IREN!
A new SEC Schedule 13G filed on November 16 reveals that Susquehanna-affiliated entities report 20.4 MILLION shares in beneficial ownership of IREN.
Here's what caught my attention:
📌 Reported beneficial ownership: 20,402,179 shares
📌 Reported ownership: 5.0%
📌 Filing date: November 16, 2026
📌 Ownership event date: September 30, 2026
The previous February filing reported approximately 13.95M shares.
That's a difference of roughly 6.45M shares in reported beneficial ownership.
BUT here's the important detail:
Susquehanna Securities' reported position includes 17.98M shares underlying options. Other affiliated entities also report option positions.
So this is NOT proof that Susquehanna purchased 6.45M shares outright.
Still, a reported 5% beneficial ownership position is significant and worth watching.
While retail investors debate every dip in $IREN, major financial institutions have substantial exposure to the name.
I'm keeping my eyes on the bigger picture. 👀🚀
Are you still bullish on $IREN?

🚨 SHORTS KEEP SAYING $IREN IS GOING BANKRUPT. BUT HAVE YOU ACTUALLY LOOKED AT THE BIGGER PICTURE?
Let me ask you something.
If IREN is supposedly on the verge of bankruptcy, why are we ignoring what this company is actually building?
I'm not saying IREN has zero risk. Of course it has risks. But calling bankruptcy just because the stock is falling? That's not the same as understanding the balance sheet.
Here's what the bears seem to overlook:
🔥 A massive infrastructure base: IREN reported $20.6B in total assets as of September 30, including $6B in unencumbered data center assets.
🔥 Long-term power advantage: More than 5GW of secured power, plus a development pipeline exceeding 35GW.
🔥 Debt maturity profile: Yes, IREN has meaningful debt obligations. But a substantial portion of its principal is scheduled beyond FY2030. That gives the company time to execute, generate cash flow, and refinance where necessary.
🔥 AI infrastructure opportunity: IREN is transitioning from Bitcoin mining into AI Cloud. Its existing infrastructure and experience operating energy-intensive facilities could become a meaningful competitive advantage.
And here's what I believe:
The market is focused on today's fear. I'm focused on what this business could look like once its AI infrastructure is fully deployed and generating revenue.
Could execution disappoint? Absolutely.
Could financing and dilution remain risks? Yes.
But does that automatically mean bankruptcy?
I don't think so.
I'm not selling just because shorts are trying to scare people out of their positions. I want to see what IREN can become over the next few years.
Who's still standing with me on $IREN?
If you're holding through the noise and believe in the long-term opportunity, drop a comment. I want to know how many brothers are still here. 🤝🚀


Let me tell you why I'm still NOT selling $IREN.
I've watched the ups and downs. I've seen the volatility, the red days, and all the negativity surrounding this stock.
But honestly, I didn't invest in $IREN just for a quick trade.
I believe in what this company is building.
AI infrastructure is a long-term opportunity. IREN has the power capacity, the data center infrastructure, growing AI Cloud revenue, strong customer demand, and a clear path toward becoming a major player in this space.
Are there risks? Absolutely. Execution, financing, and dilution are things we need to keep watching.
But I don't believe every dip means the story is over.
I'm staying patient because I believe the bigger opportunity is still ahead.
And I want to ask you guys something:
Who else is standing with me and holding $IREN?
If you're still bullish and believe in the long-term vision, drop a comment and follow me. Let's see how many brothers are still in this together. 🤝
🚨 $NBIS IS NOT JUST BUILDING DATA CENTERS. IT'S BUILDING THE AI CLOUD PLATFORM OF THE FUTURE.
And its latest move in Europe deserves investors' attention.
🇫🇮 NEBIUS IS A KEY PARTNER OF SLUSH 2026 IN HELSINKI.
The company is bringing its AI Cloud and Token Factory teams to meet startups building the next generation of AI.
But here's why this matters:
NEBIUS WANTS TO POWER THE ENTIRE AI LIFECYCLE.
From training models on thousands of GPUs to running inference at scale, Nebius is positioning itself as the infrastructure layer behind tomorrow's AI companies.
And the numbers are getting hard to ignore:
🔥 Q3 2026 RESULTS:
• Revenue: $980.8 MILLION, up 571% year over year.
• AI Cloud revenue: $973.8 MILLION, up 643%.
• Annualized run-rate revenue: $6.4 BILLION.
• Remaining performance obligations: $38.7 BILLION.
• Token Factory is approaching a multi-hundred-million-dollar annualized run rate less than a year after launch.
THERE'S MORE.
Nebius is expanding beyond traditional GPU rentals:
• NVIDIA Vera Rubin systems are already live and being integrated.
• Nebius became the first AI cloud to adopt NVIDIA Groq 3 LPX for faster inference token generation.
• Its Token Factory is expanding into production AI inference.
• Its platform is adding support for post-training, AI agents and enterprise deployments.
• The company continues targeting more than 1 GW of new capacity coming online annually.
This is the bigger opportunity.
AI demand isn't just about training bigger models anymore.
It's about serving billions of requests, powering AI agents, and running inference efficiently at scale.
Nebius wants to capture more of that spending through one integrated platform.
Yes, execution and data-center delivery timelines remain important risks. But the growth opportunity is massive.
I'm BULLISH on $NBIS because I believe the AI infrastructure buildout is still in its early innings.
If you're following Nebius or holding $NBIS, FOLLOW ME.
Let's keep tracking one of the most interesting AI infrastructure companies in the market. 🚀
Not financial advice.

🚨 ANOTHER DIRECT INSIDER BUY IN $KEEL!
KEEL's COO Liam Daniel Wilson just purchased 28,942 shares at $1.73, investing approximately $50,070 of his own money.
And he's not alone.
🔥 Director Amy Freedman recently bought 40,000 shares.
🔥 Director Edith Hofmeister added another 15,000 shares.
🔥 Multiple insiders are putting their own money behind KEEL.
When company insiders continue buying with their own capital, it's a signal worth paying attention to.
With KEEL advancing its data center infrastructure strategy and positioning itself for the growing AI power demand, I believe the long-term opportunity remains compelling.
Insiders are buying. I'm staying BULLISH on $KEEL. The market may be overlooking what's coming next. 🚀📈

🚨 WHY DOES INTEL OWN $IREN? HERE'S THE STORY.
Intel's latest Form 13F disclosed:
🔥 1,290,365 shares of $IREN
🔥 $52.75 MILLION in reported value
🔥 10.24% of Intel's reported 13F portfolio
But here's the interesting connection:
Intel Capital previously invested in Mirantis, the cloud software company acquired by IREN.
When IREN completed the acquisition, Mirantis shareholders received IREN shares as part of the deal consideration.
That means Intel's IREN position originated from its earlier investment in Mirantis — rather than necessarily being a direct bet on IREN's stock.
And look at what this brings together:
$INTC — semiconductor technology.
$IREN — AI infrastructure, GPU computing and AI Cloud.
Mirantis — cloud software and orchestration.
The AI ecosystem is becoming increasingly interconnected.
I'm bullish on the long-term potential of BOTH $INTC and $IREN. The AI infrastructure opportunity is bigger than the market may realize. 🚀📈

🚨 THE MARKET MAY BE MASSIVELY UNDERVALUING $IREN.
Blackstone just agreed to a roughly $5 BILLION deal involving 647MW of Amazon-leased data center infrastructure.
That's approximately $7.7M per MW.
And what does that get you?
🏗️ Land, buildings and grid connections.
❌ No GPUs.
❌ No AI Cloud business.
❌ No computing revenue.
Now look at $IREN.
🔥 480MW targeted for 2026 capacity.
🔥 1,210MW of AI Cloud capacity targeted for 2027.
🔥 $4B+ in contracted ARR, fully funded.
🔥 $20.3B revenue backlog.
🔥 5GW+ of secured power.
🔥 NVIDIA strategic partnership.
Apply Blackstone's implied infrastructure valuation to IREN's planned capacity:
• 480MW = approximately $3.7B
• 1,210MW = approximately $9.3B
And that's before assigning any value to IREN's GPUs, AI Cloud business, contracted revenue or future growth.
The comparison isn't a formal valuation — but it raises a serious question:
How can a company with IREN's infrastructure AND AI Cloud potential be valued so cheaply by the market?
I believe the market is overlooking the full value of what IREN is building.
$IREN remains one of my strongest long-term AI infrastructure convictions. The upside could be enormous. 🚀📈

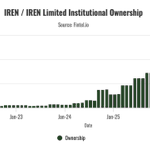
🚨 While retail investors are panic selling $IREN, smart money is quietly buying the dip.
The market sees volatility. Institutional investors see the long-term opportunity in AI infrastructure, massive power capacity, and IREN’s growing AI Cloud business.
When the crowd is running for the exits, smart money may be positioning for what comes next. 👀📈🔥

⚡️🚨 JUST IN: BERNSTEIN REITERATES OUTPERFORM ON $IREN WITH A $55 PRICE TARGET!
That's approximately 203% POTENTIAL UPSIDE based on the November 5 closing price of $18.03. 📈
Despite recent volatility, Bernstein continues to see significant long-term value in IREN's AI infrastructure, power assets and customer prepayments.
The market is focused on short-term uncertainty.
I'm focused on the bigger opportunity.
NOW LET'S SEND $IREN! 🚀🔥

🚨 $NBIS IS DOWN 60% FROM ITS HIGH. BUT HAS THE LONG-TERM STORY REALLY CHANGED?
Bears keep pointing to the drawdown. I'm looking at what Nebius is building.
Yes, the New Jersey delay was a setback. But let's understand what actually happened.
A third-party infrastructure provider retired temporary power before the replacement fuel-cell capacity was ready. Some contracted capacity has been pushed into 2027.
The important part? The Microsoft contracts remain in place.
Now look at the bigger picture:
🔥 Demand is still outpacing available capacity.
🔥 Customer prepayments now cover more than 100% of the associated CapEx on Q3 deals.
🔥 Nebius AI Cloud delivered a 53.2% adjusted EBITDA margin in Q3.
🔥 New-deal payback improved from 22 months to just 19 months.
🔥 Management expects $12–13B in 2027 revenue.
🔥 Pre-tax break-even is targeted by Q4 2027, despite planned CapEx of $40–45B.
And what about the $325M in asset-light revenue?
Management classified it as non-recurring revenue from the initial rollout phase. But it also expects these activities to become a more regular part of the business as its partner footprint expands.
That's an important distinction.
Nebius is building multiple ways to monetize AI infrastructure — through owned capacity, partner-funded deployments and its cloud platform.
Management has also described its 2027 revenue outlook as conservative, while expecting 75–85% of 2027 CapEx to be covered by customer prepayments and asset-backed financing.
Of course, execution, financing and dilution risks remain. A $40–45B investment plan is enormous, and the company still has to deliver.
But I'm not investing based on where the stock traded at its peak.
I'm watching demand, pricing, customer commitments, margins and capacity expansion.
I don't need Nebius to be profitable today. I need to believe it can execute the plan and turn today's demand into tomorrow's earnings.
I would rather evaluate the business before the market fully prices in that transformation.
I'm holding $NBIS and believe the long-term opportunity remains significant. 🚀
