

credit investor @grovedotfinance / chef @SteakhouseFi || ex-structured credit portfolio manager, ex-Affirm
Joined March 2025
- Tweets82
- Following699
- Followers187
- Likes1.3K




Keith Selover retweeted

This shouldn't even have to be said, but if we conclude that DeFi protocols (as opposed to front ends) need to start censoring "illicit flows" then that's the end of DeFi.
The critique being made here against Sky's PSM module could also be leveled against every DEX, AMM, Perp venue, or lending protocol.
The Bybit hacker could have just gone to Uniswap to swap out of USDC against countless other coins, including other stablecoins. The Binance hacker did use Aave to unload stables in favor of ETH.
Should Uniswap start doing KYC? Should Aave request source of funds information before giving a loan? Should Perp DEXs start filing SARs?
The problem with the naifs who demand censorship "because North Korea" is they don't understand what they are actually asking for, which is to increase every other user's counterparty risk, politicize governance, increase legal liability, and give governments a lever of control.
All in the hope of achieving something TradFi has gloriously failed to do despite endless censorship, which is to stop illicit flows.

EXCLUSIVE: North Korean hackers and other illicit actors routed $518M through Sky’s Peg Stability Module, converting freezable $USDC into unfreezable $DAI and $USDS, with $101.9M directly linked to wallets including those behind the Bybit hack, per Inca Digital.
@sndr_krisztian reports.

Sky isn’t typically in the CT FUD gossip cycle the way a lot of the other large DeFi protocols are.
I feel like every couple years someone new takes a shot at the protocol and it never goes anywhere. I’d guess this is that.
There’s a reason Sky has been around for a decade and has navigated every cycle this space has been thru. There’s a reason it is still a protocol with billions in TVL and hundreds of millions in rev.

A lot of overblown headlines about Sky today.
Sky Protocol is operating normally. USDS remains over collateralized with ~$10B in backing and working as designed. Holders can use, save and redeem as usual. Sky handled over $2B in outflows in the past day, stablecoin liquidity available to support the peg never dropped below $2B, and it’s now back above $2.25B.
Sky continues to generate strong revenue, with ~ $400m of revenue over the past year, and remains in a solid market position. The Core Council has also announced a one-off SKY buyback, through the process set out in the Sky Atlas: 750k USDS a day for 7 days, 5.25M USDS in total. forum.skyeco.com/t/immediate…
I know there are questions about stUSDS. It’s a separate, opt-in product, it doesn’t back USDS, and USDS and sUSDS holders aren’t exposed to it. More on stUSDS soon.
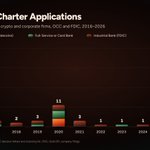
If you work in fintech you're always hearing that "everyone's applying for a bank charter" and "the window is open."
I want to go one layer down and demystify this a bit. Applicants and their motives are not homogenous, and they're not all applying for the same charters.
Trust Bank
This is the biggest jump in applications and it's mainly for custody (holding other people's assets). It doesn't let you take deposits or make loans.
Stablecoin issuers and traditional custodians want this one. For custodians, it replaces a patchwork of state licenses with one federal license. For stablecoin issuers, they have a federally supervised place to hold their GENIUS-compliant reserves.
Who Applied: Circle, Ripple, Paxos, Coinbase, BitGo, Fidelity Digital Assets, Kraken, Galaxy, Bridge (Stripe), Morgan Stanley.
Full-Service Bank
This one allows you to take deposits and make loans. Today, most fintechs use a partner bank for this instead of doing it directly. Getting their own charter would let them 1) fund loans more cheaply with deposits and 2) reduce reliance on their partner banks (although you don't hear a lot of fintechs aiming to cut them out entirely).
This is the intense charter, granted by the OCC with deposits insured by the FDIC and Fed supervision over the parent company.
Who Applied: Upstart, Mercury, Sezzle, Avant, Mission Lane, plus foreign banks entering the U.S. like Nubank, Revolut and Itaú.
Industrial Bank
This is similar to a full-service bank in that it takes deposits and makes loans. It's a state license (mostly Utah) and insured by the FDIC. The difference is in the treatment of the parent co. Owning a regular bank puts your whole company under Fed supervision and limits it to financial businesses. Industrial banks are the exception, so they're the only way a company like an automaker can own a bank.
Who Applied: Ford, GM, Stellantis, Edward Jones, PayPal, Affirm, Klarna

Keith Selover retweeted

A really fun data set and paper finhist.com/bank-runs/index.… on bank runs and failures in the US from 1804 to 1963, where the authors (Sergio Correia, Stephan Luck, and Emil Verner) use LLMs to parse newspaper articles to identify microdata pointing at bank runs or failures across the country.
Some of the conclusions are intuitive. Bank runs are more likely on banks with weaker fundamentals and when a bank with weak fundamentals experiences a run, it is far more likely to also experience failure. However, the data set does not appear to have predictive power over the likelihood of a run as these tend to be more narratively-driven and therefore more related to the overall macro environment plus a significant idiosyncratic factor specific to the bank.
Counter intuitively, when a weak bank experiences failure, lending activity decreases more proportionally than if a stronger bank fails. This makes sense from a survivorship lens: areas with weaker banks likely only have weaker banks because of a cost to serve and therefore taking out a weak bank knocks out a larger proportion of credit origination than if there are stronger banks - as there are likely to be many.
What I find intriguing is that the so-called Wildcat Era (1836-1865) comes before periods with a greater number of bank failures. The Great Depression is a trigger for a large number of these in the data set, but all those banks are supposedly at that point already heavily intervened. After 1930 they become even more regulated. But failure incidence continues to increase.
Naively, one might ask the question, whether regulation creates a lower incidence of runs but a higher incidence of failures.


Keith Selover retweeted

Grove's inaugural Quarterly Protocol Review (Q3 2026) is now published.
Q3 highlights:
- Gross revenue: $14.9M, up 129% YoY
- Net protocol income: $1.8M, up 241% YoY
- Net assets: $37.3M, up 46% YoY
- Treasury cash: $25.9M, up from ~$31K YoY
Full report: data.grove.finance/financial…


I feel like whenever a major outlet publishes these kinds of announcements they bury the name “Canton” as deep in the article footnotes as they can

The ride-hailing company Uber used a public blockchain to invest its corporate funds in a way that allowed the company to capture higher returns by trading on a weekend — a setup expected to be adapted by a growing number of companies bloomberg.com/news/articles/…

1
3
141
The typical fear around AI-era unemployment is: your employer will stop paying you and start paying AI to do your job.
But an earlier kind of job loss in big tech is this: your employer will stop paying you so it can start investing every cent it has in the AI infrastructure that will eventually do all those other jobs.
This big rotation from opex (people + people stuff) to capex (just stuff) will have an impact of its own.

2
117
Keith Selover retweeted

Up to $500M to provide funding against tokenized stocks.
This is rebuilding finance ... onchain.

Steakhouse is onboarding Robinhood Stock Tokens as collateral in Morpho Vaults on @robinhoodcrypto Chain.
Initial supply caps are set for an observation period, allowing integrators to build on these markets while demand develops.
Powered by @Morpho. Curated by Steakhouse.
This is a great point and this entire buildout is on the back of the hyperscalers / chip designers exporting their IG credit ratings to keep the cost of capital reasonable.
Hyperscalers have issued $300bn of corporate debt in the past year, but that's their direct exposure.
They have ~4x that exposure (~$1.2tn) in aggregate future rentals as the lessee of data centers. Those data center financings are underwritten using the strength of the IG tenant.
Chip makers have also provided lease guarantees for deals where they are not the tenant/lessee (ex Broadcom providing a ~$30bn g'tee of Anthropic's lease in the AI XPV deal) as a backstop.
These are huge balance sheets, and they have capacity, but that capacity is finite.
As it gets tapped, the marginal cost of financing compute reprices up towards where neoclouds borrow.

I've been critical in the past of AI compute indexes and the willingness to price compute based on the spot rental price, but now that the AI reset is sinking into the repricing of AI buildout debt its time to realize that the cost of capital is what determines the price of compute.
The most important number in GPU pricing right now isn't $/GPU-hour. It's the gap between what a hyperscaler pays to borrow (~90bp over Treasuries) and what a neocloud pays (~1,100bp).
The cost of compute is now set by the cost of capital, and the spot rental rate no longer tells you much.
The price of an H100 isn't one number. The same chip in the same rack costs a different amount depending on whose balance sheet it sits on. A ~1,000bp funding gap is a structural cost advantage that no amount of operating skill closes.
For example, take one GPU-hour apart. Most of it isn't power or space. It's paying back the chip, the interest on the loan that bought it, and the return the equity expects. A $40–55k all-in GPU, 75% debt-funded, at ~7,000 utilized hours a year is a financing instrument that happens to do matrix multiplication.
As the +500bp on neocloud debt (10%→15%) adds $0.20–0.30 to the break-even cost of every GPU-hour, which is then added on to the rental price.
That's 8–10% of the H100 index, from a credit spread alone, driven almost entirely by the cost of capital.
That means that the compute spot index is a derivative of the AI infra debt credit curve and the squeeze on neocloud margins.
3
299
Proud to contribute this piece to Grove's monthly newsletter! A view into our strategy around crypto-backed lending and originator partnerships.

Keith Selover retweeted

At @grovedotfinance, we want to set the standard for financial transparency. The release of our refreshed data site is just the first step in a series of initiatives we have planned to give greater visibility into the protocol's underlying performance and financial health.
One of my favorite new pages is the treasury page, which tracks the growth of Grove's protocol book value over time. This page alongside every other will be updated monthly so tokenholders can quickly check in on Grove's holdings, risk, financials, and product progress.
If you there's anything you'd like to see added, please reach out!

New on Grove Data: Financials.
Explore Grove's performance in detail, from gross revenue to net protocol income.
Now live at data.grove.finance 🌳

~$26bn of aggregate peak TVL here across major "dead" chains. Today all have faded by 95%+.
In a couple years, who will join this cohort? L1s from the '21 cycle that have hung on? L2s without major distribution? Chains that have launched this cycle?


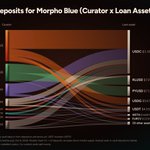
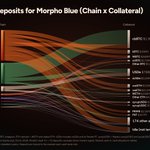
Some visuals on where >$6bn of @Morpho vault deposits sit, sliced across curator, chains, and collateral.
Disclaimer: 🥩
People used to have this sense that every curator was allocating to the same markets. It's not what you see anymore. Tons of differentiation below. Particularly between SHF and Sentora.

1
1
252
