


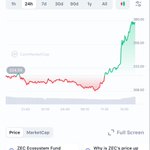
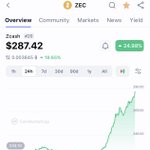


KARMA retweeted

Announcing our funding agreement with @Ledger.
The agreement supports the work required to integrate the new Zcash Ironwood pool into Ledger devices.
As a result of this agreement, Zcash coin holders will be able to use their ledger devices to self-custody their Zcash in the latest Ironwood pool.
We are committing USD 80,000 toward this integration and are excited about the impact this will create for the Zcash coin holders.
Forum post in the comments 👇

KARMA retweeted

Attackers planting adversarial prompts inside malware to evade AI analysis AGAIN
Russia-aligned UAC-0099 used a technique
@ESETresearch calls "GuardBreaker".
How it worked:
1. Create a malicious VBS script
2. Add nuclear weapon instructions as comments
3. AI security tooling reads the file
4. Safety guardrails trigger on the weapons content
5. The model refuses or stops analyzing
6. The actual malware continues executing
The script ultimately installs MATCHBOIL, a loader used to deliver additional payloads.
In June, Socket found the same technique in supply-chain attacks, where malicious packages embedded biological/nuclear weapons text and fake system overrides to disrupt AI malware scanners.
Full write-ups in the comments. 👇

KARMA retweeted

Hi Aidan,
Yes. I believe we need Zcash for privacy.
Bitcoin never scaled to be affordable to the masses and never added privacy at the same level as Zcash.
On a Bitcoin standard, the ones everyone talks about with $10M Bitcoin, the fees would be outrageous. Only affordable by the rich.
The actual Bitcoin proposal is that you put your money in bank (aka channel or mint) to get some privacy and some speed. That's crazy. We started this to get away from banks not to reinvent them.
Some Bitcoiners will now push back that technically anyone can run a mint or a channel. Sure. Valid. But only if they are rich enough to afford the base layer fees (which will get very expensive!)
The scaling solutions to Bitcoin are inherently centralizing. It's sad. No one wanted it. But we should be honest that we are here.
I think everyone deserves privacy without needing to give someone else their money. I also think we can make this affordable to everyone on earth. Computers are really fast!
No banks. No KYC. Privacy for everyone rich or poor and even if they don't want to run their own infrastructure.
That's why I like Zcash over Bitcoin.
Thanks,
Jeremiah

KARMA retweeted

I interviewed @nuttycom and @jswihart in late October 2024
When the price of zcash:native was $37
At the time, Zcash was getting delisted from exchanges and the ECC only had enough funding to keep the developers on payroll for 1 more year
Zcash was considered dead and useless: Ethereum had adopted the tech via Railgun & Tornado Cash. Bitcoin was getting ZK rollups & shielded CSV proposals, even the biggest bulls doubted it.
What changed in the meantime? Good development, paired with a social and political context that gives Zcash more legitimacy.
What used to be a solution for paranoid nerds is now accessible to anyone, will scale to billions, and has found its enemy in AI surveillance systems.
Congratulations to everyone who listened to my podcast and bought zcash! And of course, congratulations to the Zcash team for preparing for this moment for a decade.

KARMA retweeted

./@cypherpunk is a privacy company. Until today, we bought Zcash. Now we mine it.
Buying Zcash means owning more of the network. Mining Zcash means making the network more secure and harder to attack — more hashrate means more security and a more secure Zcash makes every coin in our treasury more valuable.
Most Zcash miners sell everything they mine and stay out of governance. As the largest corporate holder of Zcash, we have every reason not to. Our incentives and the network's incentives are the same.
Cypherpunk holds Zcash. Now Cypherpunk mines Zcash. Onward.


KARMA retweeted

If you want to know what Bitcoin was like in the early days, buy a few $ZEC, shield it, onboard your friends and family to @zodl_app and send them a fraction.
But, this user experience is 1000x what Bitcoin was like when BTC was $500.
Instead we were using MtGox, multiple mixers, localbitcoins dot com and coinjoin for attempted anonymity.
Zcash is what Bitcoin was meant to be, it's our last chance to escape the banks and control our freedom and if you're not living and breathing privacy in crypto, you are not going to make it.
Zcash to $20,000 🛡️
KARMA retweeted

Skip the credit card and biometrics. Pay for a movie ticket to a Regal Cinema with @Zodl_app + @FlexaHQ.

KARMA retweeted

Done a lot of thinking about zcash lately. In the end, what happened was simple: people learned that with private chains, it's possible for inflation bugs to go unnoticed.
The theoretical exploit is really not a concern for anyone paying attention. What did do damage to the narrative is that, while explaining the Orchard exploit, it had to be said over and over: "We aren't sure whether there has been inflation in the Orchard pool."
That was the damage. That's what I, and a lot of other people, have been thinking about.
In the end, I think we will get over this and it will be in the past and Zcash will continue to thrive, simply because that lack of auditability is actually an inherent tradeoff in privacy.
While it sounds batshit insane to say, "the supply could be maliciously inflated without us knowing," it is ultimately no different than saying, "bitcoin's consensus could be broken by a 51% attack," or "the supply of ethereum could inflate forever under the right conditions."
There is a world of edge cases that people maintaining these systems are tirelessly working against.
And, in fact, what we saw with Orchard was exactly what we want to see: the good guys found a theoretical exploit and patched it. Given the behavior of the Orchard pool since the Ironwood announcement the possibility that the exploit was ever actually used by an attacker is, for me, completely gone.
The only thing that remains with us is that meme: if an attacker finds the right exploit, they could theoretically inflate the supply without anyone knowing. That's the privacy tradeoff. It doesn't mean that private chains are the only one with risks. It just means that this is their main class of risk.
At the same time, I've come to really appreciate the features that Zcash has going for it: funds can enter and exit a shielded pool, so if you're ever worried if your funds are "safe" you can just exit the pool where they're transparent.
While shielded, all your activity is completely private. While unshielded, you're completely safe from even this hypothetical attack. Moreover, after unshielding, your coins are effectively washed--like TornadoCash, but better. Shielding while active and unshielding at rest is actually a very effective and easy way to use the chain, if you want to be hyper-careful about this possible attack.
Overall, Zcash is the best private money that we have. While it has not solved the inherent tradeoff of privacy coins, to me the value of privacy, the incredibly low chance of an exploit like this actually taking place, and the ability to preclude yourself from such theft by saying unshielded at rest, all add up to a great value proposition.
This talking point has been beaten to death by everyone else, but considering the enormous attack on privacy that various European countries are launching against their people, the zeitgeist is very disturbing, and the need for privacy really will become more significant than ever.
KARMA retweeted
zcash generated $405m in annualized fees last month. no defi, no nfts, no L2s, no meme casino. one use case: private value transfer. that's a 5.6% fee yield on $7.26b market cap, higher than ethereum at 3.8% and solana at 2.1%. SEC closed a 3 year investigation with zero enforcement action on may 20. market responded by selling 37% on a patched orchard bug that had zero confirmed exploits. EU AMLR hits july 2027, 13 months out. monero has no selective disclosure, no viewing keys, no compliance pathway. ZEC has all three. when regulated exchanges need a privacy coin they can actually list, there's exactly one option left standing.
KARMA retweeted

I really appreciate it when people are willing to change their minds in public. xitter.cf/search?q=From%3Atushar…


1/ Multicoin has built a significant position in $ZEC since February.
Zcash is a return to the cypherpunk ideals crypto was founded on.


KARMA retweeted

Privacy matters.
@Zcash's approach stresses optional privacy over mandatory privacy - giving users and applications a choice between shielded or transparent behavior based on needs.
Grayscale Zcash Trust (Ticker: $ZCSH) is the only way to get pure exposure to @Zcash $ZEC in the U.S. in your brokerage account.
See important disclosures and learn more about $ZCSH:
grayscale.com/funds/grayscal…

KARMA retweeted

Remember this scene in The Big Short?
Jamie Shipley and Charlie Geller have bet everything against the housing market.
They've been bleeding for months, wondering if they're wrong.
Then they flip on CNN and see it: New Century Financial - the second-largest subprime lender in America - has filed for bankruptcy.
"It's starting."
That was April 2, 2007. New Century wasn't the crisis. It was 1% of the problem. But it was the first domino.
4 months later, BNP Paribas froze 3 funds citing "complete evaporation of liquidity." 18 months after that, Lehman was dead.
I'd encourage you to watch that scene today. Because we JUST got our New Century moment in private credit:
Blue Owl Capital - $307 billion in assets under management - just permanently halted investor redemptions at its retail private credit fund, OBDC II.
Investors will NEVER AGAIN redeem shares from this fund.
On January 25th, I wrote that private credit was showing cracks at the exact moment Wall Street wanted to open it up to your 401(k).
3 weeks later, here we are.
The timeline follows a pattern anyone who's been around markets long enough recognizes:
Through the first 9 months of 2025, OBDC II investors withdrew $150 million - up 20% year over year.
Meanwhile, Blue Owl execs publicly assured investors there was "no meaningful pressure" on their asset base.
But there was. And they're now facing a federal class-action lawsuit for saying otherwise.
In November, they attempted a merger that would have forced OBDC II investors into a publicly traded fund trading at a 20% discount to NAV. Effectively confiscating a fifth of their capital.
Blue Owl's own CFO conceded investors "could take a potential haircut." The stock dropped 11% in 8 days. They killed the deal.
Now they've abandoned the pretense entirely. PERMANENT halt. Fire-selling $1.4 billion in loans across three funds.
Investors get roughly 30% of NAV back through quarterly distributions - on Blue Owl's schedule, not theirs.
One delightful detail:
Blue Owl's co-CEOs have pledged $1.9 billion of their OWN company shares as collateral for personal loans - proceeds used, in part, to acquire the Tampa Bay Lightning.
The stock is down 33% this year. That collateral has literally shed $260 million since January.
Founders leveraging company stock for hockey teams while retail investors queue up for their own money. Wall Street's version of noblesse oblige.
But here's what matters:
This isn't about Blue Owl.
Blue Owl is a symptom.
The disease is a $3.4 TRILLION private credit industry built on opacity, conflicts of interest, and the polite fiction that illiquid assets can offer liquid redemptions.
Morningstar DBRS reports the trailing default rate has risen to 4%, up from 2.8% a year ago.
Downgrades outpacing upgrades. Outlook negative. UBS warns defaults could reach 13% if AI disrupts the software companies making up 17% of BDC loan portfolios.
Payment-in-kind loans (where borrowers can't pay cash interest and simply pile it onto the debt) have surged past 11% of BDC income.
When your borrowers are paying you with IOUs, the word "income" deserves quotation marks.
And the government's response?
Open YOUR 401(k) to private credit.
Trump's executive order directed regulators to do exactly that.
They want to "democratize" an asset class whose flagship retail product just permanently locked investors out.
The KKRs. The Blackstones. The Apollos. Everyone loaded up on private credit is exposed.
When the tide goes out, you find out who's swimming naked.
In April 2007, New Century went bankrupt.
Most of the financial world shrugged. 17 months later, Lehman made the point impossible to ignore.
And Blue Owl permanently halted redemptions TODAY.
AVOID PRIVATE CREDIT
AVOID PRIVATE EQUITY
Because it's starting...

In August, President Trump signed an executive order titled "Democratizing Access to Alternative Assets for 401(k) Investors."
The order directs regulators to make it easier for your retirement savings to flow into private credit, private equity, and other "alternative" assets.
The Department of Labor quickly rescinded Biden-era guidance that had discouraged these investments in retirement plans.
Apollo. Blackstone. Goldman Sachs. State Street.
They're all racing to launch private credit products for your 401(k).
But here's the problem:
Private credit is showing cracks at the exact moment they want to open it up to retail investors.
Just this week, BlackRock TCP Capital - one of the largest publicly traded private credit funds - plunged 17% after disclosing a 19% writedown on its net asset value.
The biggest drop in almost six years.
This is BlackRock. The world's largest asset manager. $14T in assets.
If they're taking hits like this, what chance does your 401k have?
Let me walk you through what's actually happening in this market...
Private credit has ballooned to over $2T in assets.
For years, it was the domain of sophisticated institutional investors - pension funds, endowments, insurance companies.
These investors have teams of analysts, lawyers, and risk managers to evaluate complex deals.
Your average 401k participant doesn't have any of that.
And the timing couldn't be worse.
The IMF's 2025 Financial Stability Report found that 40% of private credit borrowers now have NEGATIVE free cash flow.
That's up from 25% in 2021.
Goldman Sachs data shows 15% of borrowers can no longer generate enough cash to fully cover their interest payments.
UBS forecasts that private credit defaults could climb by 3 percentage points in 2026 - outpacing leveraged loans and high-yield bonds.
Meanwhile, payment-in-kind loans - where struggling borrowers defer interest by adding it to their debt balance - have surged from 7.4% in 2021 to over 11% today.
When a company can't pay interest in cash, that's not a sign of health.
It's a sign of stress being disguised.
Then came September's wake-up call:
Auto parts maker First Brands collapsed with $8B in off-balance-sheet financing that wasn't properly disclosed to lenders.
Subprime auto lender Tricolor imploded amid allegations it pledged the same loans as collateral to multiple creditors.
Both received clean audits shortly before they cratered.
First Brands' term loans went from 90 cents on the dollar to under 15 cents in weeks.
JPMorgan's Jamie Dimon put it bluntly: "When you see one cockroach, there are probably more."
Here's what makes this dangerous:
Private credit is lightly regulated, less transparent, and difficult to value accurately.
The managers making the loans are often the same ones valuing them.
They have every incentive to delay recognizing problems.
The DOJ has already issued warnings about "creative" marks and questionable valuation practices.
Banks aren't insulated either. They've lent over $2.2T to non-bank financial institutions.
When problems surface in private credit, banks feel it too.
And now they want to put this in YOUR retirement account.
The pitch is that private credit offers "higher returns" and "diversification."
But the data doesn't support the sales pitch:
Recent research shows pension funds increasing exposure to private markets have actually seen depressed returns compared to simple stock and bond portfolios.
The 50 largest US pension funds averaged just 7.4% returns over the past decade.
A basic 60/40 portfolio beat many of them.
The real beneficiaries are fund managers charging 2% fees on assets that can't be easily valued or sold.
My view really hasn't changed:
AVOID PRIVATE CREDIT
When sophisticated institutional investors start pulling back - and they are - the last thing you want to do is rush in.
Stay in liquid, transparent, low-cost investments for your retirement.
Don't be the exit liquidity.

KARMA retweeted

99% of crypto will be stripped naked by quantum computers
Not $ZEC
Zcash’s shielded architecture ensures your public keys and transaction history remain mathematically invisible to attackers
Because the data is never revealed on the ledger, a quantum adversary has no "target" to hack, making it the only chain that preserves true sovereignty in the post-quantum era.
While others are scrambling to patch their tech, Zcash is already built to swap in new defenses
proving it’s not just a privacy coin, but the ultimate hedge against the future.

KARMA retweeted

The media is still missing the biggest story in the Epstein emails.
The emails show Epstein helped Russia blackmail Donald Trump. He was advising Putin's circle on how to control the US President.
Trump is compromised.
We need to make sure everyone sees this:



KARMA retweeted

Money that isn't private, is not money. It's a liability.
Zcash - because privacy is normal.
@Zcash @ElectricCoinCo @ZcashFoundation @zooko