

@JohnnyNorthstar
Account based inUnited States
About this account
- Account based in
- United States
- Connected via
- United States App Store
Account-level information from X, not a live location or the device used for a specific post.
Finding trades the crowd hasn't discovered yet. AI. Macro. Options. Real positions. Lawyer by training. Trader by choice. Not financial advice.
NYC/NJ
Joined October 2012
- Tweets26K
- Following1.4K
- Followers2.1K
- Likes26.6K





Pinned Tweet
Lawyer by training. Trader by choice.
The playbook:
• Watchlist I know cold
• Wait for risk/reward to flip in my favor
• Strike with disciplined stops
• Book the asymmetric move
No hype. Just my reads.
LFG 🚀
Hims & Hers ($HIMS) officially launched its Hers women's health platform in Australia, rebranding its existing Juniper service and expanding treatment offerings across weight management, hair regrowth, menopause and perimenopause.
* Market expansion: The launch follows Hims & Hers' acquisition of Australian telehealth company Eucalyptus earlier this year and the August rebranding of its men's health platform, Pilot, to Hims.
* Treatment programs: Hers offers personalized weight management, new hair-regrowth formulations and hormonal health services, supported by medication access, nutrition and fitness guidance, and 24/7 care teams.
* Women's health support: Its digital weight-loss companion draws on more than 20 peer-reviewed studies focused on women's needs. Patients can request female practitioners and access a community of over 27,000 women.
* Growth opportunity: Australia's telehealth market is projected to expand from approximately $542 million to $2.56 billion by 2034.
* Existing patients: Juniper patients will retain their current Australian practitioners and care teams while gaining access to expanded services.

$INTC has begun customer sampling of its new D-Series GPUs, formerly codenamed Crescent Island, expanding into AI inference as demand grows for infrastructure supporting autonomous AI agents.
* GPU design: D-Series processors are designed to run trained AI models and services. Unlike Nvidia’s ($NVDA) Blackwell server configurations, Intel’s new GPUs use PCIe expansion cards.
* Industry partners: Intel is working with ASUS, Hewlett Packard Enterprise ($HPE), Dell ($DELL), Supermicro ($SMCI) and other hardware manufacturers and cloud providers to develop D-Series systems.
* Agentic AI demand: Intel is also benefiting from renewed CPU demand as AI agents increasingly perform tasks such as database searches, website navigation and application management alongside GPU-powered AI models.
* Competitive landscape: Intel faces growing data center competition from AMD ($AMD), Nvidia’s Arm-based Grace CPUs and Qualcomm’s ($QCOM) expanding processor and AI accelerator portfolio.
* Stock performance: Intel shares have gained approximately 183% YTD and 175% over the past 12 months, with much of the rally attributed to renewed demand for its CPUs.
* Deployment status: D-Series chips are entering customer sampling, not confirmed widespread commercial deployment. Intel has not provided production volumes or revenue projections in the supplied material.

$SPCX's planned acquisition of low-band wireless spectrum is fueling speculation about a potential merger with $TSLA, with Pivotal Research suggesting the assets could support a dedicated communications network for Tesla vehicles, robotaxis and robots.
* Wireless expansion: The spectrum announcement sent AT&T ($T) and other telecom shares down 8%–14%, although analysts note SpaceX still lacks the spectrum holdings and terrestrial infrastructure needed to compete directly with established carriers.
* Tesla connection: Pivotal analyst Jeff Wlodarczak believes SpaceX could develop a private wireless mesh connecting Teslas, Cybercabs, robots and other devices, with Starlink customers potentially expanding network coverage.
* Merger speculation: Both companies are investing heavily in AI and collaborating on a major semiconductor fabrication project in Texas. Musk's control of both businesses has also fueled merger discussions.
* Analyst outlook: Wlodarczak rates SpaceX Buy with a $220 price target but does not cover Tesla. His network proposal remains an investment thesis, not an announced company strategy.

Two -10% days on my watchlist. Two very different charts. 👇
$CBRS -10.2% to $147.51
Fresh all-time low on 2x normal volume. Now 20% below its $185 IPO price and 62% off the first-day high. This is a stock still looking for a floor.
$LITE -10.6% to $986
Closed Friday within 4% of its 52-week high, and it’s still up more than 6x from the low. This is profit-taking in a leader that just lost $1,000.
Same percentage, opposite setups. One is a broken IPO. The other is a pullback in an uptrend.

$META is reportedly preparing a new AI model called Muse Wonder, with a circulating screenshot showing two versions designed for coding, advanced reasoning and multi-step autonomous tasks. The model and its availability remain unconfirmed.
* Muse Wonder: Screenshot describes a 1-million-token context window, six reasoning levels, native tool calling, MCP support, long-task planning, sub-agent delegation and error recovery.
* Reported pricing: $4 per million input tokens, $0.20 for cached input and $20 for output.
* Muse Wonder Full: A maximum-reasoning version designed for more complex tasks, with higher latency and cost.
* Subscription access: Screenshot lists Wonder Full as exclusive to MuseCode Power Usage and Maximum Usage plans, while showing a playground option for standard Wonder.

The index says nothing is happening. The tape says otherwise. $QQQ $SPY
Two hours in: 👇
Dow +0.44%
S&P 500 -0.04%
Nasdaq -0.32%
Russell -0.20%
Under that flat S&P, the AI trade is down 4–7% across optics, memory and neocloud.
And my leadership board is seven names with nothing in common:
$ASTS +5.2%
$META +4.4%
$SHOP +3.7%
$TMUS +2.8%
$REGN +2.5%
$DE +2.0%
$CRM +2.0%
Dow green, growth red, leaders scattered. That’s rotation, not strength.
I'll let this market come to me.
$MU 4% to $988 and back under $1,000.
The catalyst: China’s CXMT flagged progress on a denser memory design. Same fear that hit the stock in July: more supply, lower prices.
The other side: the board just lifted the buyback ceiling to $35B, and the stock trades at 13x trailing earnings.
Levels I’m watching: 👁️👁️
• $957–985: 50/100-day cluster, being tested now
• $925: last month’s low
• Reclaim $1,000 and buyers are back in control
A flush to $750–800 would trigger buying from me. Until then, patience.
Not a recommendation. Just my trade.

Goldman Sachs $GS upgraded its outlook for stocks and bonds, recommending overweight equities over the next three months and increased exposure to longer-dated bonds over the next year, citing strong earnings growth, improved valuations and a favorable economic outlook. 🔥
* Stocks: Strategist Christian Mueller-Glissmann expects corporate earnings growth and lower valuations following the recent market selloff to support equities through Q3 earnings season.
* Earnings expectations: FactSet estimates nearly 30% year-over-year S&P 500 earnings growth in Q3. Six major U.S. banks and UnitedHealth $UNH are among companies reporting this week.
* Bond opportunity: Goldman upgraded longer-dated bonds after rising yields made them more attractive for investors with longer time horizons.
* Economic outlook: Goldman expects inflation to normalize, energy prices to peak and central banks to become more accommodative, despite ongoing Middle East tensions and inflation risks.
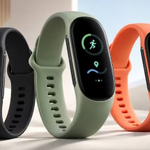
$GOOGL unveiled Fitbit Edge, a $179.99 AI-powered fitness tracker replacing the Charge 6, with expanded health monitoring, improved GPS and personalized coaching. Availability begins October 27. ⌚️
* AI health coaching: Google Health Coach provides personalized wellness guidance, while Health Guardian is described as monitoring blood pressure and insulin resistance trends.
* Fitness tracking: Supports 50+ exercise modes, automatically recognizes 100 workouts and offers up to 40% improved GPS accuracy.
* Health sensors: Includes ECG, continuous heart-rate monitoring and advanced sleep tracking.
* Display and battery: Features a Hybrid OLED display with 46% more viewing area, up to seven days of battery life and five-minute fast charging.
* Pricing: Standard model starts at $179.99; Stephen Curry Special Edition costs $219.99. Includes a three-month Google Health Premium trial.
* Market competition: The launch expands Google's AI-powered wearable offerings, positioning Fitbit more directly against Apple's ($AAPL) health and fitness ecosystem.

$MRVL unveiled its second-generation Structera X 3406 and 3506 memory expansion controllers, designed to increase AI inference performance and memory capacity while reducing infrastructure costs. Customer sampling is expected in Q1 2027. 🔥
* Memory expansion: Six DDR4/DDR5 channels, 50% more than the previous generation, support up to 9TB of DDR4 or 6TB of DDR5 memory per controller.
* AI inference performance: Marvell claims up to 40–50% faster time to first token, 2x longer context windows at equivalent latency and 2x higher query throughput for recommendation workloads.
* Memory efficiency: Built-in LZ4 compression delivers up to 2–3x more effective memory capacity, with 250GB/s compression throughput, 5x the previous generation.
* Industry partnerships: AMD ($AMD), Arm ($ARM), Alibaba ($BABA), Samsung and SK hynix are collaborating on CXL integration and memory validation.

Sharp $ONDS breakdown, and the numbers hold up: $83.8M Q2 revenue, $757M pro forma backlog, $525–550M full-year target. 👇
My answer to his question: the Q3 print. Guidance is $140–155M. Hit it and the backlog is converting. Miss it and the market keeps calling this a roll-up.
On my watchlist. 👁️👁️

When the market looks at $ONDS it sees a pile of acquisitions being built off of shareholder dilution. I see a defense company being assembled in real time without tapping the debt market.
Ondas has a $757 million pro forma backlog with a revenue target of $525 to $550 million for the 2026 fiscal year. I started a position at the end of last week and finished writing a bullish deep dive which will be out tomorrow.
I believe that the acquisitions, customer relationships and $PLTR partnership are beginning to fit together. This combination could become dramatically more valuable over the next five years. Here is the underlying business Ondas is building at a time when autonomous warfare is still in it’s infancy:
· Sentrycs provides cyber-based counter-drone capabilities
· Iron Drone adds physical interception
· DZYNE brings Dronebuster, the ULTRA reconnaissance aircraft and IonStrike.
· World View adds persistent sensing from the stratosphere
· Roboteam adds ground robotics
I see a company positioning itself to detect threats, collect intelligence and deliver responses across multiple domains. Integrating those capabilities could make Ondas more valuable to a customer than any individual product.
Then there is Mistral which was a brilliant acquisition. That acquisition gives Ondas direct prime contractor access to U.S. Army and Special Operations contract vehicles, alongside domestic manufacturing and integration capabilities. Owning that customer relationship matters when you are trying to turn a growing technology portfolio into larger defense programs.
The financial progress is getting harder to ignore:
• Q2 revenue: $83.8 million, up 67% sequentially
• Pro forma organic revenue growth: 85% year over year
• Reported June backlog: $613 million
• Pro forma backlog including DZYNE and Cyberhawk: $757 million
• Full-year 2026 revenue target: $525–$550 million
I will be focusing on the organic growth Ondas can produce because acquisitions alone cannot carry this thesis indefinitely. I want to see the underlying businesses growing while orders convert into deliveries with more cash hitting the cash flow statement.
Palantir is where the longer-term opportunity gets especially interesting. The $PLTR partnership covers manufacturing, mission planning and intelligence processing aboard autonomous platforms. SkyWeaver is being developed to process information closer to the mission and support operations when connectivity is degraded.
My view is that coordinating drones, sensors and ground systems could become one of the most valuable parts of this market. Ondas has an opportunity to participate in that software layer alongside its hardware. A recurring software business would strengthen the economics considerably.
The balance sheet also matters as Ondas ended June with approximately $1.38 billion in cash, cash equivalents and short-term investments, against roughly $6.4 million of debt. Subsequent acquisitions have consumed substantial cash but that starting position gives management room to build.
Equity financing has a real cost as every new share reduces my ownership unless the value created exceeds dilution. I am judging management on whether this acquisition strategy ultimately produces greater earning power per share. You will need to read my article which is forthcoming to see my bull case and price targets.
I will be watching organic growth, backlog conversion, cash consumption and the share count together. My bet is that Ondas can turn this collection of capabilities into a profitable defense platform whose earning power grows faster than its share count.
My question for the Ondas community is which development do you think would provide the strongest evidence that this strategy is working?
$IREN +3.8% premarket. ⭐️
The Information reports Anthropic has an unannounced multiyear cloud deal with IREN, per people familiar.
Remember the mystery “leading AI lab” customer IREN disclosed in August? The market thinks it just got a name.
Yesterday’s bitcoin miners are now AI’s landlords: Hut 8, TeraWulf, IREN, Nscale.
Reported, not confirmed. No terms yet.
$ZETA received two price-target increases Monday, with Roth MKM raising its target to $55 and Craig-Hallum lifting its target to $38. Both firms maintained Buy ratings following Zeta's recent AI product announcements. ⭐️⭐️
* Roth MKM: Raised its target to $55 from $44 (+25%), citing AthenaOS's potential to attract larger enterprise customers, increase spending per customer and accelerate growth in 2027. Highlighted partnerships with Palantir, Snowflake and OpenAI.
* Craig-Hallum: Raised its target to $38 from $30 (+26.7%), citing major Athena upgrades, an NVIDIA chip agreement, two acquisitions and record Zeta Live attendance indicating a strong sales pipeline.
* Stock price: ZETA last traded at $33.44 (+1.06%) in the premarket, implying approximately 64.5% upside to Roth's target and 13.6% to Craig-Hallum's.

The $SPCX spectrum deal has a price now: $8 BILLION. And the telecom complex sold off hard on the news: $T, $VZ, $TMUS all hit.
The market’s logic: a competitor with its own rockets, nationwide low-band spectrum, and no towers to build just entered the carrier business. Sell first, ask questions later.
The questions worth asking before joining the panic: 👇
➤ Satellite direct-to-mobile serves the coverage gaps FIRST — rural dead zones, maritime, emergencies. That’s complementary before it’s competitive.
➤ The incumbents own something orbit can’t replicate soon: dense urban capacity. Low-band travels far; it doesn’t carry a city’s data load.
➤ Timeline: spectrum is step one. Constellation buildout, device integration, and scale pricing are years of execution away.
➤ But the terminal fear is real: the carriers spent decades and hundreds of billions on networks. SpaceX is attempting to route around all of it from space.
The honest frame: this is 2026’s version of “will $AMZN kill retail?” The answer then was yes AND no; the weak died, the strong adapted.
Same test starts now for telecom.
Disruption headlines sell everything. Execution decides what stays sold.