

Investor | Fintech & Web3 Expert | Family Office Professional | XRP | Crypto Asset Structuring | LLCs | Trusts Security DM to secure your digital future
Dallas, TX
Joined November 2012
- Tweets5.4K
- Following8.8K
- Followers21.5K
- Likes93





Pinned Tweet
Investing isn’t just about markets, data, and returns—it’s also about how we respond to uncertainty.

The account minimum to onboard at DAG Wealth has been lowered to to $250,000 in qualifying assets or 50,000 XRP.
It's one minimum for everything our team manages, traditional assets and crypto alike.

If you need cash for something, you don’t necessarily need to sell your XRP. We've established partnerships with lenders who can issue loans backed by XRP, allowing people to preserve their investment position while still getting the liquidity needed.
One reason advisors hesitate on crypto is the company it keeps: retail exchanges, leverage, whatever's trending that week. Fair enough.
A sub-advisory sleeve is a different animal. A managed allocation, not an app you point a client at.
Self custody is the safest option. Have you considered setting up a Trust/LLC for your assets?


A lot of RIA and CPA firms don't need to build a crypto practice. They need a desk they can lean on for the part they aren't set up to run.
You keep the client, the plan, the return. The crypto piece stops being the thing you hope nobody brings up.


Ripple has built the full financial stack
Institutions using it don't have to pick between the old system and the new one
A lot of people holding crypto are running a fragile setup: self-custody on a hardware wallet, a personal-name exchange account, no legal structure.
Migrating to real structure is a process, not a leap. The risk of moving is far smaller than the risk of staying.
There are a few things that matter if a digital asset is going to be taken seriously as financial infrastructure:
Network reliability
Consistent transaction volume
Predictable settlement
Strong partnerships and institutional support
XRP checks all those boxes
The part of a client crypto allocation that actually protects your firm is the documentation. Your file should show a deliberate process, not an accident: the objective, the size, the custody, the risks in writing, the decision, the review cadence.
The XRP Ledger keeps leveling up with tools like smart escrows and deeper programmability
Think DeFi primitives running directly on the base layer
Builders will be able to launch full-scale DeFi apps on XRP without a smart-contract layer bolted on top
Matthew Mellon died holding ~$500M in XRP. The keys were on devices under other people's names, and his will didn't mention any of it. Nobody knew where they were.
What makes crypto hard to seize makes it hard to inherit.
A common crypto structure is a Wyoming LLC owned by a trust, and people ask why both.
The LLC handles the legal layer: titled to an entity, with charging-order protection. The trust handles succession and privacy: a successor trustee takes over without probate.
Most real success feels like planting and taking care of bamboo
You water it daily for 5 years with no visible growth
Then, almost overnight, it shoots up and everything changes all at once
Institutional custody is about to take over crypto storage, but what do all custody providers meet the standards needed to keep your assets safe?
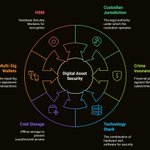
Let me break down what real institutional custody looks like. I believe that real institutional custody has five non-negotiable requirements. Miss even one and you're playing with fire.
Let me give you my definition that a lot of providers fail to meet
Requirement #1: Crime Insurance
Your cold wallet has ZERO insurance. None. If someone steals your crypto, you're done.
But here's the catch - many providers claim "insurance" when they only cover their infrastructure, not YOUR assets. Fireblocks has insurance... on their systems. Not your money. Big difference.
You need to specifically ask: "Is this CRIME insurance that covers my assets if they're stolen or hacked?" Most will dodge this question.
Requirement #2: Bankruptcy Remote
Remember FTX? Celsius? Voyager? Thousands lost everything because their assets were co-mingled.
When these companies went bankrupt, users became creditors. They got pennies on the dollar... if anything.
You need your assets completely segregated. Not in some omnibus account with everyone else's money.
Your assets should be in YOUR specific wallet, under YOUR account. If the custodian goes down, your crypto stays yours.
Requirement #3: Proper Licensing
In the US, this means a bank charter or specific licenses like New York's BitLicense.
The highest standard? Federal bank charter with OCC oversight. That's the gold standard for custody services.
Coinbase and Gemini have the right licenses. Many others... don't. Licensed custodians have regulatory oversight, capital requirements, and legal obligations to protect your assets.
Requirement #4: FIPS Compliance
This is where it gets technical. Federal Information Processing Standards require Hardware Security Modules (HSMs), not just software solutions.
Think military-grade facilities with armed guards and level-four security.
Here's where many "institutional" providers fail...
Fireblocks? No HSMs. Copper? Nope. They use software solutions that don't meet US qualified custodian standards.
Great for exchanges, but not ideal for client custody.
Real HSMs are physical hardware in fortress-like facilities. Your keys are encrypted, sharded, and stored across multiple locations with zero network access points.
This is why traditional finance trusts these systems with trillions.
Requirement #5: Regular Audits
Your custodian should undergo regular third-party audits and meet all federal standards.
No audits = no accountability. Your assets could be at risk and you'd never know until it's too late.
Here's what's really interesting...
The US market is actually the most competitive for institutional custody, despite appearing "behind" in crypto adoption.
These institutions have been preparing in the background for years.
Why does this matter for you?
Your cold wallet doesn't have:
→ Insurance coverage
→ Beneficiary designations
→ Spouse access
→ Protection from phishing
→ Recovery if you lose keys
As your crypto appreciates, institutional custody becomes essential. You need proper estate planning, insurance, and professional management.
Remember the five requirements:
❒ Crime insurance on YOUR assets
❒ Bankruptcy remote segregation
❒ Proper licensing/bank charter
❒ FIPS compliance with HSMs
❒ Regular third-party audits
Your cold wallet was step one. Institutional custody is step two.
Don't get caught holding yesterday's solutions in tomorrow's market.
