

Partner, Afi. Research. Views generally my own. 🇺🇦🇪🇺
Madrid
Joined December 2010
- Tweets6.4K
- Following1K
- Followers1.3K
- Likes3K






Jose Manuel Amor retweeted

🤝 @JuanManuelBazo, socio de Internacional de Afi, presentó junto a @el_BID, los resultados de nuestro estudio sobre el ecosistema de pagos digitales en América Latina y el Caribe, en el marco del Diálogo Regional de Políticas del Sector Financiero (BankLAC/CapiLAC 2026).


Una oportunidad única para aumentar la visibilidad en materia de entorno global geo, macor y financiero para apoyar la toma de decisiones de tu empresa. Te esperamos en #BCN con @FomentTreball @Afi_Research @Afi_es

📊 Com impacta el nou entorn econòmic en les decisions financeres de les empreses?
El 15 d’octubre analitzarem amb @Afi_es l’escenari macroeconòmic, geopolític i financer, i aprofundirem en la gestió de riscos i les fonts de finançament empresarial.
Inscriu-te aquí: foment.com/events/oportunita…

Jose Manuel Amor retweeted

This might have just been the most wild Saturday in AI history.
And that's saying a lot.
Sam Altman took a $1 trillion IPO off the table to agree with Dario Amodei, and it all happened in about five hours.
That photo is from Modi's AI summit in Delhi back in February. Modi tried to get every CEO on stage to join hands for the cameras. Sam and Dario were the two who wouldn't. They raised their own fists instead, and that gap between them ended up being the picture the whole week ran on. Two weeks later they were fighting over Pentagon contracts and a leaked memo.
Today they closed the gap on their own.
Dario published a 3,900 word essay this morning arguing the industry has to slow the pace of capability gains. His reason is that since this summer, models have been helping build the next generation of models, and the gains have outrun anyone's ability to check them. He committed Anthropic to giving outside evaluators like METR badges, desks, laptops, and the right to publish what they find without Anthropic editing it.
An hour later Elon posted "Dario is right." Ninety minutes after that Sam wrote that OpenAI would do the same.
Then Fortune dropped its Sam interview, where he confirmed OpenAI will not go public in 2026 and called an IPO now an ill-advised moment given the safety work ahead.
Here is the part that connects all three.
Pacing the frontier is a coordination problem. The whole thing collapses if one lab defects, and the strongest force pushing a lab to defect is a public shareholder base with a quarterly earnings call. A public CEO who slows a product to honor a competitor's essay gets a securities lawsuit. A private CEO with a nonprofit board gets a hard week.
Sam said it almost word for word. OpenAI needs to make decisions "not obviously in the interest of our business and our shareholders," and that is what the complicated structure was for.
So the IPO delay and the agreement are the same decision. You cannot credibly promise to pace while marching toward a listing that rewards whoever ships fastest. Staying private is the collateral behind the promise.
Back in June the reported reason for waiting was Sam holding out for a $1 trillion print. The reason on the record now is safety, and the incentive math favors the second version.
Dario's step two still needs an antitrust waiver so competitors can discuss limits without a DOJ problem. That part needs Washington. Step one was done at two labs before lunch, with a nod from the third.
The men who wouldn't hold hands for Modi just set AI's first speed limit together.

Jose Manuel Amor retweeted
El próximo lunes, 7 de septiembre, volvemos a abrir al público la "Reunión de la mañana" en homenaje a Emilio Ontiveros. Media hora para repasar lo que está moviendo la economía y los mercados financieros.
🗓️ Lunes, 7 de septiembre, de 8:45 a 9:15 h
➡️ afiglobaleducation.com/pagin…

Jose Manuel Amor retweeted
En su último artículo, @JMAafi y @mromero_afi analizan el cambio de época que atraviesan la economía y los mercados, marcado por el creciente peso de la geopolítica, una inflación más persistente y un menor margen para la política económica.
👉afi.es/insights/del-dividend…

Jose Manuel Amor retweeted

Hay que decirlo muchas veces. La productividad y los salarios altos están en las empresas con tamaño. La escala es una virtud.

Gran paper este. Las pymes no sirven para nada y si hay que poner plata desde el estado tiene que ser a las grandes empresas. Siempre lo supimos, pero bueno ahora está el paper.
zhangc-econ.github.io/files/…


Jose Manuel Amor retweeted

En @Afi_Research, coincidimos con Airef. Nuestro tracker de PIB de España para el 1T26 anticipa un crecimiento muy flojo (menos de lo contemplado en otros modelos por los que apostamos más en esta ocasión: rango 0.5-0.6% T)... veremos!

Enhorabuena - merecidísimo.

Pablo Hernández de Cos, Premio de Economía Emilio Ontiveros 2026.
Reconocimiento a una trayectoria de rigor técnico, vocación de servicio público y contribución al análisis económico y al debate público.
Accede a la nota: fundacionafi.org/pablo-herna…
#Economía #PremioEO

Jose Manuel Amor retweeted

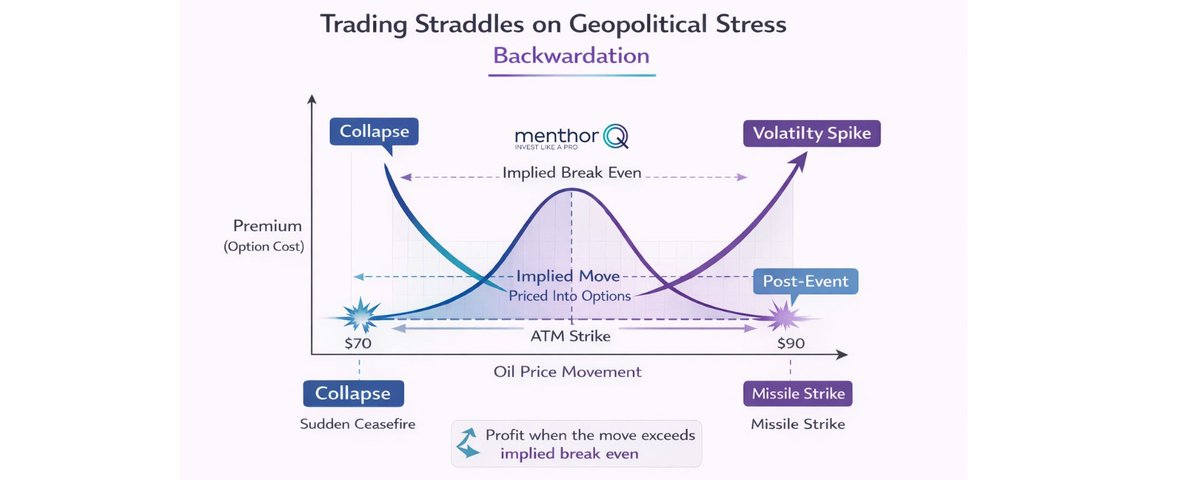
Markets are pricing both the probability and timing of a US–Iran ceasefire. Prediction markets imply ~60% odds by mid-2026, while oil options suggest a gradual resolution with risk fading into 2027. The option surface shows hedging demand, not panic, meaning markets are pricing insurance against shocks rather than a structural supply disruption.

Jose Manuel Amor retweeted
En este primer episodio,@JMAafi, socio director de Análisis Económicos y de Mercados de Afi, y Raúl Viñas, analista y experto en geopolítica de Afi, responden a la pregunta: ¿Está la Unión Europea condenada a la irrelevancia #geopolítica?
Jose Manuel Amor retweeted
I find it hard not to have as a central scenario where oil prices will remain very high for a long time, higher than the market current prices.
I am no expert on geo-politics and defense technology, but this is what I think I have learned:
Fully protecting ships in the strait of Hormuz is basically impossible. Not enough time to stop missiles or drones.
There is no reason, whether or not Trump declares that war is over, to think that Iran will not continue for some time to threaten to destroy the ships that try. Why should they stop?
The risk will thus remain sufficiently high that most non Iranian ships will not take the risk.
Thus, the shortfall of 20 million barrels a day is likely to last for long.
The scope for increased supply from elsewhere is very limited in the short run. Perhaps 2 million barrels at the most.
The 400 million barrels reserve release can only add 3-4 million barrels or so daily.
The short run elasticity of demand for oil is very low, at most -0.1, and probably less.
This suggests to me prices closer to 150-200 dollars per barrel (or more, but I hesitate to give higher numbers…) than to the current market price.
To repeat. I am no expert (As an economist, I have a bit more sense about the next step, namely what such a price would to the world economy). I would be more than happy to be proven wrong.
Jose Manuel Amor retweeted

Second China shock to Europe in full motion.
Europes policy response is weak, fragmented and haphazard.
Buckle up.


Jose Manuel Amor retweeted
On the effects of higher oil prices: The conclusions from our 2009 paper (with Marianna Riggi) nber.org/papers/w15467 are going to be tested. (but there is more to the current episode than higher oil prices)


Jose Manuel Amor retweeted

Kremlin has proposed a wide-ranging economic partnership with Trump administration, including its return to the dollar settlement system. Looking at the Russian seven points provided by @christogrozev, it looks like Russia positions itself for reversed Nixon amid New Cold War.


Siempre llegando allí donde nuestros clientes necesitan tomar decisiones. Puedes suscribir un trial de nuestros servicios de research aquí afi-research.es/ES/secciones…

📊El EU‑ETS arranca 2026 en un entorno de mayor volatilidad geo, climática y especulativa. Desde @Afi_Research analizamos: caída de correlación TTF‑EUA, exigencias en aviación y marítimo, factores fundamentales (clima/ generación energética) y posicionamiento táctico futuro.


Jose Manuel Amor retweeted

🔥 Use AI to read this and re-read. Huge ramifications for the decade and beyond.

Two questions about Japan. 1/ Why has 🇯🇵been able to accumulate so much debt (275% of GDP in 2023) up until now without triggering a fiscal crisis? 2/ Will 🇯🇵 be able to continue harvesting these excess returns?
1/ Why has 🇯🇵 been able to accumulate so much debt (275% of GDP in 2023) up until now without triggering a fiscal crisis?
The Japanese public sector was funding itself at below-market floating rates by having the BOJ issue reserves (91% of GDP in 2023) and then investing in risky assets (181% of GDP), including foreign assets.
Between 2013 and 2023, the public sector earned an extra 6.25 % of GDP per annum (in excess of its below-market funding costs) by taking on interest rate risk, currency risk and equity risk.
As a result, between 1997 and 2023, the net debt, liabilities minus assets, of the entire public sector has only grown from 24.7% to 94.3% of GDP, a 70% of GDP increase, despite the fact that the cumulative primary fiscal deficit of the general government exceeded 133% of GDP during the same periods and despite growth being close to zero.
2/ Will 🇯🇵 be able to continue harvesting these excess returns? No. Probably not. In a counterfactual exercise without QE and YCC (no funding by issuing reserves; the public sector funds itself at true no-YCC market rates), we find that the extra 6.25% of GDP is reduced to 2.75% of GDP. If we then force the government to hedge the currency risk (like the financial sector), then there is no excess return left. The no-QE/no-YCC counterfactual assumes that market bond yields would have been 200 bps higher.
Since the BOJ's tentative switch to policy normalization in 2022, the 10-year JGB yield has already increased by more than 200 bps. The long end has increased even more. This suggests these excess returns harvested by the public sector will disappear going forward, unless the BOJ reverts back to massive QE and/or YCC.
Bottomline: Low-rate policies and financial repression are easy to start, but hard to exit. Japan has been running an interesting experiment for the rest of the world, especially advanced economies, and Europe in particular. I hope we all learn from it.
Joint work with YiLi Chien and Hal Cole.
dx.doi.org/10.2139/ssrn.4620…

Muchas gracias a @elconfidencial y @MAPFRE_ES por invitarme a este panel.

José Manuel Amor, socio director de @Afi_es: "El mercado no es que ignore los riesgos políticos, pero los trata de forma excepcional. El error del mercado es valorar todo de forma cortoplacista porque lee mal la prima de riesgos política"
