

We assist commercial real estate owners and investors in obtaining the most appropriate financing for their assets.
Joined May 2022
- Tweets2.3K
- Following313
- Followers273
- Likes13.1K




A Lower Cap Rate Can Mean More Cash at Closing. And less income relative to price can reduce the debt a property supports.
Two properties have the same asking price—but one generates less net operating income.
Under the same loan terms and coverage requirement, the lower-income property supports less debt. The buyer may need to contribute more equity to complete the purchase. That’s why cap rate matters beyond valuation. It can also influence your financing plan. At a fixed purchase price, a lower cap rate means less NOI available to cover debt payments. If your model assumes a 25% down payment, but the property’s income supports substantially less leverage, the equity gap can change your projected returns.
Before moving forward, evaluate the purchase price, underwritten NOI, interest rate, amortization, and required debt coverage together.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisor
A Saturday question for seasoned investors ☕
When did you last review your debt stack, not just your rent roll?
Experienced owners watch NOI closely. Fewer look as hard at the debt behind it:
📅 Which loans mature in the next 12–24 months?
🔒 What are your prepayment terms costing you in flexibility?
⚖️ Are you carrying recourse you could restructure away?
💰 Is there trapped equity you could put back to work?
Q4 is the right time to plan 2027 refinances, not the month they come due.
When you’re ready for a second set of eyes on your capital strategy, we’re here.
icateam.com
#CommercialRealEstate #CREFinance #CapitalMarkets #RealEstateInvesting #ICONCapitalAdvisors
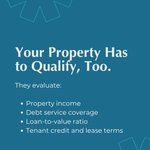
Loan-to-value measures the loan against the property’s value. Debt service coverage measures whether the property’s cash flow can support the loan payments with the required cushion.
For example, a 1.25x DSCR requirement means the lender requires $1.25 in qualifying cash flow for every $1 in annual debt service. If the proposed loan payments are too high, the loan may need to be reduced.
Treat advertised leverage as a ceiling. Your actual proceeds depend on the property, its underwritten cash flow, and the financing terms.
Have a deal in mind? Start with a preliminary debt-sizing review before assuming the maximum leverage.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisor
Buying a property at a 6% cap rate doesn’t automatically mean you can finance 70–75% of the purchase price.
Consider a $2 million property generating $120,000 in annual net operating income. With a 1.25x debt service coverage requirement, that income supports a maximum of $96,000 in annual debt payments.
The loan amount that fits within that payment depends on the interest rate and amortization schedule. With higher borrowing costs, the proceeds could fall closer to 60% leverage—even if the lender’s program allows more.
That difference means additional equity, a revised offer, or a different financing structure. Before you build your investment projections around a down payment, confirm how much debt the property’s income can support.
Save this for your next acquisition, and reach out to discuss your financing assumptions.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisor
Start the conversation before financing becomes urgent.
Ask about:
• Current lending requirements
• Available loan structures
• Rate benchmarks
• Refinancing and extension options
A financing deadline is a difficult time to start learning what your lender needs.
Build those conversations early. Understanding available structures, underwriting expectations, and potential refinancing options gives you more time to evaluate your choices and prepare.
#IconCapitalAdvisor

Could Your Property Handle a Higher Payment?
Stress-test your financing before committing.
Review what happens if:
• Interest rates increase
• Property income declines
• Refinancing requires more equity
Does the property still support the debt?
A deal may work at the quoted rate—but how much room does it have if conditions change?
Investors should evaluate whether their properties can sustain higher debt payments and future refinancing requirements. Testing different scenarios can help reveal pressure points before they become urgent.
#IconCapitalAdvisor

Equity builds wealth. Liquidity gives you flexibility.
Available cash can help you:
• Address unexpected property needs
• Prepare for refinancing
• Respond to acquisition opportunities
You can have substantial equity in real estate and still face a cash shortage when a decision needs to happen quickly.
Focus on the value of preserving liquidity alongside your property investments. Available funds can give you more flexibility when financing needs change or an opportunity requires a timely response.
How accessible is your capital when you need it?
#IconCapitalAdvisor

Your financial profile is part of the story. The property’s ability to support the loan matters, too.
Income, debt obligations, property value, and tenant stability factor into commercial lending decisions. Two properties with similar rental income may present very different risks to a lender.
Understanding those differences can help you prepare for financing conversations.
#IconCapitalAdvisor

What feels like a high interest rate often depends on your perspective—and your experience in the market.
Conditions may change, but a carefully structured deal can still support the returns and long-term growth an investor is working toward.
Looking for guidance on your next commercial real estate investment? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
Sometimes, the motivation behind a sale starts with the loan.
An approaching maturity and difficulty refinancing can create pressure for an owner to consider selling. For prepared buyers, understanding that situation can help identify potential opportunities.
The next step is still careful evaluation of the property’s income, condition, and financing needs.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisor
Higher interest rates don’t automatically mean it’s a bad time to invest in commercial real estate.
Rates are only one part of the equation. The broader economy, tenant demand, and property fundamentals can tell a very different story.
Are you waiting for rates to fall, or evaluating opportunities based on the full market picture?
Considering your next commercial real estate investment? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
Start the conversation before financing becomes urgent.
Ask about:
• Current lending requirements
• Available loan structures
• Rate benchmarks
• Refinancing and extension options
A financing deadline is a difficult time to start learning what your lender needs.
Build those conversations early. Understanding available structures, underwriting expectations, and potential refinancing options gives you more time to evaluate your choices and prepare.
#IconCapitalAdvisor

When higher borrowing costs and tighter lending standards collide, some owners may face difficult decisions—while prepared investors may find new opportunities.
Are you tracking upcoming loan maturities in the markets where you invest? Share your thoughts below.
Exploring acquisition opportunities created by the maturity wall? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
That question helps you understand:
• What drives your rate
• How a floating rate may change
• How future payments could be affected
An interest rate quote tells you where a loan starts. The benchmark helps explain how a floating rate could change. Pair that question with a review of the lender’s margin and adjustment terms to better understand your potential borrowing costs.
#IconCapitalAdvisor

A strong net worth and readily available capital are not always viewed the same way.
In a rising-rate market, preserving liquidity can strengthen your position with lenders and help you move quickly when the right opportunity appears.
When evaluating an investment, how much importance do you place on maintaining liquidity?
Planning your next commercial real estate acquisition or financing strategy? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
A Federal Reserve announcement makes headlines—but what does it mean for your commercial property? Commercial real estate loan rates don’t all move together.
Your rate depends on:
• The benchmark tied to your loan
• Whether your rate is fixed or floating
• Your property’s financial performance
• Your lender’s pricing and requirements
Understanding your benchmark and loan terms can help you assess how rate changes may affect your financing.
Start with one question: What actually drives your loan’s interest rate?
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisor

More leverage can increase your buying power today—but it may reduce your flexibility tomorrow.
The right commercial real estate loan isn’t always the one offering the lowest rate. Its structure should also support your strategy and intended hold period.
Financing a new commercial real estate acquisition? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
A competitive rate matters. So does how the loan fits the property and your plans for it.
Financing decisions should account for your investment horizon, leverage, and future needs. A loan that looks attractive today may create challenges if its maturity or structure doesn’t align with your strategy.
Compare the full loan—not just the headline number.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
Predictability in your commercial loan payments may come at a price—but interest-rate uncertainty can carry its own cost.
Choosing whether to lock a rate requires weighing the upfront expense against the potential impact of future market volatility.
Would you pay a fee for greater rate certainty, or accept the risk of future adjustments? Share your thoughts below.
Comparing rate structures for a commercial real estate loan? Let’s talk.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
Borrowing more can leave less financial flexibility.
Before maximizing leverage, consider:
• Higher debt payments
• Changes in property income
• Future refinancing requirements
• Cash needed for improvements
The maximum loan amount isn’t automatically the right loan amount.
Investors need to consider how leverage affects their ability to navigate changing conditions. Larger debt obligations can leave less room to absorb higher financing costs, weaker income, or additional equity requirements at refinancing.
Evaluate what the property can comfortably support over time.
📞 424-320-9870 | 🌐 icateam.com
#IconCapitalAdvisors
