

Building quantitative AI systems Research @ Tensor Investment I trade crypto, fixed income, commodity, & ETFs Advisor & Builder @ AlphaNet
Hong Kong
Joined May 2025
- Tweets629
- Following145
- Followers634
- Likes1.1K




Founder of Deepseek Liang Wenfeng lives in my building in Shanghai, when he's in Shanghai. I only know because a friend saw his name and address on a Ferrari dealership VIP clientele list. Bumped into him once a few weeks ago when walking my dog. He's a very unassuming figure, dressed in a sporty casualwear and walks to the office (High Flyer asset management).
None of the other neighbors (that I've met) know. You would never guess this guy manages $30B quant fund and runs one of the most consequential AI shops to exist.
China already exports frontier AI. Next it will be institutional-grade quant alpha. I will make sure of it.
This quoted post is unavailable.
If an intelligent trading system can capture a variety of different alphas (up, down, chop, vol, etc) without you having to do anything, then it's 1) definitely institutional grade and 2) a robust system.
A volatile and panic-stricken few days in the market as privacy coins $ZEC and $XMR sell off, with $ZEC retracing as much as 56% from June 5.
How did AlphaNet's strategies navigate the dump for privacy coins and others?
See the report below:
alphanet-info.github.io/06-0…

OK so I claim credit for this paper 😄 (whitepaper actually). Deep learning denial/hating in quant industry is real, but Chinese shops have just embraced it heavily, from mid 2010s. You will see Chinese shops delivering rentech-like returns on US equity markets within the next year or so, mark my words.
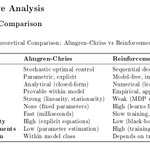
Traditional quant strategies utilize "alpha mining", utilizing often explainable signals (price/volume, microstructure, macro, event-driven etc) to generate trades and positions - and this is what majority of Wall Street firms use. In China over 80% of the top quant firms heavily utilize deep learning systems (including Deepseek's parent High Flyer), a black-box approach that is often non-explainable and uses deep neural network based trained on years of historical data to output predictions from hundreds or thousands of data points.
It is a controversial topic, which practitioners in category often critiquing the other. This 47-page paper compares in detail both approaches and provides an argument on why deep learning has bigger long-term moat.
It also covers frontier approaches for portfolio management in deep learning strategies. (Hint: multi-asset portfolio strategies coming to AlphaNet)
The paper is first being published first in the Chinese quant and academic industry - source is below:
alphanet.global/Alpha%20Mini…


Can't help but wonder if the "AI agents are soon gonna take over crypto transactions" narrative is an attempt to save face for in general low crypto liquidity and interest or stir the pot for another hyped wave.
Either way, for it to be true - one must take the leap of faith that 1) trying to tie many disparate agents to work together is better than a single well-built use case-focused agent 2) the economics and dynamics of such a system would work.
With mainstream LLMs becoming more agentic, and as their ecosystems achieve higher economies of scale, not sure the necessity of crypto/blockchain for such case.
Retail are now showing off their AI quant trading PnLs 🤣 Good good, better than degen trading
This quoted post is unavailable.
Jane Street and Citadel are not worried and are recommending plebs to vibe trade using coding agents - ever wonder why?
True robust vibe trading will not be any Joe Schmo vibe coding some makeshift strategy that may break down any time but rather an AI agent assistant helping pick the right institutional-grade strategie(s) that are made using SOTA quant pipelines, stress-tested and alpha-decay managed.
Optimize strategy selection for market conditions, liquidity, risk profile, and timing. AlphaNet is just getting started and is looking to disrupt the space. We're starting with crypto & single asset strategies but will be coming to commodities, equities, and portfolio management.

Chinese New Year Strategy Leaderboard is here - if you deployed any of these strategies on AlphaNet then your February PnL would look like this halfway through the month without having done anything.
This is what institutional-grade alpha looks like - superior to passive investing, staking, discretionary trading, or buying and holding, on a risk-adjusted return basis.
Welcome to institutional-grade vibe trading.
#AITrading #quant #vibetrading $PHB

A superior alternative to bag holding - alpha exposure both on upside and downside volatility with limited drawdowns. Freedom to mix and match strategies with no lockup period (start and stop anytime).
Disintermediate fund managers and take control with an assistance of an AI chat agent (coming soon) + commodities & equities availability (soon).
The market is deep red, and AlphaNet Autopilot strategies are either green and producing alpha or holding up decently.
The Project Holder Transition program is coming soon. We will be rewarding holders from tokens such as $LINK $DOGE $ZEC $PENGU to transition to AlphaNet and deploy the respective strategies for the token here as an alternative to buy-and-hold.
#AITrading #vibetrading $PHB


Upside + downside alpha exposure for assets without the drawdown risk of buy & hold. What's not to love?
Would it surprise you if I said this could become a highly preferable alternative to investing in altcoins or any high volatility assets?
#AISystems
When investing in an asset over a particular timeframe, two key metrics that investors care about are 1) the return and 2) the risk, and one of the descriptive ways to measure this is “max drawdown”, which measures the maximum decline in PnL equity curve from peak to trough (lowest point).
For traders and investors that want exposure to their favorite tokens, but don’t want the risk (drawdowns) of holding or the trouble and unpredictable results of swing trading, they are much better off one-click deploying in AlphaNet a strategy for that token and let it do the heavy lifting – for instance our Hackworth Prime Series.
Will this cause a generational shift from passive (beta) investing to AI system-driven alpha generation?

Let this be the birth of Vibe Trading. #termcoined
Engineers who use AI tools have "vibe coding". Traders who have access to AlphaNet have "vibe trading".
With vibe trading using AlphaNet in Standard Mode, leveraged scalping becomes almost effortless with the help of proprietary quantitative ML models. From predicting market microtrends, determining when to trade & optimal entry points, and AI algo execution to optimize slippage and trading costs, AlphaNet does the heavy lifting for the user.
Alpha presents itself in front of the trader daily. See how to leverage the models shown below:👇
alphanet-userguide.phoenix.g…
alphanet-userguide.phoenix.g…
#vibetrading #AITrading $PHB


First of its kind. Will likely heat up quick.
AlphaNet AI DEX is now live – first wave of whitelisted users will now be able to access trading. This launch marks a paradigm shift in the crypto trading space – advanced edge and superior alpha will no longer be inaccessible for retail traders. AlphaNet differentiates from the pack from shifting from the main perp DEX talking points to one purely focused on alpha generation value for users.
Access the platform here:
trade.phoenix.global/
This launch includes:
- AI Algo Execution – Through a proprietary deep learning-based execution engine, optimize for minimal slippage and trading costs, often achieving negative slippage. Automate the order execution process and let our system do the heavy lifting.
- Quantative ML Insight Models – Proprietary models that will help you determine and predict trend, market state, market efficiency and optimal entry and exit points ideal for use in leveraged scalping. Freakishly accurate models that adds unprecedented edge to your own edge and trading style.
- Click-to-Deploy Quantitative AI Strategies – Choose from an arsenal of quantitative AI strategies engineered for superior risk-adjusted return from a variety of strategy types, assets and market profiles. Deploy and monitor in real-time, or adjust, mix and create your own “strategy of strategies”. Whether you like market neutral, mean reversion or fat-tail heavy strategies, we got you covered and will give you complete freedom of control.
In the next week or two, expect 1) more announcements 2) video tutorials 3) new models and strategies 4) more growth & adoption-related news!
The future of trading is finally here. Happy new year and see you in 2026!
$PHB #AITrading
Crypto market is not ready for something like this, but here we are on the countdown before new year. #AITrading
Merry XMas!

There lacks a technology platform that provides traders alpha in crypto regardless of the market conditions - in other words, a robust, adaptive market-agnostic alpha harvesting tool. By definition, at a certain point (certain scale) access will be limited by maximum alpha and "meta-edge" capacity - it needs to, and the existing users will want it to (preserve the collective interest).
If the platform has the technological, knowhow and compute capacity for continous new alpha discovery and decay mitigation, then these limits can be expanded with time.
This just described what I'm launching in a few days. It's an ambitious project, and never seen before in similar form. You will know what I mean when you see it.

Adept algo execution (edge) , automated AI quant strategies (alpha), and ML predictive insights (meta edge + alpha) in one trading platform.
May transform the face of retail short-timeframe leveraged futures trading - and perhaps ultimately the "haves" would be in a different echelon from the "have nots".
No longer will retail traders have to attempt to place manual orders for optimal order execution - AlphaNet does the heavy lifting via our proprietary algo execution systems. Minimize slippage (often achieving negative slippage) and optimize average entry price - changing the paradigm for crypto futures trading (especially alts). #AITrading $PHB
For the technical savvy & quants, read up on the background & theory here:
alphanet.phoenix.global/api/…
Traditionally quants have used factor models (which these days mostly produce at most beta and risk premia) and alphas (temporarily sustainable "edges") to produce signals.
With the proliferation of ML and deep learning in institutional trading, "features" (model inputs) and outputs of robust ML systems are being used as alternatives to the above. This is especially prevalent in top quant shops in China & Asia, and less prevalent in Wall Street (no right or wrong, good or bad).
My latest paper (with the help of my team) describes latest methods in adaptive, automated feature construction and evaluation - how to construct features utilizing scalable systems capable of self-optimization and "new alpha" over time. Main approaches described includes genetic algorithmic approach, reinforcement learning-based approach, and LLM-based approach.


Full paper:
hackworthai.substack.com/api…
Substack post:
substack.com/home/post/p-181…