
Reformed short seller. Looking for inflections
Joined September 2025
- Tweets369
- Following192
- Followers6.8K
- Likes853


Pinned Tweet
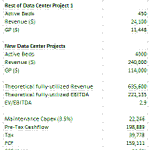
$PUMP is my top pick in Data Center power.
It's perhaps the most asymetric opty I've seen in public markets with reasonable liquidity.
I think this can easily be a $30-40 stock in 2-3years. Net cash balance sheet and 15% fcf yield protect downside.
Guasty Winds retweeted

We remain committed to minority shareholders receiving fair value at Golfzon Holdings and created a website dedicated to this.
golfzonfairvalue.com/
Some notes on $1AST.de.
HD Hyundai is a good read for transformers, as their US Power businesses is predominately comprised of HV power transformers. The company still has a book-to-bill of ~2-3x despite having expanded capacity meaningfully, with no sign of slowing.


Some notes from the $1ast.de call:
- Demand outstripping supply.
- Pricing is still moving higher. "Sky is no limit"
- Strong LT visibility - 55% of the business under LTA, with some stretching to 2032.
- Capacity expansion supported by contracted demand.
I started a position in $PSIX after 2Q results. Many were burned by past management. However, the cpy. appears to have turned a corner on its operating issues and has announced a new CEO who appears fit for the job. At just 10x P/E with a clean balance sheet, I like the R/R.
If you think there’s a 50% chance $PSIX gets its act together, this looks like a good bet. I think the probability is >50%, so I own the stock.