
Focusing on technical analysis, the consumer, and the credit cycle. CFA and CMT. Tweets are only my analysis/opinions/thoughts and NOT investment advice.
Joined August 2012
- Tweets16.1K
- Following178
- Followers3.7K
- Likes58.6K


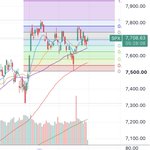


$SPX we had a classic 2HR double div on the ON chart, so not completely surprised by this move. Likely a lot of hedges unwinding. Don’t be surprised if we retest the lows by the end of the week.
Market Analyzer retweeted

That's insane!
Available cash on the NYSE as a % of market cap is at its lowest level in history.
Investors are essentially "all in," with leverage adding to the risk.
With interest rates this high, a mean reversion seems increasingly likely.
Definitely not an ideal time to build a long-term position at these levels.

Market Analyzer retweeted

🚨 A MAJOR CREDIT CRISIS COULD BE BUILDING IN THE U.S.
The riskiest U.S. corporate bonds are now yielding over 18%, their highest level since the pandemic.
Just six months ago, these bonds were yielding around 13%.
That means companies with the weakest finances are now facing borrowing costs that could make refinancing their debt extremely difficult.
But what's more concerning is the growing gap between strong and weak companies.
BBB-rated bonds are paying around 1.1% above U.S. Treasuries, while CCC-rated bonds are paying more than 13% above them.
And the stress is already spreading through the loan market.
According to JPMorgan:
• $139.8 BILLION in risky corporate loans are trading below 80 cents on the dollar, up nearly 90% in a year.
• $65 BILLION in loans are trading below 60 cents, up from $40 billion a year earlier and the highest since March 2020.
• Technology companies account for 39% of all distressed loans, or roughly $54.4 BILLION.
AI-related borrowing is also becoming a serious concern.
CoreWeave, one of the biggest AI infrastructure companies, has seen some of its bond yields climb toward 15%.
Its quarterly interest expenses have jumped from $267 million to $640 million in just one year.
The company has roughly $50 billion in debt and financing commitments to support its expansion.
Meanwhile, higher Treasury yields, persistent inflation and uncertainty surrounding the Iran war are making borrowing more expensive.
The problem is that many heavily indebted companies need to refinance their existing loans at much higher interest rates.
Some may not be able to afford it.

Market Analyzer retweeted
BREAKING: "Speculative data center debt is being repackaged and sold to pension and retirement funds, university endowments, and other institutional investors in a manner eerily reminiscent of the subprime bubble," per AFR
With token pricing falling and AI soon to be on every phone, why would we need more data centres? The bond market knows this yet retail investors continue to go all in (even via passive vehicles). This won’t end well. @JG_Nuke


$SPX looking like 5 waves down and 3 up. 1/2HR reversals. Looking for 3 down into the end of the week.
$SPX just as SPX breaks lower.


BREAKING: Retail investors bought +$9.1 billion of US equities last week, their largest weekly purchase over the last 16 weeks.
This also marks their 9th-largest weekly purchase over the last 12 months.
This follows purchases of +$6.4 billion in the prior week and +$4.8 billion two weeks earlier.
Semiconductors led last week's demand, attracting +$2.6 billion, the 3rd-largest weekly retail purchase over the last year.
Retail investors also bought +$2.4 billion of AI Infrastructure stocks, their 4th-largest weekly purchase over the last 12 months.
Retail investor appetite for AI-related names is surging.

2
300


Market Analyzer retweeted

Look, I know...perma-bear blah blah blah.
But this is crazy stuff.
There are 2 days in history like today, when the S&P 500 $SPY rallied at least 1% to within 1% of a new high, and more of its stocks fell to new lows than highs.
• Jul 23, 1929
• Dec 21, 1999


We've never in almost 100 years seen breadth this bad.
The S&P $SPY is knocking on new highs but there are (many) more stocks at lows than highs.
The percentage of stocks in long-term uptrends is plunging.
The only remotely similar setups were January 1973 and November 1999.
