



Pinned Tweet
Today is the day I join the Substack family, and I have two main reasons:
1) Substack offers better options for sharing longer and more complex work. I want to share, for example, my Excel files, where I have all my calculations, and that works better on Substack than through X articles
2) Feedback from my followers - I was surprised, but many people already asked me if I wanted to create an account on Substack. I assume it is easier for people to read and share than using X.
Please understand that all my articles, deep dives, valuation models, and further analysis will be free for everyone. I am new to Substack, and I must say the fact that the first thing it helps you with is setting up subscriptions is comical. I have some preset settings for subscriptions, but you don’t need to subscribe, as all posts will be open to everyone!
The only limitation I actually set up myself is that commenting is open only to subscribers (the free tier is sufficient) to avoid annoying people.
Feel free to share this so people can follow. Already uploaded my updated Nebius Thesis, and tomorrow I will release the margin impact analysis regarding Token Factory’s new joiner, Inferize.
Thanks for all the support!
funmentalist.substack.com/

We might have an ugly week again, you never know in this market. So let me give you some advice as someone who had everything going for him and suddenly lost most of it. I had to rebuild everything from scratch while suffering from terrible feelings of never being able to be happy again.
Don’t be afraid to lose. Everyone who is truly successful, once lost something that meant a world to him…
If you don’t lose money that you need to survive or someone you love, there is always a way to get everything back and not only that, even more.
You have to lose in life and remember:
The biggest risk is not taking any risks!
See you tomorrow
$NBIS
I’ll be honest, but after this week I am really upset with what is happening on X.
Nothing against @brent_e_trader, first post that I see from him so he might be different, but I see so many negative people on X right now and it must feel terrible for people that are actually trying to get valuable insights from here.
So many posts, that Nebius and other companies are done and that they will go way lower. Do you know what’s worst? That not a single argument/number or god forbid valuation explanation is provided by these people who claim that Nebius is done.
All I read now is:
“Nebius is dead”
“You will lose all your money”
“Look at the debt!!!”
Not a single FCF model that would show why might the business not work, why the debt is a problem, nothing…
I have done all the calculations myself, so I am not bothered by any of this, but I feel in the comments under my posts that some investors are genuinely worried. I don’t want to defend them as they should be responsible for their investments and they should have their own conviction, but man… so many posts also feel like the people are actually happy that others are losing money.
Genuinely sad…

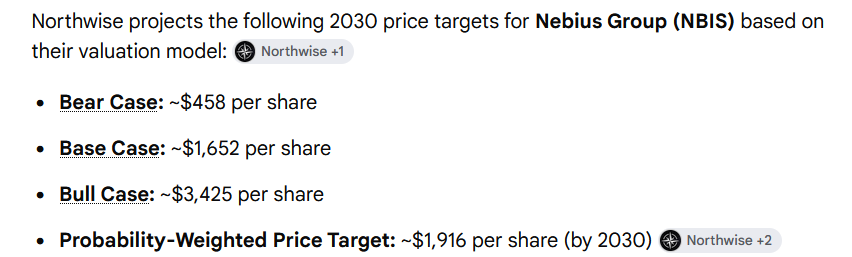
Can someone tell me how credible is Northwise and their price target for $NBIS ? 🤯
Even their bear case is out of this world.
$IREN
Disrespectful to shareholders to be fair…
I hold $IREN for the immense potential upside and I was never hiding the fact that I see many red flags in the management’s ability to achieve their goals.
I apologize to @danroberts0101 and his team, but there is no way these deals make any sense from the ROI perspective…
Don’t use any “visibility” argument on me please. If you are in the compute sector right now when demand is through the roof and people don’t know your company, you are just a poor company and your product must be terrible.
Come at me $IREN bulls, but I am really disappointed shareholder by these things and I think that any lack of execution in the actual compute side of the business will send $IREN back to single digits…
Looking forward to Q3 earnings


Not saying that I don’t think some of the data center plays could be intriguing close to these levels, but why is GPU rental prices being used as a primary principle to promote neocloud valuations?
Pretty much every single one of the major neocloud players have been contracted at much lower prices than what’s currently out there with their current backlogs.
As a shareholder in these companies you are paying for constant dilution, delays which cost even more money and GPU prices that’s not being fully realized and sold at a fraction of the current price.
At this point why not just buy the hyperscalers or chip makers? Hyperscalers have much better credit, resources and capacity, chip makers book revenue in today and don’t have to wait for infrastructure permits.
That’s not even to mention, the pricing on neoclouds bonds have absolutely gone in the toilet, if they were to raise money to build new data centers at readjusted rates of current compute pricing they are getting absolutely smoked in interest payments on top of any additional delays.
Until we have futures markets or some sort of large scale capital marketplace for compute, the neoclouds compared to hyperscalers and chip makers are likely just blind shooting.
$CRWV $IREN $NVDA $NBIS

$NBIS Taking a step back after the drawdown
What I always do for my investments when they experience such a dramatic fall every time is take a step back and look at everything again over the weekend with a cool head, so as not to mix emotions and facts.
1) Thesis
First of all, I attach the updated thesis that I published at the end of September, and I think this is what you should go back to first, as it makes you remember all the verticals that the company is currently progressing on, and it shows you why I believed in the company in the first place (and still believe obviously)!
I believe that nothing has changed since September 2026, and many would argue that things even improved.
2) CapEx/Debt debate
A lot of things were said during this week regarding CoreWeave financials and their implications for the whole neocloud sector. I think it is fundamentally wrong to compare CoreWeave with Nebius and IREN, for example, because each company has a different strategy. In my opinion, the biggest problem for CoreWeave compared to these two is the fact that they sold out their whole 2027 capacity, and overall their deal profile is long-term contracts with terms that do not reflect the current prices. Combine this with their annual interest and potential difficulties to raise additional capital, and you have a problem.
I absolutely disagree with statements that if Nebius were to succeed, CoreWeave must succeed as well. However, that’s not what I really care about today, as I want to discuss Nebius as my biggest position. (Good luck to CoreWeave, as it would definitely be better if they managed to get out of this negative perception!)
So what is the current situation for Nebius?
If we assume the high end of the 2026 CapEx guidance - $25B and look at the gap between what Nebius already spent on CapEx and what is left to spend (we don’t really know what happened since June 30, so we have to work with that):
- CapEx spent in H1 2026 - $8.13B
- CapEx required to meet guidance - $25B
- 2026 Remaining CapEx (as of June 30) - $16.87B
What is the cash situation?
- Unrestricted cash on June 30 - $8.04B
- July secured debt facility - $0.775B
- August convertible financing - $5.75B
This gives us approximately $14.5B in cash and financing resources, which creates roughly a $2.3B gap to cover the remaining CapEx.
We also have to assume that Nebius wants to still finish the year with some unrestricted cash, so let’s assume the $8B similar to its June 30 position.
This means that Nebius needs ~$10.3B of additional net cash inflow during H2, and let’s discuss where they could get this money before people start with the FUD that we will get diluted or Nebius will take on an additional $10B of debt (trust me, they will eventually, you have to account for that).
2.1) Customer prepayments
Management expects more than $9B of upfront customer funding in 2026, but don’t forget that is for the entire year. If we look at the H1 cash-flow statement, we can see a $4.4B positive change in deferred revenue, so we don’t know for sure, but we can expect several billion dollars of additional customer funding arriving during H2, which helps significantly with this gap.
2.2) Operating cash generation
H1 operating cash flow was $109M, and I believe that we can expect at least $400M of operating cash flow in the rest of 2026. Nothing significant, but still almost half a billion dollars.
2.3) Additional asset-backed financing
People completely forget that this is actually the most important and plausible source of capital. Management said that more than $40B of additional customer commitments could support a similar financing structure to the $775M secured facility in July, where Nebius borrowed against deployed GPU infrastructure and contracted cash flows from investment-grade customers.
Overall, to maintain that $8B cash buffer, I believe Nebius still needs to find approximately $5-$6B of further financing excluding operating cash flow and customer prepayments, which we will know more after Q3 earnings (second week of November most likely).
Remember, $5-$6B of additional cash if they want to keep that financing buffer, but if they think that now is not the right time to seek capital, they are covered for 2026 despite what many tried to tell you during this week. So again, everyone panicking before double-checking the facts...
3) Mismatch between my expectations and the street’s consensus
Probably something that makes me most bullish still, and I keep going back to this number is the extremely slow progression curve that the street is expecting. To be fair, I am not surprised that the consensus right now is that Nebius is not a great investment if they expect them to announce $16B in ARR by the end of 2027.
I don’t know what the exact consensus on the active capacity at that time is, but with that estimate, I would be bearish as well, as the economics wouldn’t make much sense at that point, and this is where I believe the big re-rating will happen - Q3 earnings.
I believe many saw the post from @SMASIMHO, where he showed the least bullish base case you can ever see (on purpose), but I will repeat it, so you don’t have to switch between posts:
- 2026 ARR guidance is currently $7-$9B, and I will confidently say that we can assume the midpoint of $8B
- Already confirmed capacity for 2027 is 800MW, and that will most certainly be around 1GW, and in my valuation model, I currently assume 1,700MW of active power by the end of 2027
You can probably understand by now that $16B in ARR is complete nonsense because that would imply -> $9.4M/MW, which is below the bare-metal deals around $11-$12M/MW
I’ll just use my estimates of 1,700MW of active power and blended revenue per MW of $21.1M. First of all, I am already quite bullish in my base case, but we only see GPU prices increasing, and until I see actual cracks in the data, I won’t be lowering my expectations. For those who read my valuation model, I am way above $30B in exit 2027 ARR, but even if we assume my bear case of $25.8B, it would still be 61% higher than what the street is expecting - 61%
My next point would be whether the deals are actually profitable and how much FCF is actually generated, but I am preparing a longer article on this topic because many people apparently can’t do math on X (spoiler: a lot of FCF for Nebius).
So yeah, I am still calm and collected going into the next week and I would summarize it like this:
- No signs of demand slowing from Nebius
- Deals make sense economically
- Sentiment shifted, which is normal
- Thesis is still intact
- Pumped for Q3 results
Thanks for your attention!

$NBIS
As long as people think about Nebius like this, I am happy to hold because the upside is still significant


I see a lot of people upset about me and other FinX influencers for saying that $NBIS was a great buy since $200 (or even higher) and now at $165.
First of all, if you bought a stock simply because someone told you on X and you did 0 DD on the company. I hate to break it to you, but your chances of making serious money in the stock market are pretty low.
Second, I am a long-term investor in $NBIS and I don’t expect to sell my position for several years, which means that if I buy Nebius at $200 and it goes lower, I’ll just simply buy more and won’t be upset about being down 20%. I can’t predict the market in the short-term and while there are indicators and TA works to a certain extent, it is still just psychology and if the majority of the market believes something structurally changed, they will sell/buy beyond what TA suggests.
My valuation of Nebius suggests that we are far away from its current fair price and I’ll happily continue buying.
For complete transparency, which I promised to my followers, I ended the week down 15.3%
You get used to it and I stand by my decision to be heavily allocated in $NBIS and $IREN
I wouldn’t be able to look in the mirror if Nebius or IREN go way higher from these prices because all I see is, in my opinion, asymmetric opportunity
I had almost zero time today, so I had only time to buy more $NBIS
Will write my thoughts tomorrow, but I really think that market is overreacting way too much
Q3 earnings soon and I believe that management will AGAIN show everyone that we need compute and there is still extreme supply shortage
This week everyone suddenly turned bearish AI trade, which is healthy long-term…
Lol
I absolutely love people like this
If the market goes up, this exact person will tell you that the market is irrational.
Now, @daniel_koss provided a simple argument on his take and this person uses market as his argument because he actually has no idea what to answer…
Comical

$IREN
This is scary to hear as an IREN investor. Regardless of who’s fault it is, ANY issues with Microsoft as a client will punish the stock heavily.
Not that my thesis is heavily connected to this bare-metal deal, but it is/was the only validation of IREN’s technology for the broader public.
Will have to investigate this further!

$IREN Status of H2
Timelines
From two separate sources, one is a 2nd degree source and the other is a 3rd degree source, MSFT is requesting changes to H1's networking topology. By extension, this topology will be need to be cabled for H2-4. The re-cabling on H2 was given a timeline of 45 days while H1 will be re-cabled while running workloads aka billing and that process was given a timeline of 4 months. H3 will be delivered with H4 as a supercluster, H4 hasn't begun cabling and will maintain December timeline.
H1 recabling will take much longer than H2 because H1 is already accepted so the changes will be made during maintenance window in stages. H1 will be running live workloads and billing.
I'm not sure when the 45 days started but H2 will be delivered either late Nov or Early Dec.
Both H3 and H4 will be delivered as a super cluster Dec.
What's the Issue
This request comes after acceptance test while running workloads on H1 but before the supercluster networking before H1 and H2. The issue was described as networking bandwidth between racks within a scaleable unit. All of H1 counts 1 scalable unit.
Networking physical distances are not as sensitive as Cray supercomputer days and spec is around 50 meters. This is important because it means that racks will not need to be moved, aka no changes to liquid cooling pipes or power distribution components.
Cabling does take a long time because there are literally hundreds of thousands of cables that need to carefully cabled as wrong cable will take more time debugging than getting it right in the first place. The cabling team used for H1-4 too. However, internally the deadline is still 2026.
Who is at Fault
MSFT is a very large company with multiple team. Their bare metal team signed off because IREN met Nvidia DSX specs. However MSFT platform team when deploying software need a specific topology for their workload and was not communicated to the bare metal team. This explanation is based on the fact that this was not a test case in acceptance testing and found more than 1 month after acceptance and usage began. During this one month, it's likely that platform team deployed and only now did MSFT's AI research team started running workloads.
Between IREN, Dell, MSFT - it's most likely MSFT's platform team did not gather requirements from MSFT's research team and did not relay the full requirements to MSFT's bare metal team. Dell is paid for cabling based on MSFT specs.
And no, there cannot be one huge stress test to have maximized traffic between every rack within the SU because the networking bandwidth is maximized for workload traffic patterns. Every rack pair cannot simultaneously get each rack’s full bandwidth. Different topology maximizes for different workloads. IREN's supercluster topology is most likely rail-optimized, non blocking fat-tree.
$NBIS Beam Day 0
Should I even comment this anymore?
Token Factory needs time and investors need to be patient, but it will be a huge business

Reflection's Beam is available on Nebius Token Factory from Day 0
Reflection’s first open-weight model is built for coding agents, advanced reasoning, software engineering, and autonomous agentic workflows.
Put it to work fixing bugs, refactoring code and using tools.
Try it out today: tokenfactory.nebius.com/?mod…

$ZETA Upgraded to $45 by GS
I studied a lot of material from @wealthmatica back in May/June and even asked him a few questions afterwards.
The thesis was clear to me and it was one of those buys where you immediately get a big return
Lot of people asking me if the stock makes sense after the latest run, but I believe it does (long-term). Back in May when price was around $20, I got $60 as a fair price given the growth and FCF $ZETA will soon generate.
Management is fire, CEO loves the company, pretty simple long-term position if you want exposure outside the AI buildout and also have exposure to a company that benefits directly and significantly from AI itself.

Goldman Sachs raised their $ZETA Global price target…
PT: $30 → $45
Rating: Buy
Commentary:
Goldman "views Zeta as a "differentiated" marketing technology platform at the intersection of customer data, campaign activation, and measurement. The firm sees the company gaining share from legacy marketing platforms and fragmented point solutions. Zeta is positioned to benefit from its platform breadth as enterprises look to consolidate software spend and create room for AI investments... Goldman expects upside to consensus estimates to drive a further rally in the shares."
$ZETA

$NBIS $IREN
Ross apparently knows nothing about AI/GPU technology because he provides a one-sided argument that works only if the output price of tokens is linear, which it obviously isn’t, with Vera Rubin and others producing cheaper tokens than previous generations.
However, he is right that at this point no one probably doubts the demand, and the main skepticism is around "who is going to finance all of this?" and "is there enough capital?"
This is why the sell-off was so aggressive due to potential rate hikes (which I disagree with) and CoreWeave bond yields surging. If there are signs of capital not willing to finance the buildout anymore, we would have a structural problem.
However, both Nebius and CoreWeave were able to raise a meaningful amount of money in the last 2 months, so I don’t think we are this far in the "bubble" cycle.
It will definitely come one day because even among "neoclouds", I see companies that just want to take advantage of the current supply shortage, and their strategy/financing structure makes 0 sense. Only the strongest will prevail, but as long as we see Nebius/IREN increasing their prices and customers willing to pay a significant premium for short-term compute, there is no reason to panic
$NBIS
"Demand is essentially modeled as infinite right now. Generally, for every contract that's about to expire, there's about 15-20 other customers
waiting to bid for that."
I think I don’t have to comment on this one

One of the crazy quotes from an expert call I read was from a GPU Cluster Architect at Nebius and he was asked how they model compute demand and the response was:
"Demand is essentially modeled as infinite right now. Generally, for every contract that's about to expire, there's about 15-20 other customers
waiting to bid for that."
Yes, this is basically the industry right now. Everyone is modeling compute demand as infinite, along with the spend.
$NBIS
$NBIS Muse Spark Open on TF
It was already leaked earlier today, but the best US open-weight model is on Token Factory
Day 0 AGAIN
Muse Spark Open is on Nebius Token Factory from Day 0
It is the most capable US open-weight model to date.
Built for coding and agentic work, it excels at long-horizon tasks, complex software engineering, and multi-step reasoning.
Try it: tokenfactory.nebius.com/play…

$HIMS
I kept saying this since May
Only a matter of time for HIMS
Peptides are first vertical that will start spinning the wheel

$HIMS
🚨 BREAKING: TWO PEOPLE FAMILIAR WITH THE WHITE HOUSE PEPTIDES PLAN SAY IT WILL ALLOW PHARMACIES TO COMPOUND SOME OF THE "MOST POPULAR PEPTIDES"
INCLUDING BPC-157 🔥🔥🔥
SOURCE: AP


$NBIS
And you are not adding in this pullback?
Day 0 or 1 every single new model
Available on Nebius Token Factory from Day 0: NVIDIA Nemotron 3.5 Super VL
Built for agents that read documents, interpret charts and images, and combine reasoning with tool use to get work done.
Evaluate it on your workload: tokenfactory.nebius.com/?mod…
