

Verified on Wealthsimple 🇨🇦 No alpha here. Nothing to sell AI infra/memory/power I buy on vibes Your next fund manager
Canada
Joined July 2026
- Tweets517
- Following422
- Followers1.1K
- Likes409




$CIFR near the bottom?
The $850M 0% convertible notes (due 2032) + the concurrent exchange of ~$166M older notes into ~40.7M shares created the usual dilution + hedging/selling overhang. This pressure is largely done.
Stock is at a 52 week low. Management not talking due to quiet period.
They are the first ai data center to report earnings on Nov 2 so they will set the tone.
Neoclouds are red pre-market again and it is a credit story, not a demand story. Here is what actually happened in the last 24 hours.
$NBIS just raised $3.5B from Citi: senior secured, 364 days, SOFR plus 275 bps stepping to 350. No dilution, and management says $40B+ of investment grade customer contracts get securitized next. Stock still down 3.8% pre-market at 8:49 ET with the group.
$CRWV is the reason. Bernstein cut its target to $51 from $74 and kept Underperform, and the 9.75% 2031 bonds yield about 15.5%, up from 11% in August. When the biggest neocloud borrows at 15%, every power-secured name gets repriced with it. Goldman upgraded it to Buy on Monday, so the Street is split.
Meanwhile the physical bottleneck keeps tightening. Nvidia is pre-paying suppliers: SPIL takes CPO optical engine capacity up 15x by mid 2027 and doubles it again by end 2028, KYEC gets a $1.1B test advance, substrates 2.5x. Taiwan tool makers say CPO equipment lead times went from 3 to 6 months to 6 to 8 months. That is what real photonics demand looks like.
Memory: KB Securities says 80% of Samsung's 2027 output is already under long term contracts and 2027 HBM prices rise 100 to 150%. Bernstein thinks Samsung passed SK Hynix in Q3 HBM revenue, $8.7B vs $7.6B. DRAM contract prices still rise about 20% in Q4, slower than the 80% and 40% jumps earlier this year, and $MU says tight for two more years. Seoul sold it anyway, SK Hynix closed down 5.5%.
Watchlist: $APLD got a Roth Buy at $35 and a 50 MW wind JV in Texas. $IREN licensed a 300 MW campus in Spain for 2028. $WULF CEO says 2028 and 2029 power demand is extremely
strong and no dilution is planned. $HUT got a Piper target cut to $123. $CIFR reports Nov 2, $KEEL Nov 5.
My take: the funding cost is the only bear case that matters right now, and the companies with contracted power and investment grade tenants are the ones that get through it. I am not selling the memory or photonics legs into a deceleration that is still 20% a quarter.
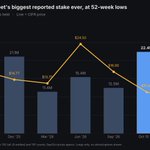
Jane Street just filed a new 13G on $CIFR
22.4M shares. biggest stake they've ever reported here. up from 12.5M on Sep 30
stock is at 52 week lows
no, I don't think JS is a long term holder. they're probably hedging the convert. but someone took the other side of a lot of selling and it wasn't retail
$9B+ Barber Lake lease, Q3 on Nov 2. I'm watching

Optics keep getting confirmed while the stocks get sold. Innolight says 2026 is basically sold out and customers are already handing over 2028 demand for 1.6T, 2.4T and NPO. Lumentum is almost sold out into early 2029 and still undershipping some products by 30%. $LITE and $COHR both report in the first week of November and the order books are the actual story.
$COHR got dumped hard from the $440 high and is sitting around $237. Datacenter and communications is already ~79% of revenue and still growing in the mid-50s. They called fiscal 2027 basically completely booked with customer orders reaching into 2028 and long-term agreements running to the end of the decade. The 6-inch indium phosphide ramp is what unlocks more of that capacity. Same demand that keeps squeezing $MU and filling the neoclouds is what fills the modules and lasers.
Memory is still tight. TrendForce still has Q4 DRAM contract prices up another ~20%. $MU is the pure play and the Taiwan strike talk is more likely to keep things tight short term than break the story. On the power and site side $IREN just locked grid power and civil works for the 300 MW Spain campus, $APLD still has the insider buys and the Texas wind JV. Cost of capital is the debate everyone wants to have, but the leases and the multi-year optics orders are not going away.
My take: the stack is real. Optics lagged the memory names on this last pullback and $COHR looks like the one that got left behind.
Neoclouds got a bounce this morning, and for once there was real news under it, not just Musk tweeting.
$IREN launched IREN Europe with a 300 MW campus in Badajoz, Spain. Grid power and the civil works licence are secured. First ops 2028, no capex or tenant yet. Stock pre-market $27.69, up 4.0% at 9:00 a.m. ET, still sitting near a 52-week low. $APLD signed a 50 MW wind-backed Texas JV with Soluna (51/49, tenant is its own ChronoScale on a non-binding LOI, no dollar value) and Roth reinstated Buy with a $35 target after insiders bought about $6.7M of stock. Pre-market $20.15, up 4.2%.
The real fight is over $CRWV. Goldman upgraded to Buy but cut its target from $139 to $106. HSBC still says Reduce, $39. The 9.75% 2031 bonds traded near 80.6 cents, about a 15.6% yield. That yield is the discount rate the market is putting on every signed lease at $HUT, $WULF, $CIFR and $APLD. Piper cut $HUT to $123 and $NBIS to $185 on the same logic.
Memory did its own thing. Samsung closed up 5.57% and SK hynix up 5.81% in Seoul. Korea chip exports hit $27.5B in the first 20 days of October, up 222.5%, but last year's base had the Chuseok holiday in it, so the cleaner number is a record $4.74B a day. TrendForce still sees Q4 DRAM contract prices up about 20%. Micron's Taoyuan union strikes tomorrow, roughly 22% of its DRAM capacity, though the Taichung HBM site settled. $MU pre-market $924.50, up 3.2%.
Optics, only in Chinese press so far: Innolight says 2026 is basically sold out and customers are giving 2028 demand guidance for 1.6T, 2.4T and NPO. Tencent published a 102.4T NPO switch spec naming Innolight and Eoptolink as suppliers, with NPO supernodes planned for Q4 this year.
My take: the leases are real, the memory squeeze is real, the optics orders are real.
$SPCX just printed $14.6B in Q3 revenue up 161% from last year. AI segment alone did $7.6B and is now the biggest piece. They swung to $4.4B profit with 1.7 GW of compute already online and still building.
This is the AI infra and power demand story. They are leasing capacity to the labs while Starlink keeps adding subscribers at 13.6 million. It validates the buildout in memory and power that I have been talking about and helps the rest of the names in the portfolio more than the market is pricing in yet. After hours is around $155 from the $147.79 close and still well under the $223 target.
Buying the dip on vibes has been working.
The AI infrastructure trade is now a fight over the cost of capital, not demand. Here is what actually happened in the last 24 hours.
$CRWV: Goldman upgraded to Buy but cut its target to $106 from $139. BNP kept Outperform and cut to $117 from $169. HSBC is still at Reduce with $39, arguing CoreWeave makes about $12M of revenue per MW versus $17 to 18M at the big clouds. The 2031 bonds yield over 15%. Korean neocloud Elice closed down 32% on its first day in Seoul. $CRWV, $NBIS and $IREN were all off 3 to 4% pre-market at 8:56 a.m. ET.
Memory: TrendForce has Q4 DRAM contract prices up about 20% quarter on quarter, down from 40% in Q3 and 80% in Q2, with long-term contract price ceilings starting to bite. 2027 blended HBM pricing is still seen up 121%. SK hynix reports Oct 28 with consensus Q3 operating profit near 77 trillion won. It fell 4.2% in Seoul today and $MU was down about 2% pre-market.
Also $MU: the Taoyuan union at Micron Taiwan strikes Thursday Oct 22 over profit sharing. Taiwan is roughly half of Micron's chip output including HBM. A short stoppage tightens an already short market. A long one becomes a volume problem.
Photonics: Innolight says customer orders cover all of 2026 and part of 2027, and key customers have given 2028 demand guidance for 1.6T, 2.4T and near-packaged optics, not yet binding orders. Dell'Oro's OCP recap: $NVDA CPO switches are in production but nobody announced 3.2T, so 1.6T pluggables carry the volume through 2027. $LITE says it is sold out into early 2029. $LITE and $COHR report Nov 4 and 5.
Watchlist: $APLD president bought 300k shares for about $5.7M and the CEO bought another $1M. $HUT: one aggregator shows Piper Sandler cutting its target to $123 from $143, not confirmed elsewhere yet. $MSFT walked away from Nscale's Essex site after the grid date slipped to the 2030s, while Anthropic is reportedly talking about a second $45B, 460MW building in West Virginia.
My take: nothing in the last two days says AI demand slowed. Prices are still rising, orders stretch to 2028, and the hyperscalers are still signing. What changed is the price of money for levered builders. Energized power and funded balance sheets win.
JPMorgan upgraded $INTC to Neutral from Underweight (PT $85). Ends a multi-year bearish call. Points to better execution under Lip-Bu Tan on yields, advanced packaging, and core compute, plus agentic AI workloads that are more CPU-heavy supporting EPS revisions. Stock still ~36% off the June peak.
Tenstorrent closed a $1.5B Series E at a $6.2B valuation (more than doubled from late 2024). Capital for scaling Galaxy servers on open-weight models and inference. Jim Keller’s shop stayed independent after earlier Intel/Qualcomm interest. More non-$NVDA options in the mix.
SemiAnalysis: ~+50 GW of new data-center capacity coming online in 2027, roughly matching all pre-2024 global supply in a single year. >24 GW already in advanced construction and ~$1T in binding non-cancellable leases signed YTD. Once more sites energize, the bottleneck can shift from power/grid toward chips, memory, and networking.
$INTC $NVDA $MU $TSM $CRWV $APLD $CIFR $IREN
Everyone spent last week pricing AI infra like the debt market was closed for good. Huge changes today.
Goldman upgraded $CRWV to Buy this morning. Target cut to $106 from $139, but the argument is the one that matters: revenue per MW and unlevered IRR biased up over the next 24 months, and blended debt cost rises maybe 100 to 200 bp because the borrowing is asset based, not the 15% the unsecured bonds screamed last week.
Memory is not slowing down. Morgan Stanley just took Q4 contract DRAM to +10 to 15% from +3 to 8%, NAND to +15 to 20% from flat to +5%, enterprise SSD +23 to 28%, and 2027 HBM ASP +121%. One caveat, they also cut 2026 Vera Rubin NVL72 racks to under 10,000 vs 15,000 target, and they still rank memory third behind compute and networking. $MU
Nvidia reportedly wants Samsung, SK hynix and Micron all on $TSM 3nm base dies for next gen NVHBM, +30% bandwidth, 15% less power. Samsung foundry's in-house base die angle is gone. The two names already on TSMC keep their lead. $NVDA
The warning sign: $MSFT walked away from Nscale's 50 MW UK site because the grid connection slipped to the 2030s. Nscale has $103B contracted and 55 MW actually live, and IPO talk went from $35B to $16 to 19B. Contracted MW is a press release. Energized MW is revenue.
$APLD insiders bought $6.7M of stock at the lows Friday. Optical comms revenue in Taiwan grew 58% y/y in Q3 with pluggables still outnumbering CPO by more than 25 to 1 through 2027.
Power and memory still the whole story while the sell-off digests.
Samsung and SK Hynix just showed HBM4E at SEDEX. Up to ~16 Gbps (20% faster), 12-layer 48GB options, and SK saying HBM alone won’t cut it for inference so they’re pushing HBF + 3D DRAM. $MU and the Koreans still the only ones that matter here. I don’t think CXMT will deliver on their promises.
McKinsey still sees data-center power demand at ~24% CAGR through 2030. Supply (grid, transformers, turbines, permitting) is the limiter, not the chips.
IEA has data-center electricity roughly doubling to ~945 TWh by 2030. AI sites growing even faster.
Anthropic locked 95 MW in Cape Breton, Nova Scotia on a 20-year lease. Canadian power 🇨🇦 + AI infra is real.
$MU $SKHY $CIFR $WULF
Weekend $QQQ from -0.67% to +0.4% in less than 2 minutes. Those thin crypto order books have no weight to the real market.


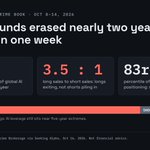
Hedge funds just erased nearly two years of AI buying in one week.
Goldman Sachs Prime Book, Oct 8–14:
• 2nd-largest net selling of global AI stocks in the past year
• 3.5:1 long sales to short sales: longs exiting, not shorts piling in
• Net buying since early 2025: fully reversed
Context:
• July's blowup (Situational Awareness, $45B to ~$10B) and the worst month for Goldman's hedge fund VIP basket in 20+ years came first
• However net flows aren't holdings: 3-year AI positioning is still at the 83rd percentile and leverage is near five-year extremes
•Net leverage: 73.3%. In late August it was 76.8%, which was only the 27th percentile of the past year, so it isn't at an extreme.
•Multi-strategy funds: running about 4.5x leverage. AI allocation: 26.1% of single-stock net market value, down from a 31.7% peak in June. That's the 49th percentile over one year.
Source: Goldman Sachs Prime Brokerage

$CIFR is at $9 and down 30+% the last week and hardest hit of data centre stocks.
Goldman says hedge funds just reversed all net AI buying since early 2025, with longs dumping 3.5:1 over shorts and net leverage at historic lows.
What didn't change: $11.4B of contracted leases (Amazon-guaranteed Black Pearl, Google-backed Barber Lake) and ~$793M/yr NOI from Oct '26 (company est.). 2027 revenue estimates were only ~3% lower as of Oct 9.
The bear case is real: $6B+ debt vs $870M unrestricted cash, a fresh $850M convert note.
If forced selling is mostly done, ~$9 prices in a lot of bad news. Let’s see where this goes on Monday.
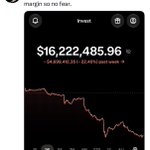
This week was a bomb and not in the good way.
Power and memory stayed the core focus amid continued sell-offs. UBS flagged ~57 GW of data-center capacity needed in 2027 versus only ~38 GW confirmed, while Morgan Stanley pointed to a ~32 GW net US shortfall through 2028; global DC power demand is heading toward ~161 GW in 2026 (+31% YoY) with AI servers already ~33% of that and hyperscaler capex north of $650B TTM.
$WULF was repeatedly highlighted with $27B+ in long-term contracted revenue (Anthropic 401 MW ~$19B alone plus Fluidstack/Google-backed), Muskie advancing toward 1 GW, and no dilution needed—Morgan Stanley kept a 65 target while Cantor cut to 30. $CIFR settled an $850M zero-coupon convert (conversion near 15.31 plus older notes swapped for ~40.7M shares) with Wells Fargo noting Barber Lake 36–38% over budget and Cantor cutting its target to 19 from 28. $CRWV saw 2031 paper briefly yield over 16% and CDS hit records above 1,000 bps, even as management pointed to a 104B backlog plus 25B of new commitments and Cantor reiterated Buy with a 176 target. On memory, $MU was cited at $133B revenue (+256% YoY), 80%+ margins, majority of 2027 HBM already contracted at higher prices, 35%+ of revenue locked through 2030 via SCAs, and still trading around 5x forward after opening a new HBM packaging plant in Taichung. $SKHY fell 31.5% and Samsung 23.9% across seven Seoul sessions before bouncing; Nanya printed Q3 revenue +61.9% QoQ at an 85.7% gross margin with ASPs up over 60%.
We are in extreme fear zone. Hang on for 3 more weeks.
