earth
Joined January 2021
- Tweets158
- Following204
- Followers91
- Likes120


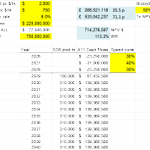

$LQDA some more number crunching...
where can we expect Q4 '26 and full year 2027 financials?
mMngt told analysts that the PAH/ILD split was about 70% towards the end of Q3 in favour of PAH. So its fair to assume that the incremental PAH revenues in q3 was about $35M.
q/q growth has been approx 30% for the past 2 quarters. Since the PAH share of revenues was increasing, it implies that PAH revenues was growing closer to +50% q/q in Q3.
q4 '26 revenues could be as high as $275M. However, there might be some seasonality effect with end of year holidays so it might be more prudent to expect $260-$265M (fwiw, Jefferies expects $264M).
my understanding is that while LQDA cannot sell Yutrepia for ILD anymore, it will maintain existing ILD patients and the related existing revenues for those patients (please correct me if you understand otherwise).
If so, 2027 revenues can exceed $1 bn by a wide margin.
$UTHR has been trading consistently around 7x NTM Revenues. On the same metric, it means $LQDA could be worth 7-9bn in a few weeks or months.
We only need to have more granularity from mngt during the Q3 release (Nov 2nd) and then witness life without ILD with Q4 numbers to be released early next year.
it is totally possible that the share price triples to approx $100/share within the next 6 months.
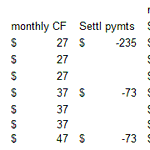
$LQDA: On the potential need for a fundraise, I think the maths and 8k filing help clarify that there is NO need for any fundraise to settle all settlement amounts and meet revised covenants. The Maths:
- LQDA has net cash of $396M as of end Sep. It means they generated about $112M of cash in 3 months (from $222M of rev).
- with PAH-only sales, I think they generate over $180M of rev in Q4, implying about $80M of FCF (before settlements).
- Q1 2027 likely to generate over $220M of rev with about $110M FCF (before settlements).
So thats how it looks cash flows wise including settlement amount and schedule:

$LQDA up over 45% in after hours to $38/share.
Jefferies now updating their PT to $55/share. I think PT would have been much higher had they kept the excellent Equity analyst Amy Li, who seems to have left the team a few weeks ago.
Jefferies is also somewhat conflicted as the same team covers UTHR with an upgrade to their PT too.
$LQDA is expected to have revenues of >$1.2bn in 2027 (likely annualsing over $ 1bn on q4 2026.
So far it is said that revenue are equally split between PAH and ILD.
So in the worst case scenario of Skinny label, you still get $600m rev in 2027. That is not peak sales, thats 2027 sales. I'm not including L606 potential (Jefferies has P606 peak sales at $ 1.3bn).
35-40 dollar a share is a bargain....
Floor price should be $50 in worst case scenario. In a more likely royalty scenario, you get well over $100 a share.
Do we know if those sales were pre-planned (in which case, not much to read into) or intentional from a timing point of view? $LQDA
If intentional, thats quite the dump over the past few days/weeks.

Insiders continue to dump Liquidia $LQDA (hasn't slowed the stock down any)
10 insiders have now sold $40mm of the stock in July alone

Full of Resources retweeted

Join us! We're presenting at the @proactive_x One2One Investor Forum on Wednesday 24th June.
Hear from CEO @RemyWelschinger to learn more about Arc Minerals.
Register to Join via the QR code.
#ARCM

Very interesting transaction by Sandfire in the KCB.
They are paying $3M to acquire two licences on the edge of MMG's Zone 5 corridor.
- There has been very little work done on those licences held by junior Galileo (some geochem and limited drilling with traces of Copper). This is setting a new floor for licence M&A in the area and further highlights that the sweet spot of the KCB is near Zone 5.
- Sandfire is hunting in MMG's territory (unexpected !). This is going to rattle MMG's cage as #ARCM and $LVX hold attractive ground with a proactive exploration campaign.
Maps for context below (Galileo licences & Arc licences).
Watch that space this year !


Interesting. the drilling season will be very exciting for both juniors. One is about 6x cheaper than the other with arguably the more attractive location (based on MMG's discoveries metres away from it). #ARCM $LVX #KCB

Very relevant for #ARCM - Arc is about 2 months from drill start. Our license much closer to Mawana Fold and Z9 (T1 discoveries) plus more evidence of Cu. They’re up 40% and Mcap of £83m…
Just look at these maps. We are ”priority” to MMG.
Botswana up n coming.


Atlantic Lithium taken over by Huayou Cobalt at 18.8p per share.
Not surprised but the price seems low, considering Assore (largest shareholder at 26%) were happy to pay c.30p at similar spod prices, before permitting. They kept buying blocks at 25p.
The statement suggests that Assore is open to higher offers. Maybe CATL ? #ALL #A11 #AtlanticLithium

Atlantic Lithium is pleased to announce it has entered into a binding Scheme Implementation Deed with Zhejiang Huayou Cobalt Co., Limited ("Huayou"), under which it is proposed that Huayou will acquire all of the issued shares in Atlantic Lithium by way of an Australian scheme of arrangement.
Read in full: shorturl.at/pfC7J.
#ALL #A11 $A11 #ALLGH #Lithium #Ghana #Mining


Mar 30, 2026
#Lithium Carbonate 99.5% Min China Spot
Price: $23,719.92
1 day: $+937.26 (+4.11%) 📈
YTD: +40.31%
#Spodumene Concentrate (6%, CIF China)
Price: $2,313.00
1 day: $+83.00 (+3.72%) 📈
YTD: +49.42%
Sponsored by @LibraEnergyMats
Another smart comment below. Could add upside pressure to spodumene prices.

If Mr Friedland is correct, and that the DRC is struggling to get sulphuric acid for copper oxide ore processing, then the Manono North lithium sulphate plant that is meant to start producing this year could be in a bit of trouble also.
Converting spodumene concentrate to lithium sulphate can use a broadly similar amount of sulphuric acid per tonne of final product, as processing copper oxide ore to copper.
If they can't produce a sulphate intermediate product, they will need to transport spodumene concentrate. Sulphate contains ~5x the amount of lithium in say SC5.2. Transportation costs will be significant given the location of the mine.
Could be one of the many reasons as to why the price of spodumene is running?

Geology as warfare...

According to CNN, based on satellite imagery, while the airstrikes have struck 77% of tunnel entrances to underground missile launch facilities, within 48 hours most are reopened by digging out blocked entrances.
thestatesman.com/world/iran-…

Brilliant analysis below of one of the world's largest spodumene deposits.
Saw this article today on the Manono North Deposit and just couldn’t help myself but to make comment. I'll also give my opinion on the deposit as I've had a few people ask for it.
Firstly, the deposit was stolen from AVZ shareholders. I hope AVZ holders get what they deserve for this deposit and it's absolutely pathetic by the Australian government to sit idle. Lots of hard earned Aussie dollars were put into exploring and developing the orebody and the government stays silent? This orebody needed to stay under the one company in order for it to achieve its maximum potential.
Zijin gained control of what is now known as Manono North which predominantly consists of the The Carriere de l’Este Pegmatite, often referenced as the CDL Pegmatite. I do think it's the inferior part of the orebody. It's lower grade than the Roche Dure Pegmatite (not in Zijin's control and to the south) and from an early stage, it seems its metallurgy wont be as good.
Personally I think splitting the deposit up was also a technical mistake. I think it was important from a metallurgy point of view to keep the both the north and south together.
The article states that the Manono North mine will produce up to 130,000 tonnes of LCE per year. I’d argue it won’t be anywhere even close to this.
40.4/(0.82*6) = 8.2 tonnes of SC6 per tonne of LCE.
130,000 * 8.2 = 1.06 million tonnes of SC6.
6/(1.58*0.7) = 5.43 tonnes of 1.58% ore needed per tonne of SC6. I’ve used a very generous recovery rate of 70% and you’ll see why it's generous later.
1.06million tonnes * 5.43 = 5.75Mtpa
This seems doable but the problem is, I don’t think Manono North is going to produce SC6 looking at historical met work and its grade. I think Manono will join the same club as LTR, PLS, MIN, in terms of recoveries. It’s not Greenbushes. I think it will produce somewhere around SC5.2.
40.4/(0.82*5.2) = 9.47 tonnes of SC5.2 needed per tonne of LCE. It becomes very different when you plug this in.
So they are going to need far more than the 850kt of concentrate as stated within the article to produce those 130kt of LCE.
At the time Zijin took control of the north section, the resource was entirely inferred. This is understandable given the lack of drillholes and met work that had been undertaken (AVZ were mainly focusing on the south and doing a great job). I could be mistaken, but I haven’t seen anything via satellite (generally signs of drillholes are easily identifiable) that suggest Zijin has done further work to progress the deposit from Inferred to indicated or measured. So there's a decent chance that the proper work hasn't gone into understanding CDL and it's getting rushed.
One thing that is important to understand is that size of the deposit just one of the many criteria which should be used to rank a deposit. If the deposit is larger than 90-100Mt, I’d say it gets less and less important. Grade and metallurgy become king. So, Manono North is large, but lets talk about its grade and metallurgy.
I dug into historical metallurgy testwork undertaken on the CDL pegmatite and it was average. I can’t find any flotation testwork done on CDL specifically, but the DMS testwork gave 55% recoveries for 5.6mm size and 66% for 3.35mm size. But here's the issue, the head grade used in these tests was 2.37% Li2O. The average grade of the deposit is 1.58% Li2O … What happens if you plug in the average grade of the deposit? So that rules out it being purely a DMS deposit and flotation will be required. Here’s some info from an old post on DMS and flotation from an older post of mine:
xitter.cf/sparkes_dwayne/status/…
So they’ll need to float it which means higher CAPEX and OPEX.
There is some flotation test work done on the pegmatite to the south so I’ll use that as a bit of a guide (It’s a rough guide as metallurgy can change rapidly over 50 meters let alone kms). It came in at 81.5%. Lab work always comes in higher. Every single time. Also it's important to note that this test work was done on a higher grade pegmatite than CDL.
One example which is comparable from a testwork and grade point of view is Kathleen Valley. Manono south's testwork for flotation comes in at almost identical to how Kathleen valley’s (whole of ore flotation not DMS + flotation) did. 81.5% vs 81%. Liontown’s recovery is now at ~63% for SC5.2, 18% less than what the test work gave and not for SC6 as their test work suggested. Just an example how lab tests don't equal what actually happens in practice.
Summary: So in my opinion, Manono North will be somewhat similar to another Kathleen valley or Wodgina coming online. It's grade is somewhat above average @ 1.58% and I'd say its metallurgy is average. Yes it's large, but above 90-100Mt, this becomes less important. So overall a good deposit, but it's no Greenbushes and i don't believe it will spit out the tonnes as what many are suggesting. In order to get those tonnes you're going to need an extremely large capex and i don't think Zijin will invest that much given the nature as to how they got the deposit and also the jurisdiction (unstable).
Those are my thoughts on the Manono North Deposit. Cheers for reading.


Lithium prices up again in Asia. Lithium names are flying on the ASX. Note how Elevra Lithium is rerating. I would add them to the list of potential buyers of @AtlanticLithium alongside Assore and Chinese producers. #ALL #A11
Mar 25, 2026
#Lithium Carbonate 99.5% Min China Spot
Price: $22,088.64
1 day: $+724.22 (+3.39%) 📈
YTD: +30.66%
#Spodumene Concentrate (6%, CIF China)
Price: $2,143.00
1 day: $+71.00 (+3.43%) 📈
YTD: +38.44%
Sponsored by @LibraEnergyMats
Elevra is about 5x the market cap of Atlantic and yet with similar targets to produce just over 300ktpa of spodumene concentrate by 2029/2030. Obviously Elevra is already a producer, so definitely more advanced and derisked but you can see the logic for them to buy Atlantic at 30-35p and be highly value accretive for Elevra shareholders. #ALL #A11 $ELVR #ELV

Iran war fuel crisis gives electric cars a long-term boost - column by @ClydeCommods reuters.com/markets/commodit…

The EV/battery/lithium sector is going to benefit from the sad conflict in the middle east. @AtlanticLithium is the only fully permitted quality spodumene project in Africa that has not yet been acquired by larger lithium producers. And it is still valued at only 20% of Project NPV using conservative assumptions. #ALL #A11
Mar 24, 2026
#Lithium Carbonate 99.5% Min China Spot
Price: $21,350.51
1 day: $+144.75 (+0.68%) 📈
YTD: +26.29%
#Spodumene Concentrate (6%, CIF China)
Price: $2,072.00
1 day: $+44.00 (+2.17%) 📈
YTD: +33.85%
Sponsored by @LibraEnergyMats