
here to talk about finance, real estate, and politics.
Colorado, USA
Joined November 2021
- Tweets30.2K
- Following618
- Followers5.4K
- Likes19.7K


Earning $50 (10%) on $500 isn't addictive.
Earning $5,000 (10%) on $50,000 is addictive.
As parents, if you can seed your child's investment account through the boring, non-addictive phase... and hand over the reigns to the account once its growing by $4-6K per year, it will be much easier to get them hooked on investing for the rest of their life.
Pro Tip: keep a Bic razor in your car, because for some reason, you're much more likely to identify a rogue whisker in you rear-view mirror, than your bathroom mirror.
If you're gonna roll the dice on an adjustable rate mortgage, you better do the following:
1. Plan to aggressively pay down the principal in the first 5-7 years. This will guard you against a sizable increase in payment, if the interest rate adjusts up significantly.
2. build up a sizable cash reserve, so that you can either buy down the principal when the loan reprices, or have the ability to absorb the new higher monthly payment amount for the forseeable future.
I fear that a majority of the people who went with an ARM, as part of their plan to "date the rate" over the past 4-5 years... did neither of the two things listed above.
I own a SFH rental in a Denver suburb, that rents for $3,240/mo. I estimate the current market value of the home is about $500,000.
If I sold the home at this price, to a buyer with 20% down, and a 7.5% interest rate, their 30yr P+I payment would be $2,797/mo. Add in taxes and insurance, and their total payment would be $3,155, or $85 less than what they are paying in rent.
Interest rates are always a variable, but I do feel like this is a good sign that the Denver-metro mousing market is starting to level off. Hopefully this is, or is close to the bottom.
Anyone who bought in the last 24-36 months, who is trying to sell in 2026... is gonna get absolutely clobbered.

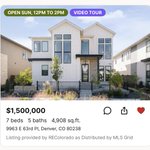
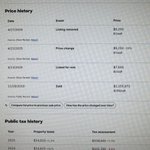
Very well appointed home in my neighborhood just listed for sale this week, with an asking price that is $140,000 less than what they bought the home for just over a year ago... Ouch!
redfin.com/CO/Denver/5880-Be…

Very well appointed home in my neighborhood just listed for sale this week, with an asking price that is $140,000 less than what they bought the home for just over a year ago... Ouch!
redfin.com/CO/Denver/5880-Be…
We've gone so long without a proper correction/recession, that people on X will call you retarded if you're not chasing 15-18% returns with every single dollar.
In 2024, my emergency fund saw a 4.64% return.
In 2025, my emergency fund saw a 4.99% return.
In 2026, my emergency fund is on track to see a 5.43% return.
My emergency fund isn't sitting in a checking account.
My emergency fund isn't isn't held in a money market.
My emergency fund isn't invested in stocks or ETFs.
My emergency fund is the cash-value of my adjustable/universal life insurance policy, through Northwestern Mutual.
Most financial accounts on here will tell you to avoid permanent life insurance at all costs. And if you're looking to maximize long-term growth... they're right.
But if you're looking for a safe financial product that can be utilized as one's emergency fund, you could do a lot worse than a cash-value life insurance policy.
I recently updated my net worth spreadsheet to reflect the current market value of our 11 pieces of real estate.
It was painful, and it reduced my total net worth by nearly $600,000. But it's done, and I can continue to make decisions and moves based on practical, non-delusional data.
Anytime someone bitches about owning/managing real estate, by citing clogged toilets as a major pain point... you can rest assured they have never owned or managed rental property, and are just speculating, without any real world experience.

Anyone else having issues with @dashlane the last 30-90 days? It use to be a great password management utility, but now it's borderline unusable. Slow as shit, and often times wont work unless I remove and re-add the extension.
Drunk Daniel Day Lewis, reading for "There Will be Blood", without rehearsing.

Trump does an incoherent ramble as a confused audience listens in complete silence:
"And you know what they're doing? They go straight down, you know, you can make those drill bits talk. You can make 'em sing, you can make them go, they go down. New York's over here, Pennsylvania-- they go down and they take a sharp left. And they suck our oil out. Can you believe it? Lines of different states, and you'll see one has Cadillacs, because they like Cadillacs better than they like Mercedes, but one has an Escalade, and one has a 50 year old Chevy. And you're talking about 3 ft. It's a line that goes right up. One has some beautiful drilling plants, and one has no drilling plants, it's got no money, it's got poverty."
Who would you rather be in October of 2026?
1. A seller trying to sell a home.
2. A landlord trying to rent a home.
Huge, if true! 🤔

42% of Americans have lost their homes this year.
Readers added context they thought people might want to know
The post falsely claims 42% of Americans lost their homes this year. Completed US foreclosures rose 42% YoY to 5,794 properties in August 2026 per ATTOM, a small fraction of ~149 million total housing units.
nypost.com/2026/10/05/rea…
attomdata.com/news/market-tr…
fred.stlouisfed.org/series/ETOTALU…
What would you do in this scenario?
You have a adjustable commercial mortgage on an investment property, that is currently 3.00%, that will reprice in July of 2027.
The current P+I payment is $2,551/mo. If the loan reprices at 7.50%, the new payment will be about $3,865/mo, or an increase of $1,314/mo.
Option 1 - Do nothing, and pay the extra $1,314/mo. and hope rates fall in the coming 1-3 years, and refinance then.
Option 2 - Refi into a new 30yr fixed at 7.50%, and pay off $143,000 of the remaining principal (plus refi costs), which will keep the monthly payment the same as it is today. No increase or decrease in cash-flow.
Option 3 - Refi into a new 5/1 ARM at 6.675%, and pay off $111,000 of the remaining principal (plus refi costs), which will keep the monthly payment the same as it is today. No increase or decrease in cash-flow.
Option 4 - Use a large portion of your non-tax-advantaged liquidity, and pay off the $507,000 mortgage balance in full, which will increase cash-flow by $2,551/mo ($30,612/yr).
Option 5 - Something I've not considered?
We're currently sitting on over $750,000 of conservatively invested, non-tax advantaged, highly liquid capital... and I still worry it may not be enough to ride out what's coming.