

Helping couples & parents learn how to invest, make more money, payoff debt, & manage finances together 🎉Free investing guide! 210k on IG: @financiallyengaged
Joined March 2016
- Tweets403
- Following142
- Followers182
- Likes75


24% will be automatically withheld for federal taxes by the IRS.
But you’ll fall into the highest tax bracket of 37%, so when you file taxes you’ll owe the add’l 13%.
Let’s break it down:
Every store claims they’ve got the best Labor Day deal… but most of them aren’t real savings. 👀
Here are 10 strategies I use so I NEVER pay full price, and know I’m ACTUALLY getting a deal.
9. Special member of society?
If you’re a teacher, healthcare worker, government employee, first responder, student, senior, nonprofit worker or member of the military, check to see if the store offers you a discount for you being YOU.
7. Go to cashbackmonitor.com - it compares ALL the cash back offers for each store, so you can use the best one. For ex, if I shop at Target, I go to this website to find out if Retailmenot, Rakuten, Ibotta or some other site has better cash back! It's updated every day!
8. Simply google "[insert store name] coupon code." 9 times out of 10 I find a code that saves me at least 10% or gives me free shipping.
Friendly reminder with Labor Day sales ramping up:
if something costs $500 and you buy it on sale for $300, you didn’t save $200.
You still spent $300.
This is especially true with AI. Jobs (especially white collar) will evaporate or move to cheaper/better alternatives. Become resilient - financially, mentally, and with new skills. 9-5 and chill till 60-65 isn’t an option

I started out interested in personal finance in high school. Finance courses in college only accelerated this.
I always wanted to know the smart decisions that you could make early on to squeeze the most out of your income.
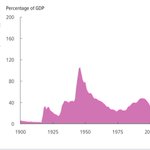
The 2008 crisis happened during high school. It felt like the government was operating like an individual heading for bankruptcy. The debt-to-GDP kept increasing and it always made me wonder....
- Are governments different than normal people?
- Does debt matter for governments just like it does for the Average Joe?
The answer: Yes and no.
The government has an out that the rest of us don't. It has a money printer. But that doesn't mean the bill truly disappears.
Someone has to pay it. And that's typically through dollar debasement (i.e., inflation) spread far and wide to all holders or IOUs of the currency.
Those that pay the most are typically the ones that understand the problem the least. They have a limited ability to dodge the cost and they feel the negative effects way more than the original decision makers. Incentives are misaligned.
Fast forward to today, we've printed a lot more and our debt-to-GDP is much higher and getting increasingly worse. The CBO's projections are conservative and damning at the same time.
It's critical you figure out your own personal finances first and then think through how your income, expenses, assets, and liabilities are impacted in this environment.
Some ultimately have to foot the bill. Be aware and prepared so it doesn't have to be you.
FinTwit spends too much time infighting on what's the optimal strategy (e.g., should you early pay on your 6% mortgage or invest it in low-cost index funds). We fall into this camp too often too.
If you're even at the stage of contemplating these trade-offs, you're probably doing just fine no matter which path you take. Often times, there's no right or wrong answer either.
Instead, we should keep focusing on how we can reach and help the millions of people that aren't to this stage yet.
Those who:
- don't understand the destructive nature of credit card or payday loans
- don't have the confidence or knowledge to start investing
- don't know how to broach the topic of money, assets, debt, and net worth with their significant other
- don't know what currency debasement means and why they can be stuck on an ever-increasing treadmill
Cheers to all those who are here, but let's keep spreading the word and finding ways to get outside of the echo chamber too!
In the short term, the avg. person can’t compete with the quants and insiders on Wall St and in DC.
But you can level the playing field by taking long term strategies or convictions. You don’t need to win short term games like them.
Zoom out and build strong financial habits.

