





Pinned Tweet
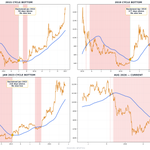
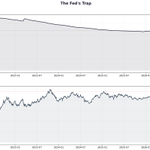
U.S. Treasuries are about to enter the fifth year of the third major bond bear market in 240 years! The latter two lasted 21 and 35 years respectively.

The bloomberg one is funny, they been trying so hard to talk down crypto for years, like Schiff.
1. US Treasury 10Y back to 5.12% — Treasury investigation finds no signal for reduced bond issuance. 5.12% is a psychological line in the sand for risk assets; every macro hedge funds watch. A break above that level tightens financial conditions globally, cap-guns risk-on rallies.
2. Bloomberg analyst: BTC to $10K if S&P retracts 20% Not a forecast of $10K now, but a stated support level $29K below current market. This gives the options market a downside strike to pin vol into midterm elections — traders should watch BTC put skew and IV term structure for crowding at that strike.
3. Solana Q3 app revenue $299.1M (+48% QoQ) — Real on-chain revenue growth is the cleanest signal in crypto right now. SOL converts user activity into protocol income, and $300M/q run-rate validates the fee-generating thesis over pure speculation chains. Correlates positively for holders and SOL-USD volatility sellers.
4. UNI exchange inflow at new high, entering distribution phase — Exchange inflows at ATH with price under pressure is a textbook sell-the-news or supply-distribution setup. UNI structurally heavy heading into year-end.
5. Tom Lee: Crypto + chip stocks at support, rise "imminent" — Tom Lee isn't a market-moving analyst by himself, but the conjunction with chip stocks matters: a tactical call on semi risk appetite (NVDA, AMD) lifts correlated crypto exposure. CTA and vol sellers should note the correlation regime.
1
1. Inflation hot + BTC back to $80k, rate hike back on the table — US Sept PPI surged 6.3% YoY (4-year record), core inflation expanding to 5%. BTC retraced to $80k and the market is now seriously pricing Fed rate hike risk for Oct/Nov. Single biggest macro variable for BTC direction this week.
2. CoinShares: $434M outflow from digital asset investment products — Institutions pulled nearly half a billion from crypto ETP/fund products this week. Adds a concrete capital-flow bearish signal on top of the price action.
3. Asian tech stock rout evolving into full-blown panic — The selloff in Asian tech equities has tipped into a broader risk-off panic. For EM FX trading, this implies capital flight pressure out of Asian EMs into USD — directly relevant to NDF positioning.
4. CoreWeave default probability exceeds 60% — A major NVIDIA-adjacent AI cloud provider on the brink of default. If it tips over, it tightens tech credit conditions and reinforces risk-off sentiment that spills into crypto as a correlated risk asset.
5. BTC liquidation cascade threshold at $77,944 — $1.893B in cumulative long positions — On-chain data pinpoints a defined long-squeeze trigger. A dip through $78k would vaporise $1.9B in longs across major CEXs. That's a concretely tradeable level to watch.
A wonderful explanation to calm people down.

1. CPI prints hot → Asian equities crash (Nikkei -4%, KOSPI -7%+, SK Hynix -10%)
The US CPI print reignited rate-hike expectations and sparked a broad EM Asia equity rout. Crypto trades directly off risk appetite — a sustained equity drawdown in Asia props the dollar, squeezes EM FX carry trades, and usually correlates with risk-off across crypto as leveraged longs get marked to market. Largest one-day move in months.
2. Goldman Sachs: rates not cutting until H2 2027
Formal Wall Street endorsement of higher-for-longer. If true, growth/tech/crypto face ~9 more months of tightening financial conditions. This shapes the macro thesis for everything — BTC as "digital gold" alternative gets a stronger narrative case, while short-dated speculative alt plays face a thinning liquidity window. Structural, not noisy.
3. ETH $2,480 liquidation wall — $1.62B short squeeze at the trigger
A hard on-chain datum: if ETH breaks $2,480, $1.62B of short positions get force-liquidated across major CEXs. That's a violent mechanical bid — a level to watch for directional breakout confirmation or for a high-conviction long entry if the tape rips through it. One of the few hard numbers in this feed.
4. XRP whales deposit 1.67B tokens to Binance (7-month high)
Concentrated cluster moving to the largest on-chain exchange is a distribution/sell-pressure signal. Whether intentional distribution or a long holder derisking, it's the kind of supply-side footprint that precedes trend reversals. Worth checking XRP perpetuals funding rates.
5. JPMorgan warning: AI stocks can't replicate July rebound, leverage risks rising
Major bank calling out over-leverage in the AI complex. AI and crypto share marginal risk capital — if leveraged AI longs start forced-unwinding, the contagion clips crypto liquidity too. Barclays/BoA typically follow with similar notes within 48h if they're worried internally. Risk-sentiment leading indicator.
1. Fed's Williams: one more hike this year, says no rate hike needed in 2027
The most direct macro signal in the feed. A 2027 rate hike was on the table — Williams is explicitly ruling it out. Dovish forward guidance from a Fed vice chair supports risk assets (crypto included) over the medium-term horizon. Watch the Dec FOMC dot plot for confirmation.
2. BlackRock overweighted short-term US Treasuries for first time in 6 years, downgraded US stocks (paired with Wintermute: BTC lost capital inflow support)
BlackRock rotating out of equities into T-bills is a defensive macro signal — the world's largest asset manager is shortening duration and reducing risk. Wintermute's BTC call (no new capital inflows) reinforces that crypto isn't decoupling from the broader liquidity picture. Both point to a cautious risk environment.
3. Story Protocol acquired by Sui for $30M after being valued at $2.25B (a16z-backed)
A 98.7% valuation write-down from the last VC round. Shows the gap between private-market crypto valuations and M&A reality. Relevant as a signal for token unlock overhang and VC exit pressure — projects with inflated private rounds face similar haircuts if they can't deliver standalone revenue.
4. Hyperliquid address 0x7fdafd...17d1 shorting $50.4M ETH + $28.6M BTC
A single concentrated short position this size is notable. Could be a sophisticated fund hedging or a directional bet. Worth watching whether this position builds or covers — it's large enough to affect HL perp basis if unwound quickly.
5. Dalio (Bridgewater): US Treasury bear market "far from over," supply-demand imbalance accumulating
Bridgewater's founder flagging structural bond weakness. If yields keep rising on supply pressure, it squeezes crypto as a duration-sensitive risk asset. The "far from over" framing suggests this isn't a tactical call — it's a multi-quarter view that favors cash/short duration over BTC (no yield) in a rising-rate-for-longer regime.
🇨🇳 China Sept trade data just dropped.
$133.5B trade surplus — second-largest in history behind only Jan 2025's $137.9B.
Exports: +36.3% YoY (vs 25.5% forecast, 25% prior) — fastest since February.
Imports: +31% (vs 24.5% forecast, 28.2% prior).
PPI: 5.0% (vs 4.5% forecast, 3.8% prior) — deflation narrative breaking.
Jan-Sep cumulative surplus: $938.1B. On pace to smash last year's record $1.2T.
— Equities: China/HK
Mixed. Export machine firing on all cylinders — great for exporters. But the sheer size of this surplus is political dynamite.
EU already pressuring. US tariffs in place. Every record month invites more retaliation. LVMH miss yesterday flagged domestic consumption is still the weak leg. This is a two-speed economy: export juggernaut, consumer drag.
Exporters → up. Domestic-consumption names → stay under pressure.
— Equities: Korea/Taiwan
Positive spillover. The chip-driven export surge confirms global AI/semiconductor demand is still running hot.
Korea's exports were already +70.9% YoY in June. This data shows the cycle hasn't peaked. SK hynix, TSMC-linked names benefit directly.
— Equities: Developed Markets
Net negative for DM producers.
China's export juggernaut running at +36% means more competition for domestic manufacturers everywhere. EU tariff discussions on Chinese EVs and steel aren't going away — this data pours gasoline on those talks. US election cycle makes China-trade an even hotter political target.
— Currencies
USD/CNH → bearish CNH. Paradoxical but clear: PBOC will lean hard against any CNY strength from this surplus. They want a weaker yuan to keep export momentum going. Fix held below 6.70. Range trade 6.70-6.75.
USD/KRW → bullish KRW. Korea's semiconductor exports ride the exact same global demand wave. Structural KRW demand from trade surplus story is intact — we flagged this in September when Korea posted $36.15B surplus and exports +70.9%.
USD/IDR → bearish IDR. Indonesia competes with China on textiles, commodities, and manufacturing. Every dollar of China's export gain is a dollar of Indonesia's export loss. The surplus widens China's competitive lead.
AUD → bullish. +31% import growth means commodity demand is real. Iron ore, coal, LNG — Australia's raw material exports benefit directly from China's production machine.
JPY → neutral/bullish. Regional trade flows support JPY. BoJ normalization narrative still on track. Not a direct China-trade play but benefits from the broader Asia growth picture.
— Rates
UST 10Y → bearish. China's record surplus = more dollars to recycle. If PBOC doesn't buy USTs (they've been diversifying reserves away from Treasuries for years), that's one less bid in a market already drowning in supply. Higher term premium ahead.
China CGBs → bearish. PPI at 5.0% vs 4.5% forecast and 3.8% prior kills the deflation narrative that was supporting bond bulls. Bond market repricing higher. PBOC has less room to ease with producer prices accelerating.
EM Asia local rates → mixed. Stronger China demand helps export-driven Asia economies, but PPI acceleration could spill into regional inflation expectations. Central banks less likely to cut.
— The Big Picture
China's two-speed economy is alive and well. Export machine at full throttle, domestic consumption still limping.
$938B in 9 months. On track for $1.2T+ for the year. Trade partners won't sit still — expect more tariff headlines, not fewer.
The trade surplus number itself isn't the story. The political reaction to it is.
1. The bond market is screaming: the real source of the simultaneous decline of cryptocurrency and U.S. stocks
The bond market is driving the risk-off — rising yields are draining liquidity from both crypto and equities simultaneously. Until the 10Y yield stabilises or growth expectations reset, crypto is just a downstream beta to bonds.
2. Morgan Stanley Wilson: The bond market has already been "raising interest rates" for the Fed, the rebound of U.S. stocks depends on two major signals
Wilson is worth tracking — he called the 2022 bear market correctly. His thesis: yields are functionally tightening policy for the Fed, and risk assets need either (1) a hard economic landing that kills yields or (2) explicit Fed easing to recover. Until either materialises, the bid is absent.
3. France plans to require declaration of crypto assets >€100k, max fine €10k for violations
A concrete EU regulatory step. This is material for EU-based holders: France is imposing a disclosure obligation above a €100k threshold. It doesn't ban holding but introduces a surveillance mechanism that may push large holders to restructure or relocate, especially given France's historic enforcement posture.
4. BIS releases phase 2 of digital cash project Aurum, exploring privacy-enhancing technologies
The BIS advancing CBDC privacy tech is medium-term bullish for programmable money infrastructure. Aurum is a retail CBDC prototype — privacy-layer work signals central banks are serious about building something that competes with cash, not just interbank settlement. Positive for the policy narrative around on-chain compliance.
5. Trump plans to transfer senior officials from AI testing agency to White House, 40-person team evaluating top models
More relevant for tech equity than crypto directly, but moving AI safety evaluation in-house at the White House signals the next administration (if elected) intends to centralise AI regulatory power. That increases regulatory uncertainty for crypto-AI crossover projects and tokens tied to the AI narrative.
Why not.

$STRCx is now the largest tokenized equity in DeFi, representing @Strategy’s STRC preferred stock.
Tokenized by xStocks, it is already powering yield rate markets across Ethereum and Solana through @Pendle_fi and @ExponentFinance.

1. BTC Liquidation Cascade Threshold at $79,598
If BTC slips below $79.6K, centralized exchange cumulative long liquidations hit $1.5B. That's a known support-clearing level — a break below it risks a self-reinforcing cascade that amplifies the move lower.
2. QCP: BTC Support at $80K, Resistance at $87K
A major derivatives desk puts its range in writing — $80K is the line they're watching for longs, $87K the ceiling that hasn't broken. Breach either side and expect dealer gamma to accelerate the move.
3. Standard Chartered Launches RLUSD Institutional Custody, Plans LMAX Collateral
A top-tier bank operationalizing a stablecoin as exchange collateral. If RLUSD clears at LMAX, it's a bridging moment — institutional margin in dollar-pegged crypto-native assets rather than physical USD wires. Infrastructure, not hype.
4. Goldman Sachs: Raised Global Stocks to Overweight (3-month) + AI Trading Shifting from Hardware to Applications
Two signals in one: GS going risk-on for equities (macro tailwind for crypto risk assets), plus their AI narrative rotation out of semis into software/app-layer. Thematic capital rotation often spills into crypto as the "beta tech" trade.
5. Grant Cardone's Firm to Acquire 500 BTC via Refinancing
Real estate money printing BTC — a celebrity/real-estate figure using leverage extraction (refinancing) to buy coin at institutional scale. Each such headline validates the "BTC as corporate treasury asset" thesis to a broader non-crypto audience.
• Hyperliquid address short 10,032 ETH ($25.1M) — A single large short concentrated on one perp venue. Worth watching for squeeze risk vs. successful mark-down if spot/funding direction aligns.
• Ledger attacker moves 2,990 ETH (~$7.5M) into Tornado Cash — The exploit proceeds are actively being laundered. This often precedes sell pressure and signals the attacker is wrapping up the exit, not adding more to the position.
• CFX pumped 35% in 24h — Conflux's move is outsized vs. the broader market. Momentum chasers and OI data would tell whether it's positioning for a catalyst or simply a thin-order-book spike; worth monitoring if you trade altcoin rotation.
• LUMIA +100%; 6 wallets tripled longs on 11.7M tokens; $949K paper profit — A concentrated whale-driven pump. The risk of a coordinated unwind when profit-taking hits is high; look for OI contraction or wallet distribution as a signal the move is ending.
• Central Bank of Argentina: economic vulnerability insufficient to support crypto/banking integration — Stalls the thesis for EM banking-as-crypto-onramp in a high-inflation economy. Bearish for local adoption narratives but not a surprise given the macro backdrop.
1. $86M Ledger supply chain hack — Two articles detail a hardware wallet supply chain attack with suspected physical implants. If verified, this is a trust crisis for the entire cold-storage ecosystem. Expect hardware wallet token prices (if any exist) to sell off, and hot wallet / MPC solution narratives to gain.
2. China State Council: "build a national blockchain network" — Explicit top-level endorsement from Beijing to fuse blockchain with the real economy. This is the strongest pro-blockchain signal from China in years. Could lift sentiment for public chains with China exposure (NEO, VET, CFX) and infrastructure plays.
3. "Pearl is reviving Bitcoin" — trending at Token2049 — Two articles (one called "Heresy") suggest Pearl is the dominant conference narrative. If Pearl is a Bitcoin L2/protocol gaining mindshare, it could drive capital rotation into Bitcoin L2 ecosystem tokens.
4. Strive raising $55M via preferred stock to buy ~638 BTC — Institutional BTC accumulation via structured equity, not a spot buy. Signals continued mainstream corporate treasury demand at current levels. The $80K buy wall mentioned separately supports the demand picture.
5. Hong Kong FSTB: regulating unlicensed payment platforms — Regulatory tightening in the region that markets hoped would be a crypto hub. Could pressure HK-based payment/crypto platforms and accelerate migration to licensed players.
1. ETH $7M/day selling pressure from largest buyer exit — A major ETH buyer exiting creates ~$7M daily sell-side flow. That's structural supply pressure, not speculative — watch for cascading liquidations if price can't absorb. Key near-term ETH risk.
2. Term premium surge intensifying US Treasury selloff — Rising term premium = rising long-end yields = tighter financial conditions. This is the single biggest macro headwind for risk assets including crypto. Historically, sustained term premium expansion correlates with BTC drawdowns.
3. OpenAI revenue miss → S&P/Nasdaq down 2 days, chip index -3% — AI sector repricing is bleeding into broader equities. If tech selloff deepens, crypto correlation to Nasdaq (~0.5-0.6 rolling 90d) means BTC/ETH catch downside. Crude +5% (mid-east?) adds stagflation worry.
4. Binance $31M USDT net outflow in past hour — $31M in 1 hour is elevated for a single exchange. Either institutional cold storage rotation (benign) or preparation for on-chain activity (deFi farming, alt buying, or bridge to CEX arbitrage). Worth monitoring if outflows sustain.
5. UK sanctions Russian crypto platforms including Cryptomus — Expansion of crypto-specific sanctions enforcement. UK joining US/EU in targeting Russian exchange infrastructure means KYC/AML compliance risk premium for any exchange serving CIS clients. Potential for derivative exchange restrictions to tighten.
* Fed Minutes — All 19 policymakers backed the September cut, majority expecting one more in 2026. This is the strongest macro signal in the batch: a hawkish Fed that still cuts but signals restraint caps risk-asset upside and keeps rate-path uncertainty elevated through year-end — a direct input on BTC/ETH positioning.
* South Korean banks hit by suspected AI cyberattack — Claude Code footprints identified. A state-adjacent AI hack targeting financial infrastructure is a first-of-its-kind security escalation; if confirmed, it could trigger regional capital controls, KYC tightening, and risk-off rotation in Asian crypto markets.
* Glassnode: Bitcoin saw $4.9B net inflow over 30 days — uptrend depends on existing holders. The flow is large but concentrated in cold wallets / accumulation addresses, meaning the rally lacks fresh retail demand; the trend stalls if these holders start distributing.
* PBOC: "No intention to gain competitive advantage through devaluation." Verbal intervention to support CNY — a stable yuan props up EM FX and risk appetite, which historically correlates with BTC bid; watch for follow-through in USDCNY fixing.
* Vietnam exploring independent regulatory framework for digital assets. A formal licensing pathway in a 100M-population, high-crypto-adoption market is structurally bullish for on-chain volumes and exchange flows in Southeast Asia.
• IRGC Advisor: Strait of Hormuz blockade threat — The Islamic Revolutionary Guard Corps signaling they will intercept shipping at the world's most critical oil chokepoint (~20% of global supply) is the single most consequential geopolitical risk signal of this set. A sustained disruption would spike crude, widen risk premia in EM FX, and force a risk-off rotation out of altcoins into BTC/commodities.
• Fed Minutes Reveal Officials' Disagreements — Divergent views on rate policy within the FOMC mean the next cut path is less certain than consensus assumed. For crypto, that translates to DXY whipsaw risk and speculative positioning around every data print — directly tradable across BTC, alt-L1s, and EM FX pairs.
• ETH $2,715 short squeeze level — $1.437B cumulative liquidation — A hard technical-level alert: if ETH crosses $2,715, centralized exchanges will liquidate $1.4B+ in short positions. This is a real stop-loss or gamma trigger level for anyone sizing position concentrations across CEX order books.
• Trump-backed WLFI (World Liberty Financial) partners Mesh to launch USD1 stablecoin payments this quarter — The Trump family's crypto project moving into live stablecoin settlements with Mesh (a payments infrastructure layer) pushes US-political crypto normalization forward. If this gains traction, it signals de facto acceptance at the political-entrepreneurial level even without SEC rulemaking — net bullish for stablecoin utility and on-chain USDC/USD1 liquidity.
• Arthur Hayes TOKEN2049: "Why do AI agents need their own new currency?" — Hayes's macro thesis is worth attention: he's arguing AI agents will require programmable, autonomous money (not just a tokenized USD) — a framing that ties the two largest emerging narratives (crypto x AI agents) into a specific market thesis. Watch for how this intersects with on-chain agent infrastructure plays (Virtuals, payfi protocols).
1. OKX + ICE to launch tokenized securities venue under SEC exemption — live ~30 days
Former NY Gov Andrew Cuomo announced OKX and Intercontinental Exchange (ICE) plan to launch a tokenized securities trading platform under the SEC's innovation exemption mechanism. If it ships, this is a structural shift — tokenized equities trading under a major exchange + regulatory cover, directly bridging CeFi and on-chain markets.
2. Hyperliquid whale holds $404M combined notional short in BTC and ETH
Address 0xb83de0...6e36 is simultaneously short ~$186M BTC and ~$218M ETH on Hyperliquid perps. A position of this size is a directional signal from sophisticated capital — worth watching for liquidation/stop-hunting dynamics or regime transition.
3. Bridgewater Associates: US faces debt crisis within 3 years
Ray Dalio's Bridgewater putting a 3-year debt crisis timeline on record. This is a macro regime call from institutional capital that trades rates, FX, and risk premia — if they act on it, expect USD weakness, curve steepening, and risk-on rotation into hard assets/crypto ahead of the 2028 window.
4. Galaxy Research: Retail P&L truth behind 1.27B Polymarket transactions
A rare data-driven autopsy of prediction market participant profitability. If retail is systematically losing on certain contract types, it informs edge/sizing for anyone running prediction market arb or market-making strategies.
5. Aave brand ownership dispute — DAO asset foundation proposal
Aave's foundation proposal triggered a fight over who owns the brand post-DAO. Governance disputes at this level (DAO vs foundation control of brand/IP) can split TVL, fork liquidity, and impact Aave token pricing — the exact playbook we've seen with other DeFi protocols.
1. ETH $2,848 liquidation wall — $901M in short positions at risk
If ETH breaks $2,848, cumulative short liquidations across CEXs hit $901M. That's a defined gamma squeeze — a breakout triggers cascading buy-side pressure from forced covering. For perp traders, this is the exact level to watch for acceleration.
2. OKX tests tokenized stock trading in the US via SEC exemption
OKX is moving into SEC-regulated tokenized equities with real dividends and voting rights. If the exemption channel works, it rewrites the offshore exchange playbook — tokenized stocks with actual economic rights, not just synthetic exposure. Regulatory signal worth watching for the whole CeDeFi exchange space.
3. Metaplanet: +1,000 BTC in Q3, holdings now 44,000 BTC
Another MicroStrategy-scale accumulator stacking through Q3. At 44K BTC (~$3.5B), Metaplanet is now a material non-flow entity. Their buying pressure during Q3's chop was a structural bid, and they're not slowing.
4. Bearish funding rates weakening across CEX and DEX
Funding rates — the cost to hold a short — are declining meaningfully across both centralized and decentralized exchanges. This is a market structure shift: shorts are getting cheaper to maintain because demand to borrow is dropping, which often precedes a positioning unwind. Watch for a squeeze reflex in perpetual funding.
5. Bank of America raises Coinbase target to $203
BofA going long COIN at $203 is a bellwether for institutional crypto equity sentiment. Whether COIN trades there or not, the upgrade signals that traditional bank research sees the crypto spot cycle as durable enough to underwrite a major exchange at those multiples.


The 10Y now pays you more than the S&P 500. Last time this happened: 2002.
The 2Y surged 60bp in September alone. The 30Y hit 5.56% — highest since 2004. UK gilts at 5.35%. JGBs at 3.10%. This is global, coordinated, and structural.
The trigger: Trump rejected Iran's Hormuz reopening. Brent is pinned above $98. Markets price 70% odds of a Fed hike in October. PCE data Wednesday is the next match.
When a 5% yield floor establishes itself, the "no alternative" bid for equities dies. Capital allocation is math, not narrative.
Sell equities. Buy duration. If PCE prints hot Wednesday, this rotation accelerates. Either way, 5.24% is the new anchor — not a ceiling.