






$BCDS $NXGB — THE CONGLOMERATE! 👑☂️
ONE UMBRELLA. MANY BUSINESSES!
Real estate, healthcare, blockchain, payments, technology, media & more!
BLAQclouds is building a conglomerate!
As subsidiaries grow, MAMA BCDS can benefit from her ownership stakes!
Here is a great informational video related to Blaqclouds, Inc., parent company, and how it will report the financials of its majority owned subsidiaries and spin-offs.
#BLAQClouds #ConsolidatedFinancials $NXGB $BCDS
For informational purposes only.
Fai retweeted

Here is a great informational video related to Blaqclouds, Inc., parent company, and how it will report the financials of its majority owned subsidiaries and spin-offs.
#BLAQClouds #ConsolidatedFinancials $NXGB $BCDS
For informational purposes only.
Fai retweeted

This is a very nice explanation of how a parent company, such as BLAQClouds Inc. , holds a controlling financial interest in its subsidiaries and spin-offs via consolidated financials. Excellent read. $BCDS $NXGB #Blaqclouds #ConsolidatedFinacials
$BCDS $NXGB — MAMA IS THE QUEEN! 👑
Real estate, healthcare, blockchain, payments, media & more!
Under ASC 810, BCDS can consolidate of controlled subsidiaries' financials, even with 60% ownership
As these businesses grow, MAMA BCDS benefits from the stakes she retains!
🤖 Made with AI

Under U.S. GAAP (primarily ASC 810, Consolidation), a parent that holds a controlling financial interest in an entity—typically a majority voting interest of more than 50%—consolidates that entity on a line-by-line basis in its consolidated balance sheet, regardless of whether the ownership percentage is 60% or 100%.
Company Disclosures on Ownership
Public disclosures filed with OTC Markets (including notes accompanying financial statements) describe the majority of the entities you listed as wholly owned subsidiaries of BLAQclouds, Inc. or as entities in which it is the managing member. These include:
-Apollo Direct, Inc.
-BLAQclouds Property Group, Inc.
-BLAQclouds Global Technology, Inc.
-BLAQclouds Healthcare Technology, Inc.
-BLAQclouds Media, Inc.
-BLAQpay, Inc.
-ZEUS Blockchain Partners
-BLAQclouds Labs, LLC
The same filings note planned or ongoing spin-offs for several of these (Property Group, Apollo Direct, ZEUS Blockchain Partners, Media, Healthcare Technology) under the company’s Four Pillars strategy. For BLAQclouds Property Group specifically, the company has publicly stated it will retain a 60% ownership stake after the spin-out distribution to BCDS shareholders while continuing as the exclusive technology/blockchain architect.
NexGen (NXGen Brands) reflects a controlling share-block acquisition by BLAQclouds rather than a traditional subsidiary formation. Entities such as BLAQCLOUDS DeFi Funding and MadHatter are referenced in ecosystem or related-party contexts but are not detailed with the same ownership precision in the reviewed disclosures.
How 60% Ownership Appears on the Consolidated Balance Sheet
Assuming the parent retains control (voting-interest model under ASC 810, or primary-beneficiary status under the variable-interest entity model):
-Full consolidation of assets and liabilities — 100% of the subsidiary’s cash, receivables, property, intangibles, accounts payable, debt, and other balances are included line by line in the parent’s consolidated balance sheet. There is no proportional (60%) inclusion of individual assets or liabilities.
-Elimination of the parent’s investment account — The parent’s equity investment in the subsidiary is eliminated against the subsidiary’s equity accounts so ownership is not double-counted.
-Noncontrolling interest (NCI) — The 40% portion not owned by the parent is presented as a separate component of equity on the consolidated balance sheet (typically labeled “Noncontrolling interest” or “Equity attributable to noncontrolling interests”). It is not classified as a liability. ASC 810 requires this presentation within equity, distinct from the parent’s own equity (common stock, additional paid-in capital, retained earnings, etc.).
-Intercompany eliminations — All intercompany receivables/payables, revenue/expense, and unrealized profits are eliminated in full (100%), not just the parent’s share.
-Income statement allocation — Consolidated revenues and expenses include 100% of the subsidiary’s amounts. Consolidated net income is then attributed between the parent (controlling interest) and the NCI.
For a wholly owned (100%) subsidiary, the treatment is identical except that no NCI line appears in equity.
Post-Spin-Out Accounting:
-When shares of a subsidiary are distributed to parent-company shareholders and the parent retains 60% (as described for Property Group):
If control is retained, the entity continues to be consolidated.
-The distributed 40% becomes noncontrolling interest. The distribution is generally accounted for as a reduction of parent equity (dividend or spin-off treatment), with NCI recognized for the portion now held by outside (former parent) shareholders.
-The parent continues to eliminate intercompany technology-service or other transactions and to allocate net income between controlling and noncontrolling interests.
#Compliance | #BLAQclouds | #FourPillars | #CryptoUtility | #Web3 | $BCDS | $NXGB

Fai retweeted
Great explanation of how a parent company will consolidate financials of its subsidiaries and spin-offs. Thanks!
Fai retweeted

Monday if you will, help lock $NXGB up and join us on the ride towards pennyland beside $BCDS 🤝
Nxgenbrands.io 21 live brands 👏
$30M+ in revs and aiming for much much more 💪
Good luck to us all! 🚀🚀🚀

Fai retweeted
Under U.S. GAAP (primarily ASC 810, Consolidation), a parent that holds a controlling financial interest in an entity—typically a majority voting interest of more than 50%—consolidates that entity on a line-by-line basis in its consolidated balance sheet, regardless of whether the ownership percentage is 60% or 100%.
Company Disclosures on Ownership
Public disclosures filed with OTC Markets (including notes accompanying financial statements) describe the majority of the entities you listed as wholly owned subsidiaries of BLAQclouds, Inc. or as entities in which it is the managing member. These include:
-Apollo Direct, Inc.
-BLAQclouds Property Group, Inc.
-BLAQclouds Global Technology, Inc.
-BLAQclouds Healthcare Technology, Inc.
-BLAQclouds Media, Inc.
-BLAQpay, Inc.
-ZEUS Blockchain Partners
-BLAQclouds Labs, LLC
The same filings note planned or ongoing spin-offs for several of these (Property Group, Apollo Direct, ZEUS Blockchain Partners, Media, Healthcare Technology) under the company’s Four Pillars strategy. For BLAQclouds Property Group specifically, the company has publicly stated it will retain a 60% ownership stake after the spin-out distribution to BCDS shareholders while continuing as the exclusive technology/blockchain architect.
NexGen (NXGen Brands) reflects a controlling share-block acquisition by BLAQclouds rather than a traditional subsidiary formation. Entities such as BLAQCLOUDS DeFi Funding and MadHatter are referenced in ecosystem or related-party contexts but are not detailed with the same ownership precision in the reviewed disclosures.
How 60% Ownership Appears on the Consolidated Balance Sheet
Assuming the parent retains control (voting-interest model under ASC 810, or primary-beneficiary status under the variable-interest entity model):
-Full consolidation of assets and liabilities — 100% of the subsidiary’s cash, receivables, property, intangibles, accounts payable, debt, and other balances are included line by line in the parent’s consolidated balance sheet. There is no proportional (60%) inclusion of individual assets or liabilities.
-Elimination of the parent’s investment account — The parent’s equity investment in the subsidiary is eliminated against the subsidiary’s equity accounts so ownership is not double-counted.
-Noncontrolling interest (NCI) — The 40% portion not owned by the parent is presented as a separate component of equity on the consolidated balance sheet (typically labeled “Noncontrolling interest” or “Equity attributable to noncontrolling interests”). It is not classified as a liability. ASC 810 requires this presentation within equity, distinct from the parent’s own equity (common stock, additional paid-in capital, retained earnings, etc.).
-Intercompany eliminations — All intercompany receivables/payables, revenue/expense, and unrealized profits are eliminated in full (100%), not just the parent’s share.
-Income statement allocation — Consolidated revenues and expenses include 100% of the subsidiary’s amounts. Consolidated net income is then attributed between the parent (controlling interest) and the NCI.
For a wholly owned (100%) subsidiary, the treatment is identical except that no NCI line appears in equity.
Post-Spin-Out Accounting:
-When shares of a subsidiary are distributed to parent-company shareholders and the parent retains 60% (as described for Property Group):
If control is retained, the entity continues to be consolidated.
-The distributed 40% becomes noncontrolling interest. The distribution is generally accounted for as a reduction of parent equity (dividend or spin-off treatment), with NCI recognized for the portion now held by outside (former parent) shareholders.
-The parent continues to eliminate intercompany technology-service or other transactions and to allocate net income between controlling and noncontrolling interests.
#Compliance | #BLAQclouds | #FourPillars | #CryptoUtility | #Web3 | $BCDS | $NXGB
$BCDS $NXGB — my take from your write up. Is this true?
BCDS IS THE MAMA! 👑
Real estate, healthcare, blockchain, payments, media & more!
As subsidiaries grow, BCDS benefits through its ownership stakes, even after spinoffs!
BCDS gets a PIECE OF EVERYTHING it retains?
Under U.S. GAAP (primarily ASC 810, Consolidation), a parent that holds a controlling financial interest in an entity—typically a majority voting interest of more than 50%—consolidates that entity on a line-by-line basis in its consolidated balance sheet, regardless of whether the ownership percentage is 60% or 100%.
Company Disclosures on Ownership
Public disclosures filed with OTC Markets (including notes accompanying financial statements) describe the majority of the entities you listed as wholly owned subsidiaries of BLAQclouds, Inc. or as entities in which it is the managing member. These include:
-Apollo Direct, Inc.
-BLAQclouds Property Group, Inc.
-BLAQclouds Global Technology, Inc.
-BLAQclouds Healthcare Technology, Inc.
-BLAQclouds Media, Inc.
-BLAQpay, Inc.
-ZEUS Blockchain Partners
-BLAQclouds Labs, LLC
The same filings note planned or ongoing spin-offs for several of these (Property Group, Apollo Direct, ZEUS Blockchain Partners, Media, Healthcare Technology) under the company’s Four Pillars strategy. For BLAQclouds Property Group specifically, the company has publicly stated it will retain a 60% ownership stake after the spin-out distribution to BCDS shareholders while continuing as the exclusive technology/blockchain architect.
NexGen (NXGen Brands) reflects a controlling share-block acquisition by BLAQclouds rather than a traditional subsidiary formation. Entities such as BLAQCLOUDS DeFi Funding and MadHatter are referenced in ecosystem or related-party contexts but are not detailed with the same ownership precision in the reviewed disclosures.
How 60% Ownership Appears on the Consolidated Balance Sheet
Assuming the parent retains control (voting-interest model under ASC 810, or primary-beneficiary status under the variable-interest entity model):
-Full consolidation of assets and liabilities — 100% of the subsidiary’s cash, receivables, property, intangibles, accounts payable, debt, and other balances are included line by line in the parent’s consolidated balance sheet. There is no proportional (60%) inclusion of individual assets or liabilities.
-Elimination of the parent’s investment account — The parent’s equity investment in the subsidiary is eliminated against the subsidiary’s equity accounts so ownership is not double-counted.
-Noncontrolling interest (NCI) — The 40% portion not owned by the parent is presented as a separate component of equity on the consolidated balance sheet (typically labeled “Noncontrolling interest” or “Equity attributable to noncontrolling interests”). It is not classified as a liability. ASC 810 requires this presentation within equity, distinct from the parent’s own equity (common stock, additional paid-in capital, retained earnings, etc.).
-Intercompany eliminations — All intercompany receivables/payables, revenue/expense, and unrealized profits are eliminated in full (100%), not just the parent’s share.
-Income statement allocation — Consolidated revenues and expenses include 100% of the subsidiary’s amounts. Consolidated net income is then attributed between the parent (controlling interest) and the NCI.
For a wholly owned (100%) subsidiary, the treatment is identical except that no NCI line appears in equity.
Post-Spin-Out Accounting:
-When shares of a subsidiary are distributed to parent-company shareholders and the parent retains 60% (as described for Property Group):
If control is retained, the entity continues to be consolidated.
-The distributed 40% becomes noncontrolling interest. The distribution is generally accounted for as a reduction of parent equity (dividend or spin-off treatment), with NCI recognized for the portion now held by outside (former parent) shareholders.
-The parent continues to eliminate intercompany technology-service or other transactions and to allocate net income between controlling and noncontrolling interests.
#Compliance | #BLAQclouds | #FourPillars | #CryptoUtility | #Web3 | $BCDS | $NXGB
Fai retweeted

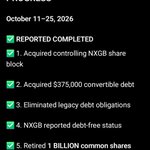
$NXGB News out!!! 1B shares retired, now debt free, acquisition coming in next few days and much more!! Let’s see that break into 005’s and head towards 01!! globenewswire.com/news-relea…

$NXGB Who the heck sold 20's last week to go chase the daily pump? Ouch! So much more ahead here! PR tomorrow on everything that has been going on and future catalysts! Break those highs and its 006 then 0088!

Fai retweeted

$NXGB I will join the effort as well 👀
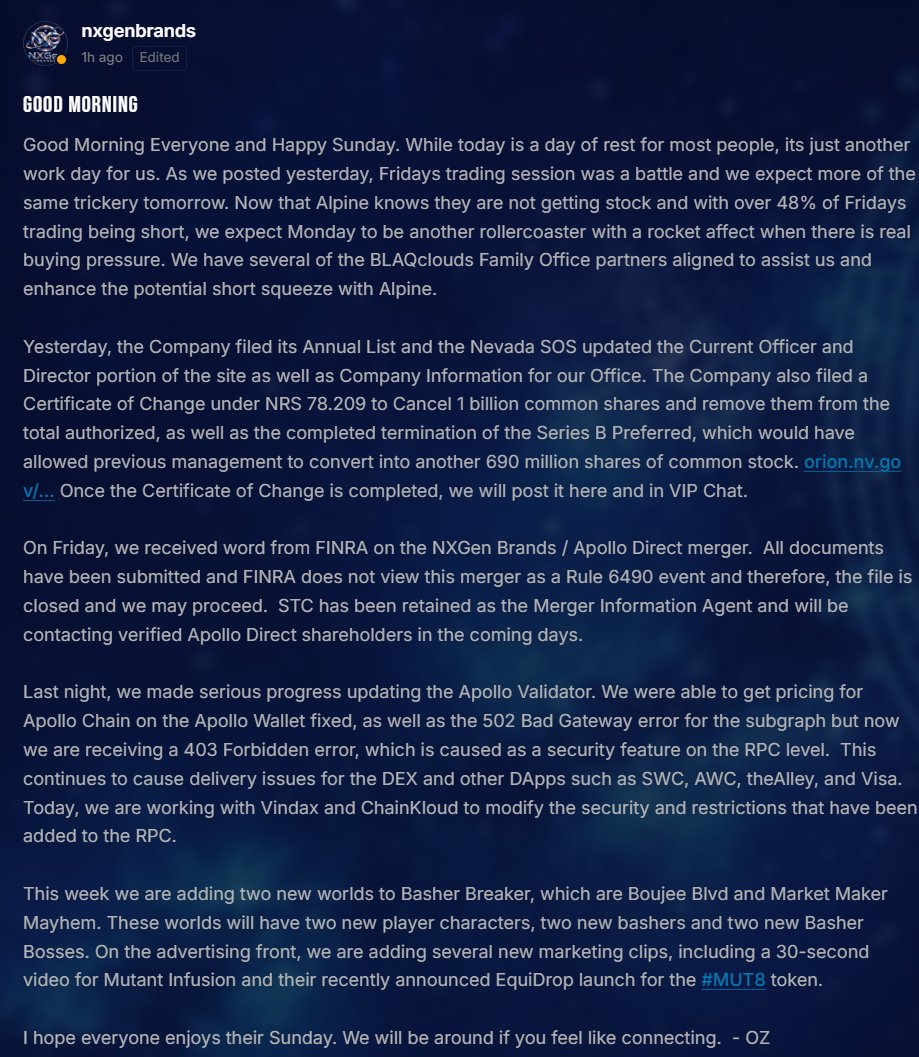
And read that morning update closely. The big boys are coming in to back us up with squeezing the short overhang with Alpine. Follow is on thealley.io for all the latest $NXGB and $BCDS updates!


