
EM economist, trader, portfolio manager for 30+years. Head of active EM bonds at VanEck. Disclosures: https://xitter.cf/t.co/Gl2tsi0aNn.
Joined July 2024
- Tweets895
- Following1.5K
- Followers1.2K
- Likes1.3K


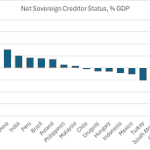
Mexico's central bank had already loosened its habit of following the Fed before this hiking cycle. A rising US policy rate will be the real test of that. It may mean a willingness to let the peso weaken.
We wrote after the April 2025 meetings that the CNY and CGBs would appreciate. We still think so, and political pressure on China is just a tailwind. Our conclusion is gradually stronger CNY and CGB prices. The external surpluses will continue indefinitely.
I left Bangkok in 1979, at 13. Today there are no strays and no soldiers behind sandbags at intersections. Rabies deaths fell from 370 in 1980 to 7 in 2025. Life expectancy rose from 61.7 to 77.1 years. Progress is real.
Markets were right to ignore geopolitics for years: the oil always got out. Not now. The Gulf closure was a first in its history. And most participants forget there's always a "grown up" table, and that part of every side's agenda is propaganda.
Europe has no fiscal union and no financial union. That invites attack on individual sovereign bond markets. France will have to fix France, not the EU and not the EZ.
En route to Bangkok/IMF.
Let’s see what everyone is still in denial about, and short it. And buy what they hate, like the dollar last April.
(Just setting a tone, not describing a process.)
Quick comments from a bond and FX guy…
Stagflation is obvious, but the hard part is going to be mentally adjusting for high nominal growth rates. The flation will convince you there’s no stag. (And the inevitable recalculation of ex-post inflation, whenever a new political actor decides to be “shocked” at the ex-post inflation understatement might even be when things turn good for rates, who knows/way too early.)
Unless peace breaks for all 3 wars (game theory is transformed by the renewed Yemen war, btw, so good luck), it’s the old “the Fed will hike until something breaks”.
Bond traders often ask themselves “what do investors think in May, and what will they likely see when they come back from vacations (what are those?) in September?”
Investors in May went in thinking nothing about midterms, and thinking (or at least reading everywhere) that the 2 wars were going great/nothing to see here. Today, the war reporting has to include a 3rd war, and more refinery destruction.
Got implications? Midterms will be a huge challenge for the IG financing around data centers. Ginormous. Isn’t this obvious? Is it priced?
BTW. I think all of this is USD bullish against the majors. We’ve been publishing detailed analyses for 15 years on this stuff - USD reserve status, fiscal dominance- and we manage portfolios every single day, so we can’t have “theories” as a basis. But our bottom-up consistently pointed to USD being the least-bad major currency (other than gold, obviously, as well as CNY, and EM commodities exporters ). And it’s not just driven by higher front-end rates, in our view, but sure, that’s clearly part.
Not gonna get into all of that here, all I’ll say is based on my extensive interaction with Europe (born, worked, etc), they still can’t have a discussion on the asset price implications of obvious political developments. No good destination comes without getting over that phase. It’s just beginning, we know it in life and know it as country economists. France CDS will be like Oracle CDS (meaning a trading dynamic can easily happen given how cheap it is to buy protection, forget whether you’re ultimately right, I can find an easy long against it and cover my short whenever)…then let’s see…that’s almost always all it takes.