Full time job on the world greatest Offshore Drilling Rig as Driller Picking easy money in stockmarket when opportunity presents itself No advice,do your own DD
Joined January 2020
- Tweets3.5K
- Following111
- Followers2.2K
- Likes8K




Okeanis $OET down 9% in Oslo last month. Sure you have sufficient amount located before numbers are out?

3
18
1,087
Strong datapoint from $VLCC just ~10% shy of Xclusive Sb record assasment of $230 mill. $FRO $DHT $ECO $INSW $OET $CAPT.OL


$VLCC.OL has entered into an agreement to acquire a modern, scrubber-fitted eco VLCC from an affiliate of Trafigura, the Company's indirect majority shareholder, for a purchase price of US$210 million.
#Tankers

2
401
#Tankers PAS take:
"...After a ~20% pullback, DHT, FRO and OET could all be paying out 32 – 38% of their market caps through 2027 (on conservative '27 estimates), rising to ~50% if VLCC rates average $150,000/day next year."
Clarksons take:
"....It’s important to underline that a lower war premium on oil prices does not immediately translate to normal shipping conditions"
#Tankers $ECO $FRO $DHT $INSW $OET
👇👇

5
432
$CAPT.OL reporting a strong fixture and has entered into a 15-month time charter agreement for their Suezmax M/TAmor built 2026.
TC is expected to generate revenues of between $73.1 million and $82.2 million. Dayrste in area of $180k/day.

1
7
558
🫡 👇👇


Loved it.
Make sure YOU tune in for latest rumors of a 6 month VL TC fixture. #Tankers #Shipping #CarCarriers

New Vonheim episode out with equity analyst in Pareto, Eirik Haavaldsen. A big menu as always!
Tune in: youtu.be/6hY64wFJAuY

👇👇 Looks like too rough weather in Bremerhaven.

Cruise liner Mein Schiff 3 CRASHES into container ship MSC VICTORINE in #Germany. The collision happened in Bremerhaven as Mein Schiff 3 was just leaving the port. The container ship suffered hull damage with a roughly 33 feet (10m) breach.
$BORR jackup Prospector 5 experience a punch through event
during preload activities, resulting in loss of stability and the subsequent
sinking of the rig.
Thoughts and prayers to the crew and families.

2
48
1,864

Mine project investment and LR2 exposure looks to be coming to an end.
Acc to Xclusive Shipbrokers Middle Eastern buyers acquired the
scrubber fitted “Copenhagen Star” - 115K/2025 Daehan for USD 125 mill.

7
588
…..and while we wait for estimate revisions and repricing there will be some serious dividends. #Tankers $ECO $FRO $INSW $OET $CAPT.OL


"The company believes the vessel is the 317,000-dwt VLCC Al Funtas (built 2017), owned by Kuwait Oil Tanker Co"
#Tankers
tradewindsnews.com/casualtie…

#Tankers 👇👇

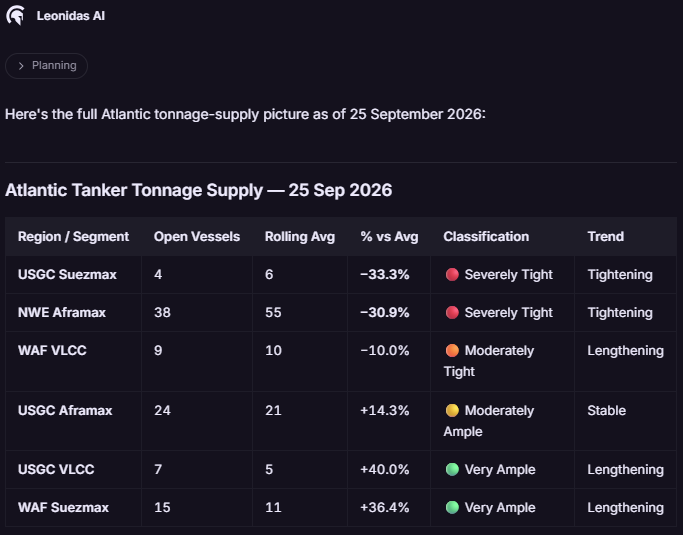
Leonidas AI: Atlantic DPP Tonnage Report
Tightest Segment: USGC Suezmax & NWE Aframax — both severely tight and still tightening
USGC Suezmax is the standout on a percentage basis — 4 open vessels against a 6-ship average, 33% below the mean, and the list has drawn 4 vessels week-on-week. That's a sharp move. With no TD route formally assigned to this segment, the demand is likely being absorbed by cross-basin activity or VLCC substitution pressure, but the physical list is genuinely short. Owners here have leverage.
NWE Aframax (TD7) is equally alarming in absolute terms — 38 open against a 55-ship average, 17 vessels below the mean, and the list has tightened by 17 w/w. That's a dramatic draw in a single week and the trend is still tightening. This is the most significant week-on-week shift across the entire Atlantic board.
Notable Shifts
NWE Aframax: −17 w/w — the single largest absolute move on the board. A 31% discount to average and still tightening is a strong physical signal for TD7. Owners should be fixing prompt; charterers are exposed.
USGC Suezmax: −4 w/w — a 4-vessel draw on a 6-vessel average list is proportionally severe. Watch for rate support here even without a formal TD benchmark.
WAF VLCC: +5 w/w — the list has lengthened by 5 vessels week-on-week, moving from what was likely tighter territory toward the average. The trend is now lengthening, which caps the upside for TD3C/TD22 origin competition out of WAF.
WAF Suezmax (TD20): +1 w/w — already very ample at 36% above average and still building. Charterers hold the leverage here; owners are competing for stems.
USGC VLCC (TD22): +2 w/w — 40% above average and lengthening. WTI Midland's competitiveness into Asia would need to improve materially to absorb this overhang.