
Harebrained schemes. Building. Prev: Investor @a16z. Founder @FrankTrusts Forever: Tortured fan @MapleLeafs
San Francisco, CA
Joined September 2011
- Tweets3.9K
- Following1.7K
- Followers14.4K
- Likes13.4K



Pinned Tweet
1/ If you’re a founder you’ve probably heard someone say “oh, I’ve seen this idea before - it didn’t work” or “isn’t this just like that other thing that person/company X tried?”
this thesis aligns with everything i see right now.
- simple is getting cloned immediately
- interesting is extremely competitive and (over) funded
and fwiw complex doesn't actually mean highly complex in that you need to be a gigabrain to understand, it just means it requires time to get it


D’Arcy Coolican retweeted

Be profitable and run your company with maximal agentic loops
You don’t need to sell more of your co anymore
$10M profit per year reinvested is like an annual Series A no dilution
The best startups do this now. No whinging about the Series A/B crunch.
You don’t need saving.

Series A and Series B are the hardest rounds for founders today.
Founders launch a vertical AI SaaS company. They reach $1M-$3M ARR in 2 years or $5M-$10M in 3-4 years.
They go out to market with their 1x-3x growth. Almost no interest from investors.
If it's not the right category or a deep, long-term conviction bet, most investors stay away.
Founders are stuck with large pref stacks and a market that doesn't value this growth. They are neither sustainable (at their current burn) nor venture-fundable (without growth).
The exit options (if available) don't leave much for the team. In most cases, founders are required to join the acquiring company (but they aren't interested).
I talk to many founders who have been misadvised, and they keep grinding without making progress.
The Series A or B that didn't happen won't magically happen in 1 year with a little more progress. If the market moves much faster than your company progresses, you will always be behind. If you are told today to hit some metrics and come back, the market will have already moved by the time you return.
how I've seen this work well in early stage companies (will use head of people version as example)
- it's actually two roles not one. The "founder peer" is ~10 hours a week. Also hire a junior HR ops person
- trying recruit someone who a true peer to be your FT Head of People is extremely difficult (as tweet below notes). if they are that elite, the opportunity costs are too high for them to take that role unless it's actually an n of 1 type company. But flexibility and/or ability to spread across 4-5 companies can make it compelling
- Their hours should be spent with founder and direct team going through the most difficult issues, not managing the HRIS or sending out offer letters (that what the junior ops person is for). They're also on call for emergencies.
- Junior ops person handles the day to day issues and logistics and reports to legal/GC but has a mentor in the "founder peer". Founder peer reports direct to CEO.
- "People issues" are routed through managers and skip levels rather than being routed to HR. If issue warrants it, it goes to legal and dealth with by the GC (with guidance). No standing "People" org to soak up problems without authority to handle them
- Founder peer needs to be both in it for the long term and in it deep enough to know the org, the personalities and the issues. Can't be an "advisor" or HR consultant that dips in and out.

investors and founder are often playing very different games.
play your own game. run your own race. win.

Where are all the “distribution is a moat and hence raise a lot of money” investors today..
when the *checks notes* incumbents are flexing their distribution muscle.
It’s SO important to stay first principles on what matters. Find your unfair advantages. Build a great product with high retention and ideally network effects. Use capital as a weapon to compound and not as destiny. And, finally figure out how to be a self sustaining business because this money spigot will dry.
And, that is so freaking hard. It’s never been easy - especially not now.
(PS: This is not a subtweet on any company, but more so on the investors who’ll dole out terrible advice and move to the next company in their portfolio when that one crashes and burns)
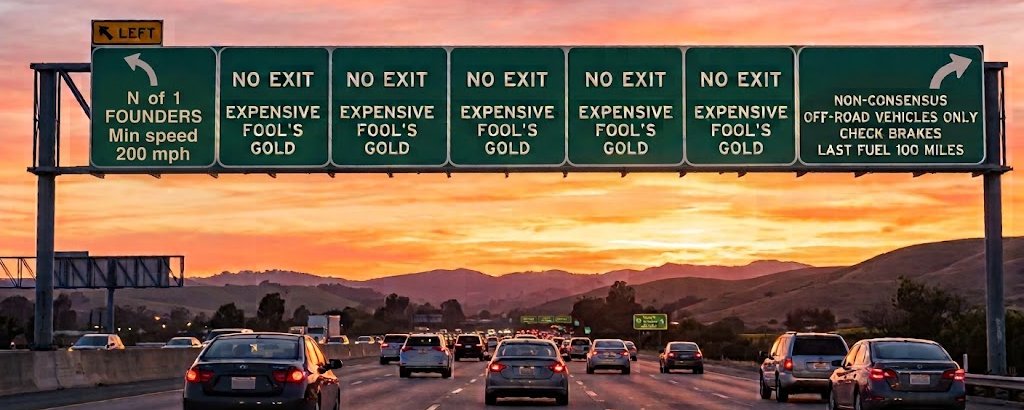
this is where silicon valley is today
founders and investors are usually playing very different games
as a founder, choose your game -- and investors -- wisely

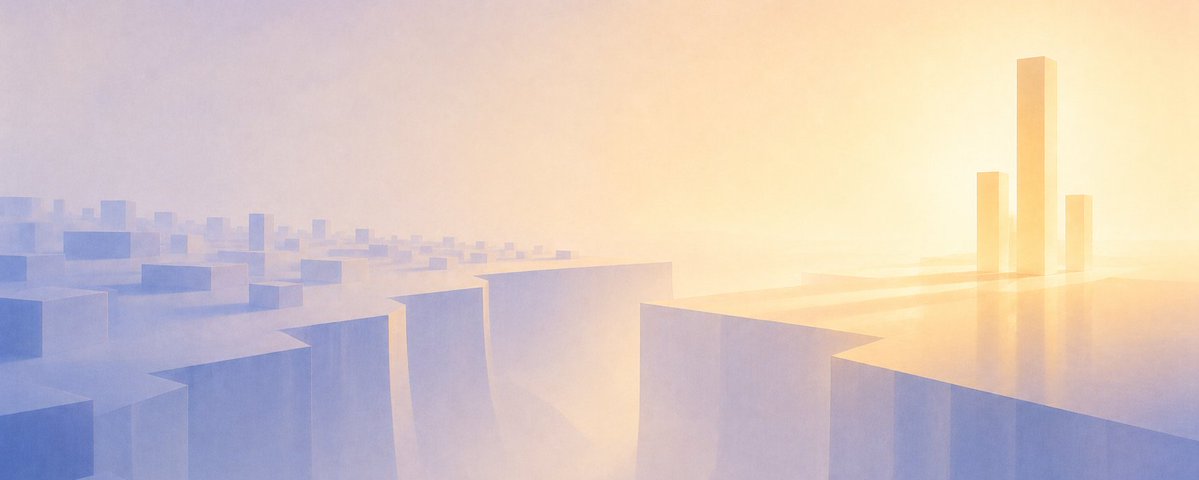
knowing how to do a reference call is such a hidden superpower
darcy.substack.com/p/how-to-…

Yesterday, the founder of a well-known, successful company called me to reference check two people he was considering for a senior role. He wasn’t looking for reassurance. He was genuinely trying to understand them, including anything that might cause him to reconsider either hire. He’s called me before about other hires, including people who wouldn’t even report directly to him. He doesn’t delegate this to others. He calls himself. I'm sure that kind of rigor is part of why his company has been so successful.
The call stuck with me because it happens so rarely. Many people I’ve worked closely with have gone on to senior roles, including C-level positions, at other companies. It’s shocking how infrequently I get called. These are among the most consequential decisions a founder makes, yet companies routinely make them without talking to people who actually worked closely with the candidate.
Part of the problem is timing. Most reference checks happen after the hiring manager has effectively decided to make the hire. You like the candidate, you’ve invested weeks in the process, and you’re under pressure to fill the role. You want the process to be over, so you’re looking for validation rather than truth. That defeats the purpose of doing reference checks.
A real reference check should attempt to disconfirm what you already believe. What am I missing? Where is this person weaker than they appear? What will I wish I had known six months after they start? You aren’t trying to build the case for the hire. You’re trying to find the flaw in the case while you can still do something about it.
I’ve learned a few rules. Start by putting limited weight on the references the candidate gives you. Nobody hands you the name of the boss or colleague who thought they were a disaster. The references that matter most are blind references, so find former bosses, peers, direct reports, and customers who aren’t on the candidate’s list. Each has seen the person from a different angle.
You also have to adjust for human nature. Most people don’t like being brutally honest when they know their words could affect someone’s career. They inflate praise and soften criticism, so my rule of thumb is to discount the positive by 3x and amplify the negative by 3x. That gets you closer to a balanced view.
When someone says, "He's a great leader, although some very good people struggled working for him," the second half of that sentence matters far more than the first. Who struggled, why, and where are those people now? When someone says, "She surrounds herself with people she trusts," ask whether those are the best people for the job or simply people who always agree with her. Hesitations, qualifications, and carefully chosen words often tell you more than the compliments.
Ask questions that make vague answers difficult. What would their direct reports say is the hardest part of working for them? What feedback did you give them repeatedly? What was their biggest blind spot? How do they behave when things are going badly? Tell me about a serious conflict they had and how they handled it. If this hire fails, what is the most likely reason? Would you hire them again?
My favorite is a forced ranking. Of everyone you’ve worked with in a similar role, where does this person rank? Top 1%? Top 10%? Top 25%? Then ask why. Adjectives can be misleading. Rankings force people to make an actual judgment and explain it.
I’ve hired many exceptional people and made some bad hires. The most important lesson I’ve learned is that the goal of a reference check isn’t to prove you made the right decision. It’s to discover why you might be making the wrong one while you can still change it.
unpopular opinion: the generational companies will come from these "slow growth" / "small tam" startups
- building from first principles of networks and defensability, not chasing low retention growth
- niche TAM's will be 100x bigger than expected. VCs always get TAM wrong. they size based on today's market vs what market will be if it works
- the markets aren't saturated with copycats
you can feel the zeitgeist turning on this. i don't know if that is good or bad tbh. kind of nice to be out of style

2 interesting arbs right now in VC:
“Slow” growth - everyone is obsessed with funding the companies going 1 to 10m+ in ARR, lots of overlooked businesses going 1 to 3m.
“Small” TAMs - everyone is obsessed with funding the next trillion-dollar companies. Lots of great outcomes to be had with funding the next 1-10b companies at the right entry price (particularly for smaller funds).
unpopular opinion: the solution is networks not verticalization. network effects have changed dramatically with AI but they are still the best (only?) form of defensability from both the AI labs and the inevitable competition


dude is living every founder's wet dream

Anthropic’s last round was apparently a bloodbath behind the scenes. A GP at a prominent fund had dinner with Dario three times before their allocation was slashed to zero. At least four other tier-one funds got pulled at the last minute.
Their crime? Passing on the Series B, the hardest round Dario ever had to raise (led by Spark). In venture conviction is all that counts.
D’Arcy Coolican retweeted
Announcing Weekend Fund IV, backed by operators and founders (and maybe you).
When we raised Weekend Fund III, we did something different.
Toward the end of our raise, we announced the fund in public and accepted applications from LPs.
Our goal was to make early-stage venture more accessible and align ourselves with an army of operators and founders to help us and the startups we back.
Over 1,000 people expressed interest to join and hundreds did, but there was a problem. Legally, only accredited investors could participate as an LP. Accreditation laws are well-meaning but limit access to the majority of consumers.
With WF IV, @vedikaja_in and I are doing something different.
Like before, we’re onboarding engineers, designers, researchers, data scientists, salespeople, and other domain experts as LPs in the fund. But this time at a larger scale with USVC.
AngelList recently announced USVC, a new kind of fund that’s accessible to everyone, including the non-accredited. It holds positions in private late-stage companies like xAI, Anthropic, OpenAI, Sierra, and Vercel. I personally invested.
Today, they just announced their investment in Weekend Fund IV, one of the first early-stage funds added to their portfolio.
If you’re interested in being a part of Weekend Fund and getting exposure to generational startups mentioned above, visit usvc [dot] com.
Of course, don’t invest what you can’t afford to lose.
Investing in startups is risky and you may lose all your money. USVC shares are illiquid with no guarantee of repurchase.
Consider investment objectives, risks, charges and expenses carefully before investing. Read the prospectus: usvc [dot] com/prospectus.
Also, USVC is currently limited to US citizens. They’re working to open the fund to other geographies.
Lastly, my DMs are open. :)

can anyone connect me to someone @cohere for something urgent? 🙏
dms open
i am trying to spend lots of money on their product, but it is proving difficult
seems like the tech zeitgeist is turning away from pure growth / $0-$100M in 45 seconds / momentum is the moat stuff to what true network effects look like now
ive had more intelligent conversations about this in the last 3 days than in the previous 2 years.
nature is healing


i can go on a long rant about what makes a good seed investor, but easier to just say that if you have the chance to work with @semil and @aashaysanghvi_, just do it. we did.
excited to see them keep going.

[brief update]
we have a new set of funds for @haystackvc
announcing haystack 8 plus more, but it's really about my teammates @aashaysanghvi_ & @DivyaDhulipala
thank you to all of our frequent ecosystem co-conspirators, our LPs, our co-investors, our founders. i'm very grateful 🙏 and this is the most fun role in the world!
semilshah.com/2026/04/26/new…