

Cardiac Surgeon, Medical Researcher & Innovator. Value Equity Investor since 21. Tweets abt Stocks are Educational & NOT Recommendations.
Karnataka/Gujarat
Joined March 2020
- Tweets5.5K
- Following0
- Followers37.3K
- Likes2.8K




Pinned Tweet
“SCIENTIFIC Approach” in Everything that You Do Liberates You From Mediocrity For Life!
EDUCATION Empowers Like No Other & With Education Must Come HUMILITY!
PERFECTION Comes From Repetition!
Create Your Own Destiny through VISION, CONVICTION, PASSION & INEXHAUSTIBLE PATIENCE!


He called Copper (beneficiary Hind Copper, etc) perfectly last year at inflection point.
Now, he recently called for Rock Phosphate/SSP fertiliser in view of self sufficiency.
One SME fits perfectly here after stellar H1.
CMP - 78
EPS - 11.92
P/E - 6.5
IPO at 99, listing at 197.
Technically perfect ROUNDING BOTTOM.
Probable re-rating candidate.


The world is facing a huge shortage of sulphur which is the most important input into making fertilisers.
Our hardworking farmers who have consistently delivered self-sufficiency in food should not face any challenge on fertilisers.
Vedanta has a plan for a unique 1.5 MTPA fertilisers plant. Apart from the fertilisers itself, we are going to produce the largest amount of sulphur, and rock phosphate, which we currently import.
Let all of us be united in this mission. Whatever is in our way - be it compliance or technical, let us solve on a war footing.
This is a project primarily in national interest, not commercial interest. We must complete this plant to serve our farmers. And to help reduce unnecessary dependence on imports.


What is the crime of Indian Retail Investors (Shock Absorbers)?
Why such SECOND CLASS Treatment to “Indians” in our own country?
Either reduce/abolish LTCG for all, or DO NOT at all.
PREFERENTIAL TREATMENT for FOREIGNERs (FIIs) is unfair & not acceptable!
@FinMinIndia @PMOIndia

FROM REUTERS
SEBI PROPOSES GOVERNMENT REMOVE LONG-TERM CAPITAL GAINS TAX FOR FOREIGN INVESTORS
#BIGBREAKING
1000+ Up on Nifty in the month since the tweet.
NIFTY
APR 2026 - Iraq/Us War Low - 22,182
APR 2025 - US Tariff Low - 21,743
JUN 2024 - Election Exit poll/Result Low - 21,281
Today’s Low - 22,217 (still above all previous Lows)
Present Levels & levels towards 21,700-21,200 - is the Real SIP time for NIFTY ETF patrons.
NOTE 1 : There is still a GAP (20,183-20,158) from Nov-Dec 2023 Nifty monthly, in case some near term negative surprises.
NOTE 2 : RSI still 43.94. Only when it hits late 30s (say 36-39), would I get much stronger bottoming signal. Personal view.
Dr. Ganesh Kumar Ammannaya retweeted

#Sugar gains as global #supply concerns persist, but renewed Brazilian rains could pressure cane production and #exports. hubs.ly/Q04CB3w70 #softs #futures #MarkBowman

(NOT a Recommendation. Merely a Stock Idea for Further Research. NO BUY/SELL Advice)
Reserves 574 Cr
+ Additionally, Cash in hand 75 Cr
Debt 0 (DEBT FREE)
Value of Listed Stock Investment 242 Cr
(~15% holding in Seshashayee paper, ~6% holding in High Energy Batteries)
Market Cap - 286 Cr
EPS - 65.84
PE - 5.06
Stellar Q2, all time Best!
Highest ever margins.
Global Sugar prices on the move upwards. India Sugar deficit + Brazil deficit (both due to El Niño effects) to keep supply pressure.
Dividend paying Co.
Book Value = 677 (trading now at half book)
Probably the most undervalued Sugar stock in the world!
Also, compare the results of other Sugar Cos of last 2 Qtrs, this one seems light years ahead!
It knows how to make hay while the sunlight shines.
Icing on the cake-
131 Cr SUGAR “inventory” (All Time HIGH) at the end of Q2.
So, Can expect better Q3 as well!
Normal winter monsoon ongoing in South India (Vs monsoon deficit in rest of India this year). Hence, Q4 promises to be decent as well.


Glad as well as proud to have pioneering publications in the field of Keyhole Heart Bypass 🙏
academic.oup.com/jscr/articl…

NIFTY
APR 2026 - Iraq/Us War Low - 22,182
APR 2025 - US Tariff Low - 21,743
JUN 2024 - Election Exit poll/Result Low - 21,281
Today’s Low - 22,217 (still above all previous Lows)
Present Levels & levels towards 21,700-21,200 - is the Real SIP time for NIFTY ETF patrons.
NOTE 1 : There is still a GAP (20,183-20,158) from Nov-Dec 2023 Nifty monthly, in case some near term negative surprises.
NOTE 2 : RSI still 43.94. Only when it hits late 30s (say 36-39), would I get much stronger bottoming signal. Personal view.
GOOD UPDATEs by management through investor presentation today.
Salient points:
- FRESH ORDER WIN - 140 CR ETHANOL Order win from Oil marketing Cos apart from Existing 400 Cr Order Book (till OCT 2026).
Same announced through separate Exchange notification as well.
- In Q1, Co had 20 DAYS ethanol plant SHUTDOWN. Considering this Co has had much better capacity utilisation as Co still managed flat revenue YoY .
- From AUG End, entire 282 KLPD to operate at FULL CAPACITY. That’s 100% Capacity utilisation expected.
- NEW LAUNCHES in FMCG Segment.
- Reiterated 66-70 Cr PAT for this FY.


PE now 10.17 (was 11.3 before Q1)
Q1 margins at ATH
Q4 carried exceptional item of 5 Cr insurance gain. Q1 PAT 12.5 Cr on 156 Cr top line Vs Q4 PAT 14.8 Cr on 243 Cr top line (PAT Margin UP to 8% Vs 6%)
Management guidance - 950 Cr Top line, 66-70 Cr PAT for FY27
Hence, rest of FY (Q2, Q3, Q4) - average can expected to be 265 Cr Top line with PAT of 17.8 Cr (BASE CASE SCENARIO)
However, with some major contract from Oil marketing Cos, Ethanol off take to full utilisation, Management confident of 1100 Cr Top line.
Overall, good Nos, MARGINS at ALL TIME BEST.
Once out of ESM coming FRI can have better liquidity with fair price discovery.
(NO ADVICE. NO BUY/SELL RECOMMENDATION)


PE now 10.17 (was 11.3 before Q1)
Q1 margins at ATH
Q4 carried exceptional item of 5 Cr insurance gain. Q1 PAT 12.5 Cr on 156 Cr top line Vs Q4 PAT 14.8 Cr on 243 Cr top line (PAT Margin UP to 8% Vs 6%)
Management guidance - 950 Cr Top line, 66-70 Cr PAT for FY27
Hence, rest of FY (Q2, Q3, Q4) - average can expected to be 265 Cr Top line with PAT of 17.8 Cr (BASE CASE SCENARIO)
However, with some major contract from Oil marketing Cos, Ethanol off take to full utilisation, Management confident of 1100 Cr Top line.
Overall, good Nos, MARGINS at ALL TIME BEST.
Once out of ESM coming FRI can have better liquidity with fair price discovery.
(NO ADVICE. NO BUY/SELL RECOMMENDATION)


Self explanatory.

ORBIT EXPORTS - Interesting MicroCap (477 Cr Mkt cap) that merits further research.
Good quality promoters - have done 3 Buy Backs - Rs 180 (2018), Rs 245 (2022), Rs 250 (2024). Consistently raised stake over last 8 yrs. Intermittent tiny drop due to ESOP.
Last 5 months, been trading even below 2018 Buy Back price.
H2FY26 may see 1.5X Expansion, expected to be in place this Q2.
Negligible Debt, Consistently good Cash Flow.
Makes, a case for further in depth research.
(NOT A RECOMMENDATION / NOT INVESTMENT ADVICE, Merely a Stock Idea for further Study)

Not bad at all, Up ~60% in 7 months.
NO Buy/Sell Advice.

FERMENTA BIOTECH - Interesting Stock Idea that merits further research.
(NOT A RECOMMENDATION / NOT INVESTMENT ADVICE, Merely a Stock Idea for further in-depth Study)
Currently trading at merely 8 PE on TTM EPS Rs 38.06 (Historical PE - last 10 yrs Mean PE 19.40, Lifetime avg PE 15).
ROCE 23%, ROE 24.9% (EBIDTA margin H1 FY26 25.9%) with excellent H1/Q2 FY26 Nos.
LATEST Development - (first 2 images) of MAJOR CAPEX.
VITAMIN D3 Moat - World leader (among Top 3 & the Only Indian Co) in Vitamin D3 (niche player)
Recent PATENT for its plant based (Vegan) Vitamin D3 expected to significantly expand margins as these command much higher premiums (image 3 gives a very rough idea about premium margins), expected to be a Key Growth Driver in core business, also for which CAPEX is primarily planned for this FY26 & FY27.
Increasing awareness worldwide about role of Vitamin D3 in virtually every organ system of human body, ill effects of its deficiency such as increased cardiovascular risks, infertility & recent European studies showing improved survival in Cancer patients on Vitamin D3 supplements, apart from proven benefits such as anti-ageing, anti cancer & immunity boosting effects, one of the mainstays in the treatment of osteoporosis (weak bones particularly elderly) etc., augurs well for wide scale use across all geographies.
Scale Up in GERMAN Operations - H1 FY26 revenue 34.3 Cr (Up 194% YoY) & EBIDTA 7.7 Cr (Up 103% YoY).
- Overall EU share increasing to 29% (from 27%),
- US share dropping to 13% (from 15%).
- Rest Domestic - 40%,
- Others-18%
Expanding to Other Vitamins - Vitamins K1 (one of the few global suppliers), Vitamin- fortified Rice (Govt schemes, like in AP) with plans of Vitamin A, E over next 5 yrs.
MoU with NIFTEM to establish Centre of excellence for Food Fortification enhancing public nutrition.
Additionally, Environmental solutions including Waste WATER management. fermentabiotech.com/environm…
Co seems to be focusing keenly on this segment as evidenced by further investment of Rs 7.9 Cr more recently in the subsidiary.
Result of this increased focus on Environmental Solutions Subsidiary Visible as - H1 Revenue up 127% in H1 FY26 (to 15.1 Cr, from 6.6 Cr YoY).
Co has been unlocking Value from Real Estate well. Has excellent LAND BANK primarily in Thane 5.5 acres (apart from Thane One) & 45 acres in Takwe, Pune, alongside steady leasehold income like Thane One.
Debt levels cut down more than half from 239 to 112 Cr, with Turnaround Positive Cash Flow.
Promoter stake has increased steadily from 59 to 64% over last 2 yrs with No of Retail shareholders coming down from 17 K to 13 K during times of extreme stress for the Co until the recent Turnaround.
Technically, C&H with probably a “W” shaped Bottom (256, that’s a DOUBLE BOTTOM, also the Key Support) in the handle seems supportive & Key multi-year resistance being (also ATH) ~450, which it tested 2-3 times in the last 7 yrs.
Thus, makes a case for further in-depth research.
(NOT A RECOMMENDATION / NOT INVESTMENT ADVICE, Merely a Stock Idea for further Study)


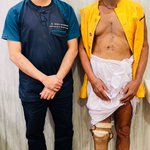
Most Satisfying for me to perform KEYHOLE HEART BYPASS (minimally invasive CABG) for the poorest of the poor for FREE to the patient under PMJAY 🙏 @AyushmanNHA
A SPECIALLY-ABLED Sadhu Maharaj from a village nearby AMRELI, operated for Keyhole Heart Bypass, back on his feet performing poojas in his temple in just 2 weeks.
Grateful!


Critical Surgeries for poorest of the poor under Ayushman Bharat #PMJAY in remotest areas of the country.
A poor farmer gets Free Heart Surgery in Bhuj, Kutch region of Gujarat, without the need to travel to any metro city and got back in the fields in no time.
#AyushmanBharat
