


KryptoKnight retweeted

$SIVE earnings just got released:
$1.2 billion revenue opportunity pipeline growth up 268% from December (incredible growth).
Last ER: $799M (this was a surprise, likely linked to Jabil)
July 2026: ~$1.2B (hinting more either more customer engagements than what's announced or larger volume ramps within programs).
"Sivers continued to reallocate resources from NRE projects toward product ramp preparation.
Sivers expects the impact of this transition to become visible in Q4 2026 and accelerate through 2027 as multiple programs progress toward volume production."
Makes sense on timelines.
Current financials reflect a qualification-stage player before volume ramp:
- $5.64M in revenue (reducing NRE activity, shifting to volume ramps soon)
-$3.72M in adjusted EBITDA (what to look at given one-off charges, eg. social security accounting expense)
Key thing to look at is earnings call in 30 minutes, very excited so far.

KryptoKnight retweeted
"Severe InP Shortage Triggers Largest Price Hike Ever" - $AXTI.
Suppliers have bluntly stated that "even if you have the money, you still may not be able to get the material" (lol).
- Industry sources revealed that InP substrate prices began rising in Q4 last year and was the fourth consecutive substrate price hike.
- The latest Q4 hike is expected to be >10%,
- Meanwhile, prices for epitaxial wafers made from those substrates have already been raised two times, and the market is moving toward a 3rd consecutive increase in Q4. (I also wrote a thesis on $IQE, which benefits here too).
Article states VPEC, Landmark, IET benefits (Taiwan centric reporting).
I did predict this last year... The bottleneck is real, but I do have higher expectations for price hikes that comes next.
Glad it's starting to play out.


KryptoKnight retweeted
I personally see it as extreme short term deleveraging that overshot many individual names.
- $BE to $TER reported blowout results, with Bloom reporting 166% Y/Y rev growth + expanding margins + raised 2026 guidance... Teradyne reported 104% Y/Y revenue growth with 300%+ EPS growth.
Your leading optical players over in China reported amazing preliminary earnings + extremely strong read through for the Western photonics sector.
Think earnings season tend to remind markets about continued AI acceleration. I'm expecting $LITE, $SNDK / SK Hynix, and sector leader ERs to continue that trend.
But it does feel like markets are rewarding existing acceleration more rather than future growth a year out over near-term revisions as seen with $AMKR.
But as a TLDR, looks very positive for the themes I'm tracking.
- Then you have $GOOGL capex raised to $195-$205B, which is typically the biggest AI demand signal from hyperscalers.
- 77% 0bps change est. next FOMC decision from prediction markets. Trump administration on Monday called for the Fed to lower interest rates.
So your 3x rate hikes fears this year seem kinda overblown.
- Chinese fears from DUV to $CXMT overflooding are extremely overblown as well. We see this with every sector from time to time until people remember that lasers or HBM bottlenecks for a reason.
As for personal thoughts, it was unhealthy seeing everything rise up or down together, especially with these themes. But I'm personally not worried since I have full conviction in my names, especially optical interconnects like $SIVE or $AAOI.
$META compute and $GOOGL GCP margins/growth shows increasing demand for $NBIS and similar neocloud business models.
$META + other hyperscaler notes around LTAs with $SNDK and Samsung/SK Hynix, $MU point to structural memory demand.
Can go on and on...
But when you have Jim Cramer telling every margined DC trader to "sell everything" at market open and news saying there's an AI bubble.
I do hate it when others say "it's dropping so sell". My belief is that the important thing to look is accelerating revenue/EPS growth. And if that thesis stays in-tact with revenue acceleration in line with hyperscaler capex.
TLDR: I see signs of AI demand / revenue acceleration, hyperscaler capex is one of the most important things to track.
And my guess is that we'll see the theme recover broadly. But I can't predict what hour, day, or week that happens.


KryptoKnight retweeted
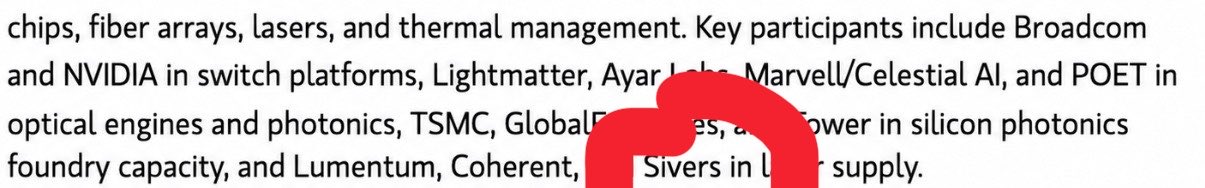
Morgan Stanley note on CPO today. Key participants include:
- $SIVE, $COHR, and $LITE in laser supply
- Broadcom and Nvidia in switch platforms
- Lightmatter, Ayar Labs, Marvell/Celestial, and POET in optical engines and photonics,
- $TSM, $GFS, and $TSEM in silicon photonics foundry capacity
I’ve covered all of these before, like Tower Semi.
But I’m especially happy that Morgan Stanley validated my research that $SIVE is one of the critical global players in CPO.
A small $1.5B laser company next to your two leading $60B+ companies…
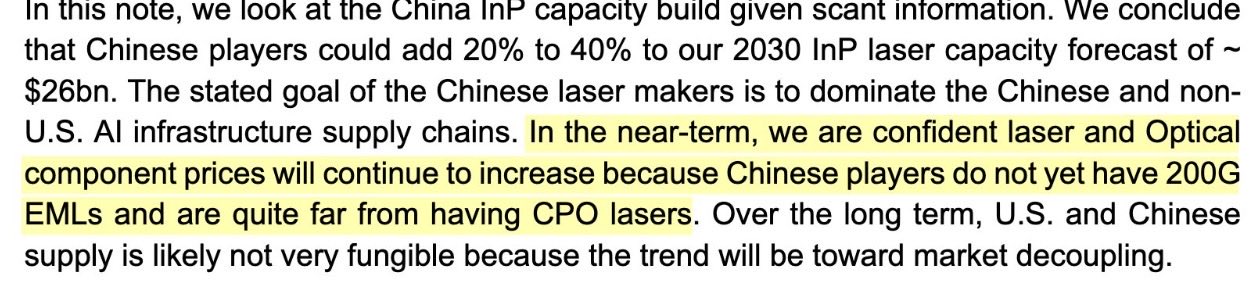
If you also synthesize Rosenblatt Securities recent note that China laser suppliers were quite far from having CPO lasers.
This kinda magnifies importance of the three Western leaders of that laser chokepoint.
KryptoKnight retweeted
Three new $SIVE insider purchases today.
Most notably: $SIVEF CEO Vikram bought 1,000,000 SEK worth of shares on the open market today.
This is following the massive drop on Sivers stock following 2 misleading CPO delay reports, Meta Compute headlines, and another insider sale report from another photonics director.
Typically, insider sells for any number of reasons. But having the CEO buy on the open-market is the clearest signal in management confidence.
Following $GFS, $JBL, and other laser supplier partnerships, and his goal of NASDAQ listing in the near term.
Feels like the CEO sees a clear potential for Sivers to become the next photonics giant (myself included).

$SIVE fell today on an EFN article claiming the photonics chief sold his entire holding — presented as alarming insider panic. Here is what I think the article can have missed.
Andrew McKee founded CST now Sivers Photonics in 1999— 27 years ago. He built the photonics business from scratch. Earlier this year Alex McCann appeared publicly as the new MD of Sivers Photonics in April/May communications. McKee moved totechnology role only. His Q1 and Q2 share sales seems to align with this transition and was probably sold (if sold at all in full) parts of it even before share re-rating.
My take is that is was done probably with no negative view on the company's prospects. A man monetizing his life's work after almost 30 years of building a company is not insider panic. IMO this is probably more a career ending on his own terms. He deserves it for sure. Even if he sold over 6 months, IMO this is still not a major negative signal.
Three things EFN did not check: A) Holdings has known blind spots — transfers to holding companies, ISK structures and family vehicles are not captured. Did anyone verify McKee holds zero shares in any structure? B) One option program was realized in early July. If McKee sold old shares to participate that is not a major negative signal (he is not insider hence would not report sell or buy) — Holdings would not show this yet since it was in early July C) The role change probably happened before most shares was sold, Context matters.
Later in the afternoon two board members has publicly shared insider purchases.
Todd Thomson — board member, former Citigroup CFO, — bought 535,000 SEK on-market today at 42.80 SEK into the panic. Karin Raj bought 460,000 SEK at 34.68 SEK — the intraday low. Both reported to FI same day. People with more information about the full picture, that also had been part of approving today clarifications around the Q-reports and US Nasdaq listing.
Update Vikram CEO have also aquired shares for approximately 1.000.000 SEK
Summing up: Journalism created the dip. Insiders bought it.
What's X view on today?

KryptoKnight retweeted
Let’s put it this way:
Retail thinks a 30-60% drop is a “falling knife” where bagholders will never recover.
And they end up panic selling after seeing swiggly line TAs and people comparing valuable chokepoints to memes.
I see it as long term ownership over:
- the next hyperscaler with $NBIS, projecting $7-9B ARR Q4
- 40% of the InP supply chain with $AXTI
- leader of the next optical shift with $SIVE with CW DFB lasers
- leader of US humanoids with $CCXI inside a future trillion dollar theme
And so on… At cheaper valuations.
While I might do things like lowering margin or hedging with my own portfolio, I’m personally not panicking when something drops if the thesis didn’t change.
NFA and obviously depends on people’s investing timeframes:
Since a crash would be life changing for people that depend on investing for rent or tuition. (Which is why I personally think others should do their own DD and choose longs in line with their own risk profile)
But my personal goal is maximizing exposure to the next-gen supercycles before they hit.
I think institutions think the same way as well, which is why there’s a lot of induced volatility along the way to maximize their exposure.
If a thesis ends up correct, the valuation should be reflected in the long run.

KryptoKnight retweeted
Nomura’s report cites $AXTI and $IQE as the leading players.
Then regarding ASP updates:
- 2in InP substrate price hike 42-76%
- 3in InP substrates price hike 78%
- 2in EML Epiwafer price hike 50-75%
- 3in CW Epiwafer price hike ~40%+
- Prices lower domestically in China as expected.
Hyperscalers bottlenecking upstream photonics confirmation validation… on all fronts from pricing, demand, to supply shortages.
My personal expectation was that price hikes would keep going up like $SNDK given ramping optical demand.
We’ll see if this turns out right given another 2 years of the demand curve.


Holding my shares as I’m averaging $2.46 USD per. Long $SIVE

I personally think $SIVE can be the next $LITE.
In the past few months alone, we've seen:
1. Partnerships with O-Net pushing ELS into mass production
2. $JBL 1.6T LRO mass production signals with "relatively dramatic moats" for pluggables using Sivers.
3. $GFS SCALE reference level laser for hyperscalers with pluggable, NPO, CPO.
-> -> where $AMD and others went to GFS for CPO.
4. Ayar, which joined $NVDA NVLink for CPO
-> -> which removed Lumentum/Macom from their website and likely made Sivers their primary laser supplier.
-> -> AlChip likely Trainium win from Amazon price placement (Ayar's customer)
-> -> GUC rack level design in with Ayar.
-> -> Raised $500m for mass production by AMD, Alchip, Mediatek, and NVIDIA
5. ~ $AEVA starting HVM H2 2026.
6. $POET starting HVM H2 2026 with hyperscaler suppliers like Lumilens ("top 3 hyperscaler initial customer")
7. TFLN + $SIVE CW Lasers with Lightium
8. Likely direct relationships with $MRVL Celestial and CPO players like Lightelligence/Lightmatter.
9. Multiple new undisclosed relationships for pluggables following Jabil in their quarterly transcripts
With new Trendforce reports that $AMD and other hyperscalers are trying to source LTAs for CW laser sources, serving as a direct catalyst for independent CW sources.
So when hyperscaler suppliers from Jabil to O-Net are incentivized to mass produce as many as they can: That's very material for revenue for Sivers relative to current valuations, and it looks like just a waiting game.
Even in the past week:
- $SIVE raised an oversubscribed institutional round for volume ramp... This is very nuanced since Sivers is fab-lite so it's not going to in-house foundry capex to scale. Likely toward Win Semi and others (they mentioned other partners too), for laser scaling + foundry allocations.
So this is likely signaling material for revenue ramp is coming.
- Sivers also mentioned NASDAQ listing completion targeted in the next few quarters (probably H2 2026 or Q1 2027 is my est. timeframe).
This would fund M&A efforts, since it's impossible with the fundraising environments in local Swedish markets.
As for becoming the next $LITE:
M&A makes their lasers more valuable, so downstream IP acqusition -> into contract manufacturing like $FN, and others to make the full 1.6T pluggable or optical engines. Is how they get there, since laser array ASP scaling that people are modeling off of, wouldn't command a $60B+ valuations.
There's going to be a lot of bridge architectures like NPO/pluggables, etc and noise around certain architectural delays in the meantime.
But markets misunderstand laser companies like $LITE, $SIVE, $AAOI and others are used across different architectures compared to if you just look at certain passive optical components.
So markets see "CPO delay headlines" algos sell off laser companies that benefit from other architectures.
Being included in the pluggable 1.6T ramp to CPO scale out (Which Sivers is included in), helps bridge revenue waiting gaps until scale up inflection point H2 2027.
I'm personally holding long term, since I haven't seen a ~$1.4B company mapping to this many hyperscalers before.
TLDR:
- Waiting on volume ramps from different architectures to play out across their hyperscaler supplier mapping
-> 1.6T LRO/CPO scale out late H2 2026 start into high volume ramp 2027
-> H2 2027 CPO scale up volume ramp
- Waiting on NASDAQ listing likely H2 2026/Q1 2027 for M&A efforts to fully take off, unless Sivers get more creative with equity financing in the meantime.
KryptoKnight retweeted
Everyone chases memory names like $MU, $SNDK and neoclouds like $NBIS. Everyone is ignoring the company which grows the compound semiconductor wafers under the optics.
$IQE is what SemiconductorX's supply chain atlas calls the dominant merchant GaAs epitaxy house, and a leading independent InP epi supplier. At 45p it trades at ~5x forward sales. Its closest listed peer trades near 75x. Same layer of the supply chain.
The III-V chain has three layers. Substrate is the bare wafer. Epitaxy grows the active laser and transistor layers on top. Device fabs turn epi into lasers, radar chips and transceivers. $IQE is the middle layer. The one that carries the IP.
One epi platform feeds six end markets:
> InP for the fastest datacenter optical transceivers
> InP HEMT above 100 GHz for defence radar and satcom
> GaAs power amps for smartphones and 5G
> GaAs VCSELs for 3D sensing and datacom
> GaSb for infrared sensing
> GaN for power and RF
And the validators keep stacking. Real customers, real commitments:
> $TSEM Tower Semiconductor. Multi year InP supply signed June 2026 with contracted minimum volumes, feeding Tower's $1.3B 2027 silicon photonics book. Prior IP dispute settled in the same deal.
> MACOM. £45m invested, two board seats, InP and GaN supply agreements.
> $LITE Lumentum. Renewed multi year VCSEL supply in Dec 2025.
> $XFAB X-Fab. Joint development deal for a turnkey GaN power platform. Their CTO called it combining X-Fab device expertise with "IQE's epitaxy leadership." A foundry does not build a platform on outdated tools.
The tailwind: InP is in a growth phase on AI datacom, supply is tightening, and the supplier base is not expanding fast. Per the same atlas, the players who qualify 6 inch InP capture the next demand cycle. $IQE demonstrated 6 inch InP in 2023 and runs 200mm GaAs today.
$3081 LandMark Optoelectronics grows the same III-V laser epi with the same OMVPE method for the same AI optical demand, runs 37% EBITDA margins, and trades near 75x forward sales. $IQE prints ~5x on a fixed cost base that management says has ample capacity to support significant production increases with no expansion capex needed. The margin gap is mostly utilisation. The multiple gap is the opportunity.
Source on the supply chain structure: semiconductorx.com/wafer-pro…
X-Fab quote: iqep.com/media/press-release…
September H1 print is the catalyst. InP quantified as a revenue line for the first time.
I’m long $IQE. Just my 2c 🙈


$IQE
The market has yet to fully understand that when III-V demand begins to scale across robotics, defence, autonomous driving, data centres, and other frontier industries, the ability to deliver large-diameter, high-yield epitaxy will become one of the most critical bottlenecks in the entire supply chain.
KryptoKnight retweeted
Photonics is backed by actual revenue numbers and it's an architectural shift championed by $NVDA.
Quantum barely has any revenue.
$LITE is completely sold out for the next 2 years (per $POET AGM) likely starting into 2029. Lumentum is so strained that they buy CW lasers off competitors (earnings transcript)
$COHR is bottlenecked, so they buy EML off Lumentum.
Then, $AAOI is coming in with Made-in-America independent CW capacity, are projecting $1.4B/quarterly revenue ending H1 2027 of a stupid $9.3B MC today.
So all the CW capacity from independent players who have it now like $AAOI or $SIVE are likely to become scarce resources.
Many other hyperscalers have already started LTA discussions (per Trendforce). And players like $AMD are currently talking with players such as $AAOI (Rosenblatt channel checks).
Thematically, next 2 years is 9x TAM to US$154B per GS reports, especially with 16x/45x dollar content increase in scale out/scale up.
Then there's the overall thematic AI drop from $META, which is widely misunderstood because people conflate what "excess capacity" means. And as UBS mentioned, Meta planning a cloud offering is NOT NEW NEWS.
Bloomberg just has a tendency to publish information that causes doom drops across the semi sector like Nvidia export controls a few months back.
But I'm familiar with what I'm holding so I'm confident in these numbers playing out.
Especially when all the major players are sold out, the fundamentals catch up eventually.

KryptoKnight retweeted

Everyone is expecting a sell off in $SIVE due to AGM meeting today amid 15% dilution.
But most don't realise this is just an authorisation and not an immediate dilution. It gives the board the power to dilute without having to go back to shareholders
They can't dilute till Oct. And dilution now is necessary for Nasdaq dual listing, which is bullish news.
But again, irrational retailers might just sell on the news
KryptoKnight retweeted
Yep, Blackrock has now entered $SIVE positions as passive owners following index listing.
Fidelity Research has shown up as starting direct positions of Sivers too.
Remember when JP Morgan showed up last month with small positions…
Then bought ~5.25% of the company?
This looks like US institutions validated Sivers’s position in photonics and are trying to accumulate positions.

Just seen both BlackRock and Fidelity showing up as $SIVE institutional ownership? Is this completely new?
morningstar.com/stocks/xsto/…

KryptoKnight retweeted
$SIVE almost down 10% today. Brutal. But again, no change in the thesis. Actually got stronger with ALLSPACE 8.2m contract. It's not about the contract size, it's about the validation.
KryptoKnight retweeted
A massive catalyst arrived today with $SIVE:
Sivers announced $8.2M volume orders starting for Space applications (allspace).
This is for Beamforming ICs powering Space LEO/multi-orbit satellite communication.
The bigger implication is not the contract size:
But that Sivers now powers a larger defense prime in $YSS following their allspace acquisition (similar to $MRVL design-in with Celestial).
Which typically leads to more follow-up orders + volume contracts for Sivers, rather than just this specific contract.
Turns out Sivers is also a Space/Defense supply chain chokepoint (ahead of SpaceX IPO) on top of their photonics AI DC sector lasers...
This win aside, I'm expecting more volume ramps to be coming soon as well from their photonics side (looking at you Jabil + other pluggable makers)


ALL.SPACE Awards $8.2M Production Order to Sivers Semiconductors for Ka-Band Beamforming ICs

KryptoKnight retweeted
$AXTI vs $IQE: Some Food for Thought
$AXTI just printed an all time high near $143 in May. It trades north of 50x sales and is still losing money. 12.7% gross margin. Negative net margin.
$IQE trades at roughly 6x sales. It is EBITDA positive. It grows more revenue than $AXTI.
Both sit in the same supply chain. One layer apart. So why the 10x multiple gap?
Let's walk through it.
> $AXTI makes the substrate. The raw InP and GaAs wafer. The blank canvas.
> $IQE grows the epitaxy on top of that substrate. The active laser structure. The part that actually does the work.
> Substrate then epi then device then module. $AXTI is upstream of $IQE. They are not competitors. They are sequential.
In fact $IQE is a customer of the substrate layer. You cannot grow epi without a substrate underneath it.
So why does the market pay 50x sales for the upstream layer and 6x for the layer that adds more value on top?
Here is the answer, and frankly, some of the gap is real.
> $AXTI sits in a duopoly. $AXTI plus Sumitomo plus JX control 80 to 90% of the InP substrate market. That is a cleaner monopoly story than the epi layer where more players compete.
> $AXTI is a pure AI optical play. Over 90% of the business is optical substrate for data centre. One clean narrative. $IQE is five vectors stacked together. Photonics. Wireless. Defence. GaN power. MicroLED. Harder to model. The 40% wireless drop in FY25 masked the 15% photonics growth.
> $AXTI is on Nasdaq. US institutional coverage. There is even a 2x leveraged ETF on it now. $IQE is on LSE. Thinner coverage + Structural discount and lower liquidity.
> $AXTI has a record $100m InP backlog and turns profitable next quarter. Clean visibility.
That explains a lot of the gap. But not all of it. Here is what $IQE has that $AXTI does not.
> Western defence moat. $IQE is Western domiciled. ITAR and export controls make it a qualified supplier for Western military radar, satcom, missile seekers. $AXTI manufactures in China. That same geography is a liability in Western defence. The export control sword cuts the opposite way for each of them.
> Proprietary process IP. $IQE has its own NanoImprint Lithography that patterns laser gratings at wafer scale, production qualified since 2018. That is value add beyond a raw wafer. A substrate is closer to a commodity sold on scarcity.
> Multi vector diversification. The same breadth the market dislikes is also a hedge. $AXTI lives and dies on one end market. $IQE has five.
> It already makes money at the EBITDA line. $AXTI does not yet.
The takeaway and my thoughts:
I am not saying $IQE should trade at $AXTI multiples. The duopoly, the Nasdaq listing, the clean single story and the backlog visibility may justify a real premium for $AXTI.
But a 10x sales gap between two adjacent layers of the same chain, where the cheaper one makes money, has Western defence regulatory protection, holds its own process IP, and grows more revenue, is worth sitting with. $IQE also trades at a fraction of its closest East Asian peer (LandMark Optoelectronics) - a whopping 12x forward sales gap.
What do you think, do you think $IQE is undervalued here? I certainly do.
Just my 2c. I am long $IQE.
- Leki 🐵
KryptoKnight retweeted
GUESS WHAT ANON?
After today’s new news with Ayar joining Nvidia NVLink fusion.
$SIVE is now the laser source for likely:
The entire Nvidia’s NVLink CPO listed supply chain ecosystem partners.
From Marvell Celestial, Lightmatter, and now Ayar today (the three listed in NVLink CPO).
This is why I call $SIVE a structural photonics laser chokepoint over CPO and now Nvidia ecosystem supply chains.
-> Celestial was likely a direct customer to Sivers, not through Poet. (2023 investor presentation mapping), then bought by Marvell.
-> Lightmatter was also listed there as a customer in 2023 investor presentation deck mapping.
And… Guess what else?
Then they all happen to use GlobalFoundries.
Which Sivers is now the GFS silicon photonics foundry-level reference laser (also new news yesterday).
Supply chain mapping all starting to make sense now anon?
Sivers is also likely now the primary laser source for Ayar after they removed Macom/Lumentum their laser supply chain section (now just gfs/sivers), as a cherry on top.
Algorithms completely miss this type of image based mapping.
After this announcement, I personally think current valuations are very undervalued:
Given Sivers now holds one of the most important structural laser chokepoint over Nvidia CPO NVLink ecosystem supply chains.


Wow… new extremely transformative news got released today.
Making a certain photonics company:
The effective upstream laser chokepoint for $NVDA NVLink fusion CPO ecosystem.
With their lasers now in Nvidia’s optical infrastructure supply chains.
Can anyone guess the name?
KryptoKnight retweeted

Let me outline why I'm so bullish on $AEHR:
$AEHR from first principles:
If chips like $NVDA / $AMD/ $INTC fail inside GPUs, that's bad.
It can potentially crash a multi-week AI training run, worth millions in compute.
That's why you need to stress-test chips in advance.
-> You do this via a process called "burn-in" - which is where $AEHR's specialized burn-in machines come in.
Burn-in is where you increase temperatures + voltages above normal operating levels, and run it hard for hours.
The physics is that elevated temperature + voltage speeds up the failure mechanisms.
A weak chip that would've died in normal use instead dies during the burn-in oven...before it ships.
The good chips sail through the process unharmed.
And you've effectively fast-forwarded each chip through infancy + cut out the ones that were going to die.
-> The main reason $AEHR exists is to do the burn-in at the wafer level, before you cut the wafer up:
(A wafer is a disc with hundreds of chips printed on it, not yet separated).
Meaning that $AEHR has the machines to contact every chip on the whole wafer simultaneously.
This is obviously a good thing because it saves time + cost per chip massively.
So very simply: The more machines $AEHR places and the more designs customers run, the more high-margin consumable revenue compounds.
$AEHR also purchased a company called Incal in 2024 to add a package-level burn-in line (Sonoma).
-> Meaning that $AEHR covers:
1. Wafer-level burn-in (WLBI)
2. Package-level burn-in (PLBI)
Plenty of companies like Advantest / $TER / $COHU do test equipment too.
But doing it at the wafer-level is incredibly hard.
$AEHR has the knowledge + patents around the process.
Which makes them a quasi-monopoly in full wafer burn-in.
-> Other than AI processors/chips, they also do testing for:
- SiC + GaN power semis
- Silicon photonics / optical interconnect
- NAND Flash / HBM memory (in development)
-> And orders are starting to inflect:
- $14M WLBI order (Feb 2026) - lead AI processor customer
- Silicon photonics orders (March 2026) - major new data center customer + lead customer follow-on.
- $41M PLBI order (Apr 2026) - largest in company history
All result in H2 2026 bookings >$92M.
I'm personally expecting more orders as data center chip demand sky rockets in the coming years.
Even at just $2.9B MC:
Any order announcement for $AEHR's systems should lead to material revenue flowing into the company.

KryptoKnight retweeted
For $SIVE to become the next $80B+ $LITE.
Sivers is the current laser kingmaker of the optical transition to CPO and 1.6T.
They basically supply lasers to the leading players in the CPO space.
From likely $MRVL Celestial, Lightmatter, Lightelligence, $POET, and others for CPO. before they got big.
And now with large players like $JBL for 1.6T LRO + more test/qualifications underway for pluggables.
They've finally solved the Catch22 problem, and have the attention of the market to pull off foundational CPO related IP acquisitions downstream on NASDAQ listing (or now with equity).
And expand revenue as much as possible from the laser source into:
-> Optical Engine/ELS value.
-> Optical Transceiver IP
Just like $LITE did to drive their valuations from $2B -> $80B in 2 years.
But instead of EML + pluggables, Sivers is doing this for the CPO supercycle, the fastest TAM expansion in history for photonics.
I'm following the story for them to pull this off this David vs. Goliath shift catching up to $LITE.
More than I care about little MC % returns that's happening currently.
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more