

We swing and trade intraday US markets exploiting statistical edges. We investigate the effect of demand/supply imbalance across time-frames and asset-classes
Switzerland
Joined August 2022
- Tweets1.9K
- Following382
- Followers14.4K
- Likes1.6K




Pinned Tweet
🏆 2025 CMT Charles H. Dow Award 🏆
Extremely proud to share that our paper “A Century of Profitable Industry Trends” has been awarded the 2025 Charles H. Dow Award by the @CMTAssociation, the leading global association for technical analysis.
This recognition is especially meaningful because, over the years, this same award has celebrated research by traders and quantitative thinkers who inspired me early in my career — from Larry Williams to Andrew Thrasher, Larry Connors, @leadlagreport, and @charliebilello, among others.
A heartfelt thank you goes to my co-author @GaryAntonacci the father of Dual Momentum Investing, for sharing with me his incredible knowledge and wisdom in quantitative research, particularly around trend-following models. Writing this manuscript together has been a journey of passion and enthusiasm — hopefully the first of many more!
We look forward to presenting this work at the CMT Spring Summit 2026.
For those interested in exploring our research, in the comments you find some useful materials.
✉️ If you have any questions, feel free to DM me or contact me at [email protected]
@_TBone_Pickens #CMTAssociation #TechnicalAnalysis #QuantResearch #MomentumInvesting #TrendFollowing #DualMomentum

Chasing Skew in Trend Following
We analyzed more than 1,500 trades from a futures trend program to dig into one of the most praised characteristics of CTA funds… positive skew.
Our findings suggest that the positive asymmetry often credited to trend following isn’t quite what investors actually experience day in, day out…
Interestingly, our results are in line with what Robert Carver @investingidiocy (former Portfolio Manager at Man AHL) and Eric Crittenden (Founder and CIO of Standpoint) have pointed out.
The full article, including the program’s trading rules, is available at the link in the first comment. 👇

We are proud to open the Concretum Interview Series with @GaryAntonacci.
As many quants will know, Gary is the author of Dual Momentum Investing, a book that has influenced how a generation of practitioners think about momentum.
What began as a simple exchange of ideas has become a collaboration with Concretum, leading (among other things) to our award-winning paper A Century of Profitable Industry Trends.
In this conversation, we retrace Gary’s journey from Wall Street in 1974, through his years allocating capital to traders such as Paul Tudor Jones, Richard Dennis, and Jim Simons, to the way he designs his proprietary trading models today.
We also reflect on what it means to remain intellectually curious... and on why he has never been afraid to question the very ideas that made him so well known.
You can read or listen to the full interview by using the link in the first comment.

Backtesting is definitely one of the most important steps when conducting quantitative trading research.
If done correctly, it can become your strongest research tool. If done as an AI-generated black box, it can quickly become your worst enemy.
In our new article, we guide you step by step through the backtesting of an intraday trend strategy, using one of our public papers as a practical case study.
From database construction and signal implementation to position sizing and performance evaluation.
We hope this serves as a practical guide for anyone interested in backtesting using Python or MATLAB.
More details in the first comment 👇

Can Rebalancing Flows Enhance Intraday Trend Trading?
Academia has repeatedly identified institutional activity as an important driver of short-lived market phenomena.
Yet, to our knowledge, no study has examined whether expected stock–bond rebalancing flows could help explain (or predict) intraday momentum effects.
Today, we show how anticipating these flows can enhance the effectiveness of intraday trend signals in both equity and fixed-income markets.
For full methodology and the trading rules use the link in the first comment. 👇

We are glad to announce that next week, we are launching Concretum Interviews, a new series with top quant traders from around the globe.
We will discuss strategy design, infrastructure, data sources, risk management, financial instruments, and other valuable topics that systematic investors could benefit from reading about.
Given the extensive experience of many of our interviewees, we will also explore interesting anecdotes from their successful careers.
Whenever possible, we will add a Concretum touch: backtests, tables, and charts to examine the ideas discussed and help readers understand their practical implications.
We hope this new series will become a place where serious readers can discover new ideas, learn from experience, and explore how successful traders have been able to beat the market.
Stay tuned, and make sure to subscribe to receive the first interview in your inbox.
More info below. 👇

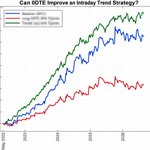
Can SPX 0DTE options improve the profitability of an intraday trend-following strategy on the S&P 500?
In our new article, we first introduce a SPY intraday trend model that, since 2007, would have generated a net CAGR of 20.8% with a Sharpe ratio of 1.20.
We then ask a different question: can we replace SPY exposure with SPX 0DTE options to add convexity and reduce downside risk?
This is the first in a series of articles in which we empirically assess how 0DTE options can be used by systematic traders.
Given the enormous growth in 0DTE trading, particularly among retail investors, understanding what these products can and cannot add to a trading strategy is crucial for long-term success.
You can read the full article using the link in the first comment.
🤖 Made with AI

It’s an honor to see our research piece, “Does Trend Following Still Work on Stocks?”, co-authored with Alberto Pagani and Cole Wilcox, CIO, featured in #TheMarketTechnician, the official journal of the Society Of Technical Analysts Limited.
In the article, we discuss the main findings of our research, which received the 2025 Diaman Partners Ltd Award, from the full rules behind a breakout system designed to capture the stocks that really matter, to the more practical aspects of implementing the strategy.
We also take the opportunity to highlight the 39th Annual #IFTA Conference, taking place in London on October 9–10, 2026.
With speakers including Perry J. Kaufman, @LindaRaschke , @Zoesbiz, @ROBINMESCH and many others, the conference should offer plenty of interesting ideas and perspectives for anyone interested in technical and quantitative market analysis.
You can read the full issue of The Market Technician for free through the link in the first comment.


Here you can read the full journal for FREE
issuu.com/societyoftechnical…

Yesterday’s market price action was clearly one of the best possible regimes for intraday trend models.
But exploiting intraday trends successfully nowadays requires a bit more sophistication than simply following the direction of the market.
The end-of-day reversal into the close fits particularly well with the findings of our recent research on intraday trend seasonality.
For anyone trading intraday trend strategies, we strongly recommend taking a look at the piece.
Article: concretumgroup.substack.com/…

In our new article, we share the Python code to backtest a 100-year trend-following strategy across U.S. sectors.
This piece is inspired by our paper, A Century of Profitable Industry Trends, co-authored with @GaryAntonacci and recipient of the 2025 @CMTAssociation Charles H. Dow Award.
We’re sharing the full backtest code, together with 100 years of historical data.
You can run it directly online and change the parameters as you like. You will quickly discover that the parameter choices used in the paper were far from optimal.
Read the article, build your own version, and share your results!
Full article in the first comment 👇

Earlier this month, we published “How to Generate Alpha From Rebalancing Flows,” a piece that sparked considerable interest among our readers.
As it turns out, investors are becoming increasingly receptive to the idea that the technical flows of large market participants can produce meaningful price anomalies.
In our new article, we present further evidence of this phenomenon and propose a simple refinement to our base ETF strategy, bringing its net-of-fee Sharpe to 1.33 over our historical sample.
As always, you can find the full methodology and implementation details at the link in the first comment.
